【Estée Lauder Thorough Analysis Part 4/Final】: The Fortress of the loader clan that holds 84% voting rights—14A reveals the light and shadow of CEO succession and internal governance within the family
ICHIRO|Anatomy of Financial Statements Lab
Over the course of Parts 1 through 3, we examined Estée Lauder Companies Inc.'s business model, the appearance of P/L recovery due to impairment write-downs, and the reality of a fragile balance sheet and looming debt repayment.
Here, we encounter a decisive question that many investors and businesspeople have.
“Why was there such excessive inventory left unmanaged, with the initial actions delayed until a huge impairment was recorded?”
“With the stock price depressed and the rating on the brink, why can’t activists refresh the board?”
“Despite being a global mega-brand, why isn’t there even a rumor of a hostile takeover by LVMH or L’Oréal?”
For a normal publicly traded company, it would be a stage where fierce market pressure would threaten leadership changes, and executives would be replaced immediately. Yet in Estée Lauder, external acquisition attempts or external shareholders forcing leadership changes were legally and impregably blocked—100% impossible—forming an iron fortress.
The key to solving this mystery is not the annual report (10-K) but the annual shareholder meeting notices and proxy solicitations (SCHEDULE 14A / DEF 14A, filed September 25, 2025) submitted to the SEC (U.S. Securities and Exchange Commission), where the details are precisely recorded.
In the final installment, we will dissect this primary material to reveal the mechanics of the LaL family’s control, the true identity of the top shareholder fund, and the truth behind the high-stakes leadership overhaul carried out under extreme pressure.
This time, the past Estée Lauder analyses can be found here?
Here are past articles from the Home Depot series in the previous corporate analysis?
■ Architecture of All 4 Analyses and Complete Integration Map
We unify Estée Lauder’s business, finance, and governance linkages on a single map.
【Part 1: Revenue Model / Fixed Costs】
  Flagship products with a 75.5% gross margin — yet 35,000 salespeople and large fixed costs at the Downstream factory (SG&A about 64%)
          │
          ▼
【Part 2: Income Statement (P/L)】
  Operating income recovery of $1,565 million, over 80% of which came from impairment write-downs (about $1.29 billion). Skincare monopolizes roughly 88% of segment profit
          │
          ▼
【Part 3: Balance Sheet (B/S) & Cash Flow (C/F)】
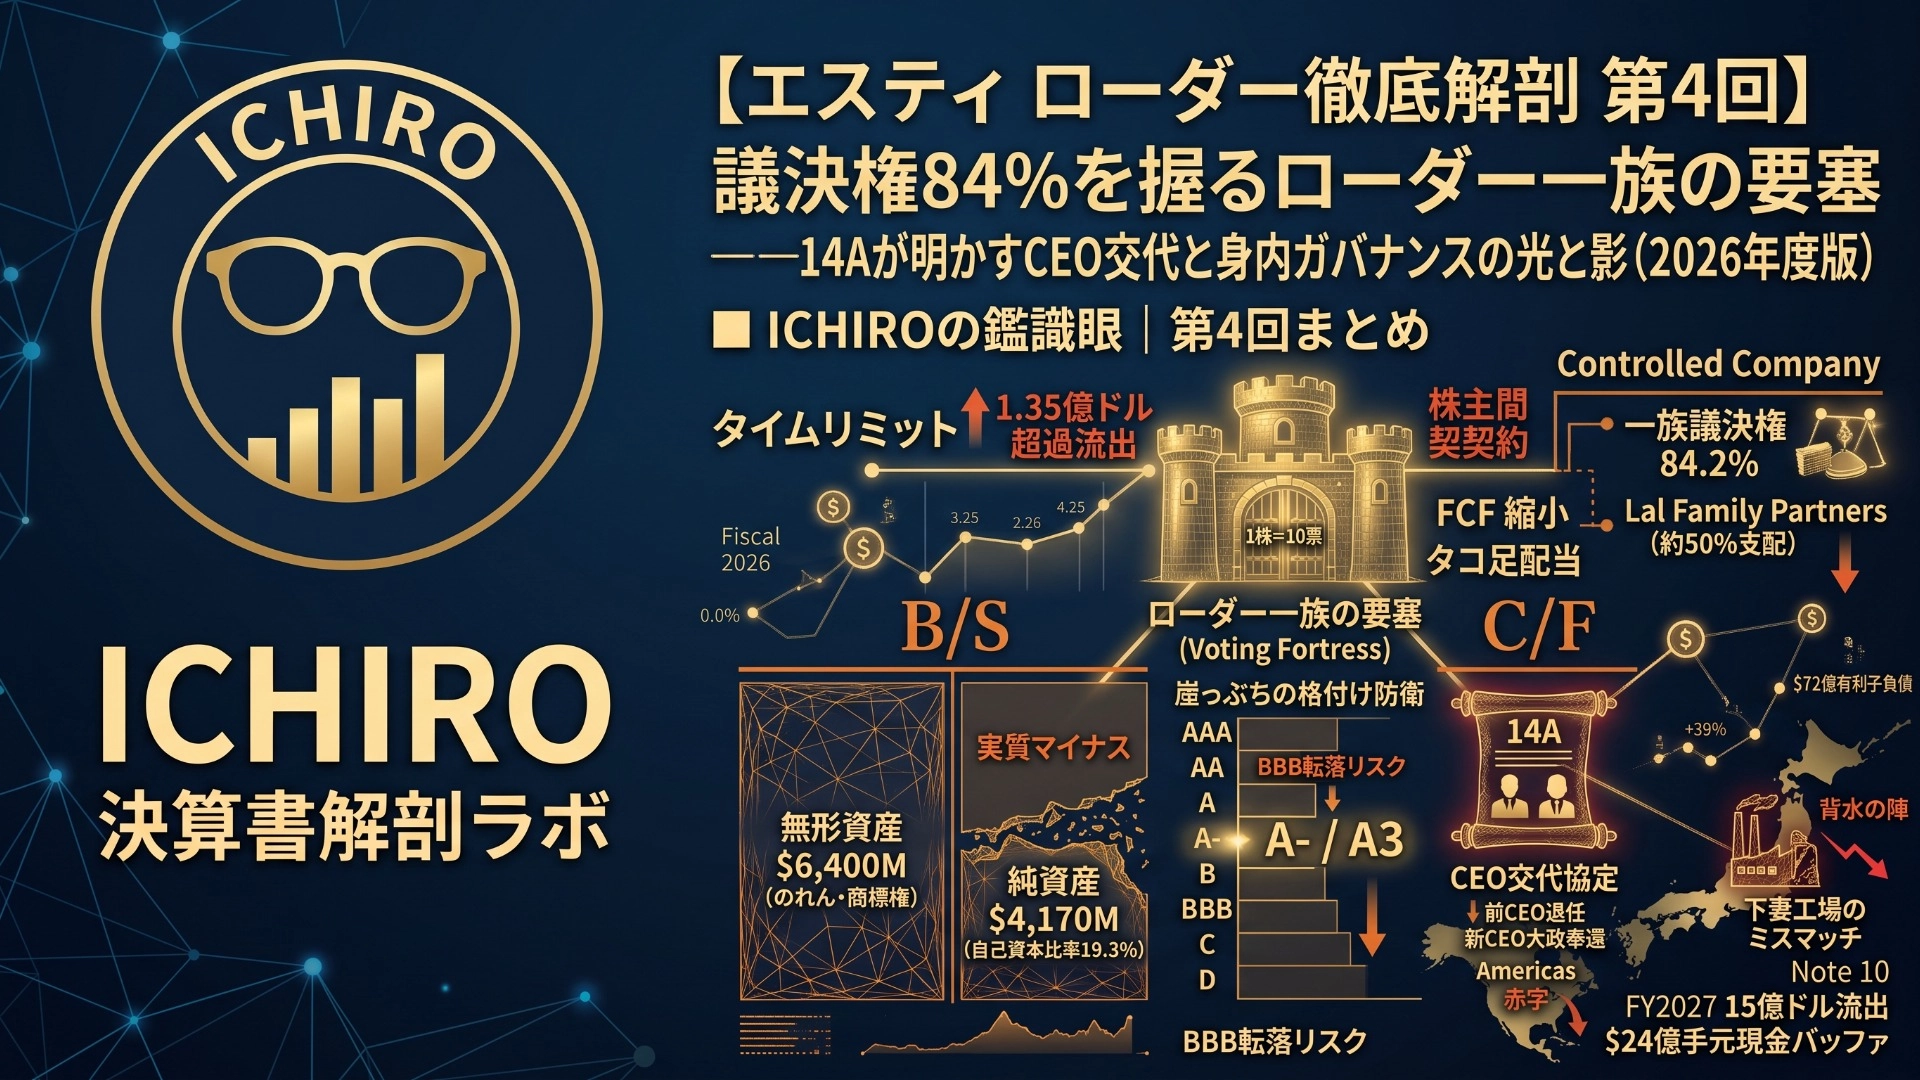
  Net assets $4.17 billion vs. intangible assets $6.4 billion. Rating “A- / A3 Negative” and an outflow of $1.5 billion in FY2027
          │
          ▼
【Part 4: Proxy Solicitation (14A) & Governance】★This article (paid area)
  [Capital and voting rights] 34.8% stock ownership with 1 share 10 votes Class B, fully controlling “84.2%” of voting rights
  [Absolute fortress] Lal Family Partners (about 50% control alone) + a shareholder agreement that blocks external intervention 100%
  [Top leadership change] Former CEO Frida steps down, Chairman William relinquishes executive powers, grand return of governance to new CEO Fabri
To readers: The following is a paid area
Thank you very much for reading this far.
In the paid area of this article (Part 4, final), based on raw SEC-submitted materials (SCHEDULE 14A), we will fully disclose the following: “84% voting rights by a founding family control,” “the true identity of the top shareholder fund,” “the terms of the CEO change agreement,” and “the reality of executive pay reductions.”
【Core themes analyzed in the paid area】
【Confirmed calculation】Why can 84.2% voting rights be held against 34.8% capital?:A legitimate fortress of dual-class shares calculated from the number of issued Class A and Class B shares
The identity of the top shareholder list’s lead “Lal Family Partners, LP (19.18%)”:A rock-solid shareholder agreement that even BlackRock and Vanguard cannot beat
What 14A reveals about the CEO transition:The departure agreement of former CEO Frida and the true reason for the grand handover to new CEO Stéphane de la Favry
The reality of a 28% cut in management compensation and zero incentive pay:The cold numbers facing executives while 10,000 people were laid off
Financial forensics conclusion: Is founder governance a shield or a shackle for restructuring?The final conclusion before the FY2027 cash outflow deadline
Additionally, as a completion bonus for this series, two practical tools to help you inspect financial statements and governance disclosures are fully included at the end.Two Practical Toolsto be used for self-checking at the end of the article.
【Two Major Perks for Purchasers】
Estée Lauder (EL) Four-Part Financials and Governance Comprehensive Diagnostic Summary Sheet
Integrated diagnostic sheet covering P/L adjustment strength, quality of B/S, C/F defense line, and capital/voting rights structure
Next Form 10-Q & Next Shareholders Meeting “Five Key Observations” Checksheet
A KPI checklist to open and verify when the next earnings release and meeting notices are disclosed
If you wish to understand the hidden dynamics of control, people, and the true nature of the company beyond surface indicators, please proceed to the paid area from here.