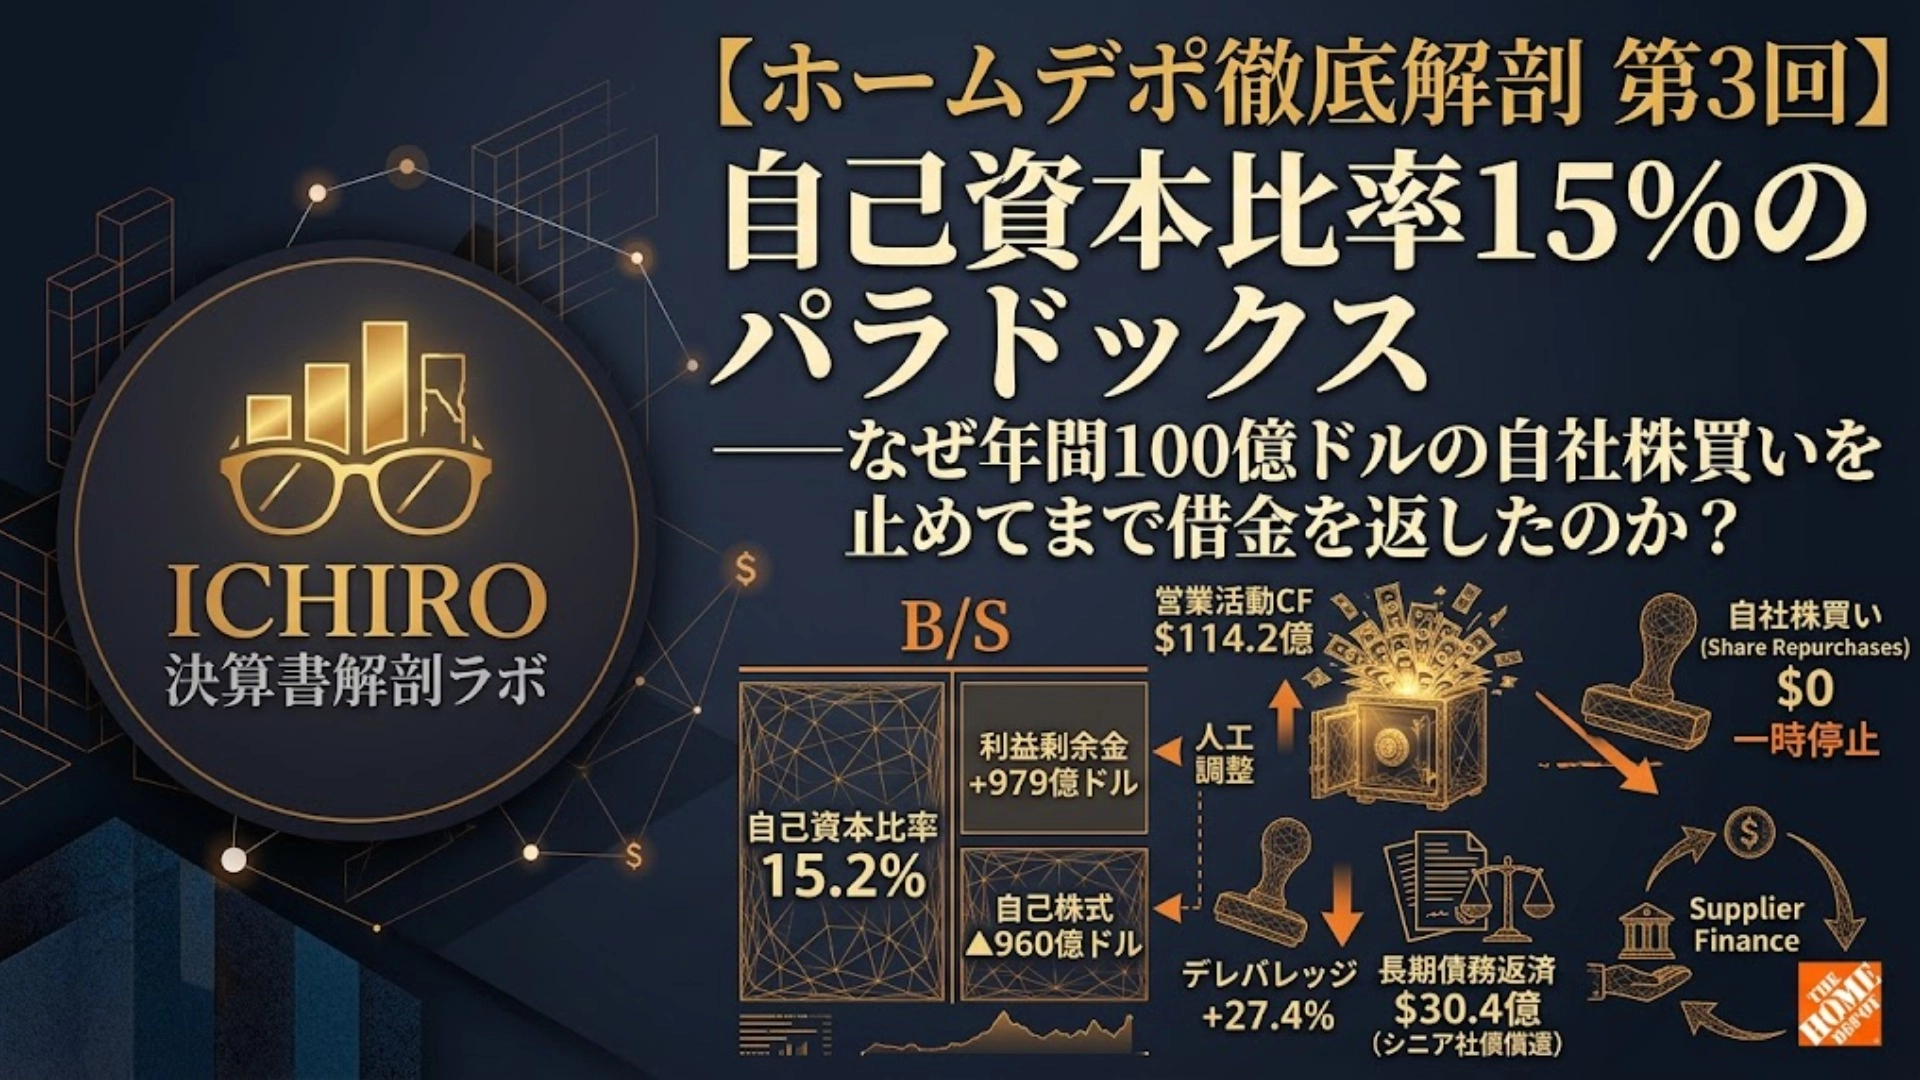
【ホームデポ徹底解剖 第3回・完】:The paradox of a 15% equity ratio—Why did they repay debt by stopping $10 billion per year of buybacks?
ICHIRO|Decision Statement Anatomy Lab
In the first installment we unraveled the current inflationary environment and the benefits of tariff refunds, and in the second installment we explained the structural shift from bricks-and-mortar retail to a “BtoB building materials wholesale platform.”
In the final installment of this series, we delve into the depths of The Home Depot, Inc.'s financial statements, which in ordinary explanations are often superficially framed as "high risk due to a low equity ratio" or "shareholder returns reduced as buybacks were halted."
A close reading of the 2026 Form 10-Q reveals a balance sheet design that appears exhaustively calculated, and a cash-flow structure that generated $11.4 billion in cash over six months.
Past installments in this corporate analysis Home Depot series are available here?
Past analysis on Palantir series is available here?
■ Summary Matrix for All 3 Parts
We整理 the main points dissected in this series and the numerical basis on the financial statements.
| Issue / Theme | Key figures and basis disclosed | Conclusion of the financial statement anatomy |
| Part 1: The Current State of the Housing Market | P/L, MD&A (P.15–17) Same-store customers −1.0%, average ticket +2.8% Tariff refunds: about $685 million | Maintains a net profit margin of 10.0% through price pass-through from inflation and a temporary tariff refund reversal accompanying the Supreme Court ruling. |
| Part 2: Shift to BtoB Wholesale | Note 1 (P.6), Note 10 (P.18) Accounts receivable from professional contractors about $3.56 billion Wholesale (Other) sales about $5.05 billion | Covers roofing, interiors, and HVAC through continuous acquisitions of SRS, GMS, Mingledorff's. Encompasses pros with substantial credit lines (on-credit terms) to surround them. |
| Part 3: Capital Policy and C/F (this article) | B/S (P.1), C/F (P.5) Operating cash flow about $11.42 billion Long-term debt repayments about $3.04 billion | An artificially thin capital structure with a 15.2% equity ratio. A capital discipline that stops annual buybacks of $10 billion and leverages the cash generated to deliver deleveraging. |
■ 1. 【B/S Mystery】 Is a 15.2% equity ratio a “danger zone”?
Looking at Home Depot’s balance sheet (P.1), the equity ratio is at a relatively low level compared with typical retailers.
Balance Sheet Summary (as of 2026-08-02 / units: millions of dollars)
At first glance, the capital structure appears heavily reliant on debt, but in reality it is shaped by two colossal figures in the shareholders’ equity section.
Peculiar Structure of the Equity Section (P.1)
Retained earnings: +$97,949 million (about $97.9 billion)
Treasury stock, at cost: −$95,971 million (about −$96.0 billion)
【Offsetting Structure of the Equity Section】
  Retained earnings accumulated from past operations
  ┌──────────────────────────────────────────────────────────┐
  │  Retained earnings (internal reserves): about +$979 billion     │
  └──────────────────────────────────────────────────────────┘
                            │
                            │(absorbed and disappeared by share repurchases)
                            ▼
  ┌──────────────────────────────────────────────────────────┐
  │  Treasury stock (deduction from equity): about −$960 billion     │
  └──────────────────────────────────────────────────────────┘
                            │
                            ▼
  Net shareholders’ equity (net assets): about $16.6 billion (equity ratio 15.2%)
The company has, for decades, returned the bulk of its earnings to shareholders via share buybacks.
The 15.2% equity ratio is not a result of financial distress from deteriorating business; it is an “artificial thinning” caused by management deliberately compressing equity to maximize capital efficiency (ROE/ROIC).
Then why did the company abruptly halt this aggressive capital compression strategy and stop buybacks entirely, which had been running at around $10 billion annually?
【Paid Area Table of Contents and Anatomy Agenda】
Chapter 1: The true meaning of stopping $10 billion in buybacks annually
— The explicit terms on P.20 reveal the CEO’s coldly prioritized order
Why did Home Depot, which had bought back roughly $960 billion (net of equity deduction: −$95,971M) in the past to compress equity to the extreme, maintain “zero acquisition value” since March 2024 and even deny any reopening in 2026?
The overarching plan to return EBITDA multiples to a 2.0x level as a top priority, even if it means suspending generous returns to shareholders temporarily, and the overall scenario for credit rating defense.
Chapter 2: The “Alchemy of Cash Creation” generating $11.4 billion in six months
— Reality of Supplier Finance and Buying Power in Note 1 (P.6)
Mechanism where half-year operating cash flow ($11,422M) exceeds net income ($8,055M) by about $3.4 billion.
Supplier finance program (outstanding balance $542M) that extends payment terms to suppliers without causing their bankruptcy, illustrating the leverage Power of large retailers in working capital.
Chapter 3: On the ground, $3 billion debt repayment
— Why they chose lump-sum cash repayment over rolling over in a high interest environment
In an environment with interest rates above 5%, the rationality of not issuing refinancing debt for matured senior notes ($28 billion total) and instead annihilating them with operating cash flow.
Estimated and tested how future interest payments would change after reducing long-term debt by about $2.4 billion (to $43,892M) over six months.
Chapter 4: Structure of artificial balancing: equity ratio from 12.2% to 15.2%
— The true safety created by retained earnings (about $980 billion)
It is a fatal error to judge financial health as fragile merely by the 15% equity ratio.
Between stopping buybacks and continuing higher dividend payouts (quarterly $4,643M), retained earnings accumulate to $97,949M, and the balance sheet rapidly repairs itself—this process explained.
? Exclusive for Buyers: How to use and interpret 2 practical tools in practice
This article fully includes two practical tools (matrix and checklist) so readers can directly apply them to future investment decisions and comparisons with other companies. We explain the design intent and how to use them effectively.
Gift 1: 3-Part Comprehensive Finance & Capital Trap Summary Sheet (2026 Q2)
Design intent:A screening matrix that allows an at-a-glance, cross-sectional view of the “GAAP surface numbers” shown in earnings releases and the structural reality behind the SEC primary disclosures (10-Q).
How to use in practice:
Benchmark for peer comparison:Use as a baseline when analyzing peers like Lowe's (LOW) to compare differences in ticket size, accounts payable ratios, and buyback policies.
Immediate removal of noise:Excluding one-off factors like tariff refunds (about $685 million) to instantaneously deduce base gross margin and operating margin.
Credit risk and cash flow risk awareness:Identify how professional supplier volume (accounts receivable about $3.56 billion) and supplier financing distort cash flow from a fixed point of view.
Gift 2: Next Time Form 10-Q “Five Point Fixed Observations” Checklist
Design intent:The moment the next quarterly report is filed with the SEC (EDGAR), this professional-grade checklist guides you to open which original sections (MD&A, footnote numbers) and verify which numbers in five minutes—without waiting for press releases or media analyses.
Practical usage:
The power relationship between customer counts and average ticket (1):Check immediately whether the reliance on price increases in a high-rate environment has reached its limit by looking at the MD&A trend in transactions.
Detecting erosion effects (2):Verify the P/L real strength after one-off tariff refunds have fallen away.
Credit & CF risk monitoring (3-4):Early detection of deteriorating leverage over professional receivables and growing power dynamics with suppliers from Note 1.
Signals of capital policy shift (5):Notice any changes in management guidance regarding debt rollovers or the resumption of buybacks (Note 5 / liquidity section).
Core of financial forensics: Why this anatomy is necessary now
Surface earnings announcements and analysts’ summaries highlight headlines like “revenue growth and profit growth” or “high operating cash flow.” Yet,the live, gritty financial strategy of leveraging through acquisitions and, in a high-rate environment, progressing toward self-amortization (deleveraging) cannot be seen unless you connect the notes in Form 10-Q meticulously.From here on, I will quote the relevant pages and note numbers from the primary disclosure documents directly, presenting only the facts of the financial operations behind the numbers.
The following sections provide the raw figures and the operational truth behind them, not press summaries.