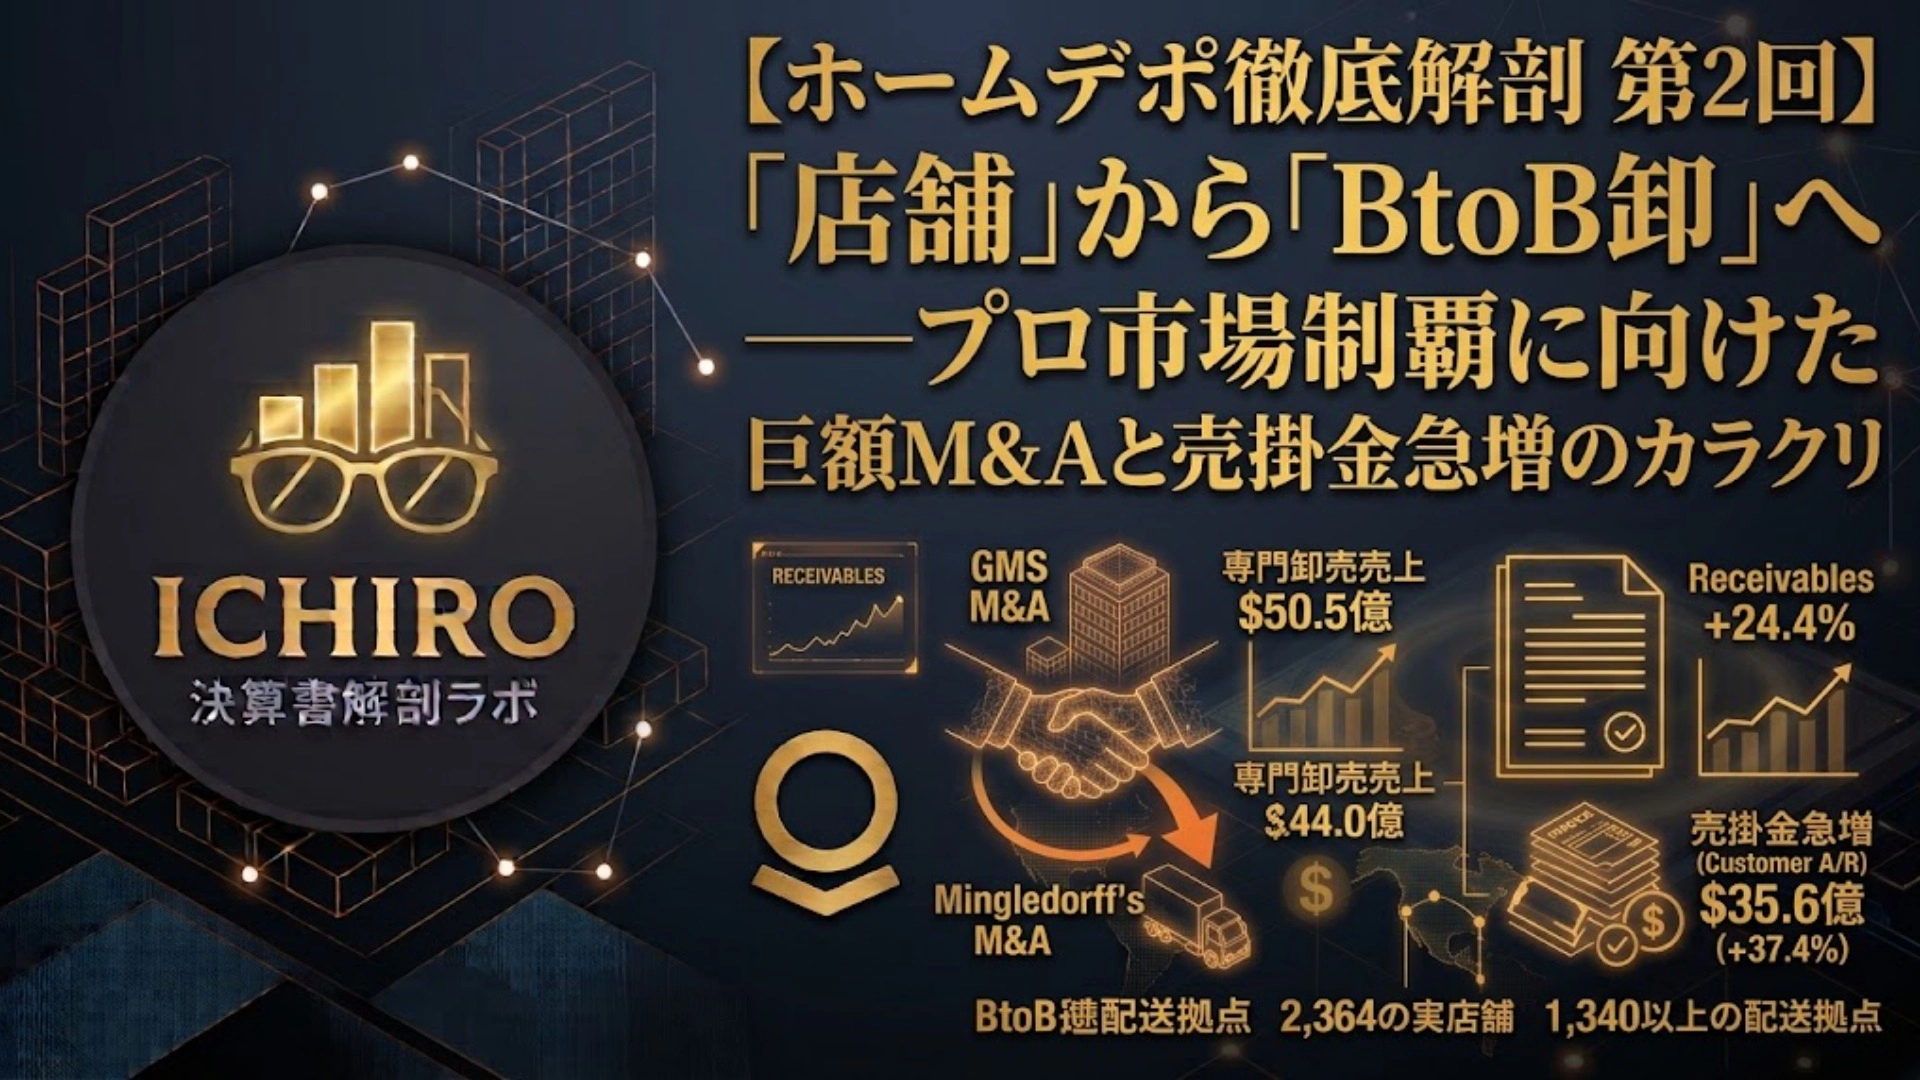
【Home Depot Thorough Analysis Episode 2】: From "Store" to "BtoB Wholesale" — The Mechanism of a Massive M&A Aimed at Dominating the Pro Market and Rapid Increase in Accounts Receivable
ICHIRO|Decision Book Dissection Lab
In the first episode, as inflation and cooling of the housing market reduce the frequency of visits by ordinary consumers, The Home Depot, Inc. unravelled how it maintained a net profit margin of 10.0% through “higher average ticket size (+2.8%)” and “temporary tariff refunds (about $685 million).”
However, the company’s management isn’t merely relying on raising prices at existing stores to weather this difficult period. What is underway at present is a tectonic shift in the business model itself that goes far beyond the long-standing flagship structure of “orange warehouse-style home centers.”
As evidence, when you open the 2026 Form 10-Q for the second quarter, a structural change occurs in the assets section of the balance sheet. Accounts receivable, net, surge from about $5.6 billion to about $7.0 billion in just six months, an increase of roughly $1.4 billion (+24.4%).
In a retail chain where cash and credit card payments are supposed to be immediate, why is there such a massive amount of “on-the-account” credit sales? The background lies in The Home Depot’s strategy to lock in the Pro market by investing over $24 billion in total funds.
Here are past articles in this Corporate Analysis Home Depot series?
Here are previous articles in the Palantir series?