Trade AI Forecast October 3 Points to Watch in the Market
This article was posted on October 3, 2026 ⇒Latest related articles?
In the early week, the market is expected to be greatly influenced by the US employment statistics released last week, subsequent interest rate moves, and the crude oil market.
Of particular note are the US employment environment and the G7's release of oil and fuel reserves.

?FX Next Generation: One-Click FX Training
US job growth slows sharply in employment data
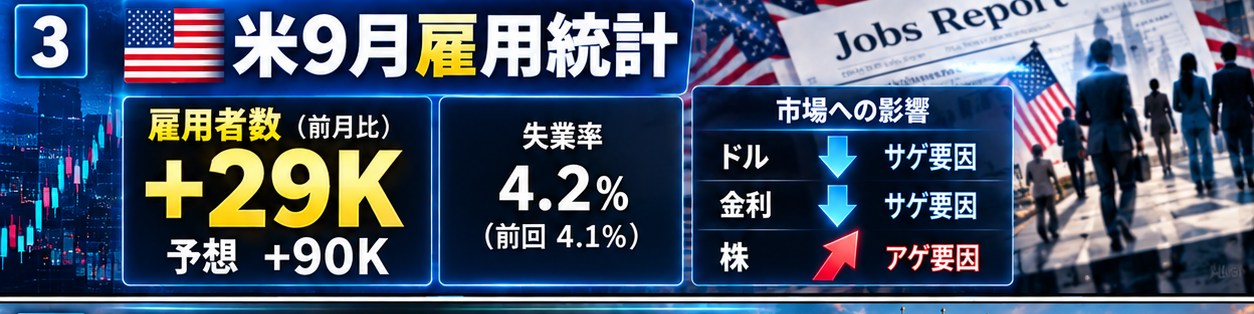
In the US September employment report released on October 2, nonfarm payrolls increased by 29,000, well below market expectations of 90,000. This miss indicates a significant slowdown in hiring.
The unemployment rate rose from 4.1% to 4.2%. Moreover, July and August payrolls were revised down by a total of 60,000, underscoring a cooling labor market.
In response, expectations for a rate hike by the Fed in October have receded. CME FedWatch now shows an 86.2% probability of holding rates at the October meeting. The stock market rose with the S&P 500 up 0.7% and the NASDAQ up 1.2%.
However, the US 10-year Treasury yield remains in the mid-5% range. On October 1, it touched as high as about 5.35%, a near 24-year high, and it held ground after the employment data.
In other words, the current market reaction is basically as follows:
Dollar: downward pressure
US stocks: upward pressure
Long-term interest rates: expectations for hikes have diminished but remain high
and a tendency to stay elevated
However, weak employment alone does not guarantee a major shift in monetary policy. The Fed is scheduled to hold a policy meeting on October 27–28, and data related to inflation need to be reviewed beforehand.
G7 moves to release oil reserves
Another major factor is crude oil.
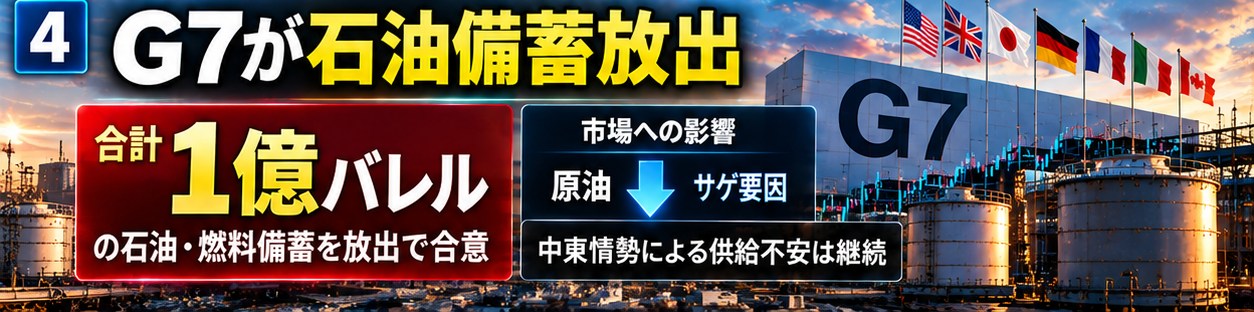
On October 2, the G7 agreed through the IEA to release up to 100 million barrels of oil and fuel reserves. The releases will occur over four months, with a large release planned for the first 20 days for diesel. It is also expected that this 100 million barrels includes the pre-announced 400 million barrel IEA release brought forward from March.
In response to this news, oil prices faced downside pressure.WTI crude (November contract) on October 2 closed around $91 per barrel, down about $1.8 from the previous day. Brent crude briefly dipped below $100.
Nevertheless, it would be premature to assume an easy downward trend for oil. Ongoing Middle East supply concerns, along with reports that Chinese refineries have stopped exporting fuel outside Hong Kong and Macau, may further tighten Asia’s fuel supply.
Therefore, for oil, several factors are in play:
Reserve releases: downward pressure
Middle East tensions and supply concerns: upward pressure
China's fuel export halt: upward pressure
and more
Attention on Japan’s monetary policy too
In Japan, the government is reorganizing communications as Prime Minister Kishida’s administration is perceived to be “inflation-friendly.”
In a October 2 press conference, Finance Minister Shunichi Suzuki stated that “the current situation is not deflation,” and that unorthodox monetary easing and YCC are over, with the restrictive monetary policy phase already ended.
Finance Minister Katuyama also indicated in an interview with the Nikkei that the government’s messaging will be made into a “one voice.”
Meanwhile, an extraordinary Diet session is convening on October 5, and Prime Minister Kishida is expected to deliver a policy address in both houses. The plan is to seek understanding for a reduction in the consumption tax on food, and statements regarding fiscal management and government debt issuance are awaited.
In Japan, attention is needed not only on the yen but also on Japanese government bond yields and the impact on the Nikkei Stock Average.
Key events for the start of the week
On October 5, the US ISM Non-Manufacturing Index (Services) is scheduled to be released in Japanese time at 23:00. It will provide further evidence to gauge the Fed’s monetary policy outlook after the employment data.
At the start of the week, the question is whether the downward revision of US payrolls and the possibility of rate hikes will persist, or whether oil prices, high long-term interest rates, and Japan’s policy factors will weigh on the market.
The Trade AI Forecast organizes the impact of publicly available news and economic information on the market. It does not guarantee actual price movements.
Practice and verify freely with a completely risk-free trade simulator!
Details of One-Click FX Training