20 items to check before buying EA. Six dangerous answer combinations to spot: averaging down, martingale, and no stop loss.
I am the director of FX Grail Research Institute. I am a 50-year-old systems engineer who records attempts to verify and deconstruct automatic trading methods that look “possible to win,” using past data.
In the articles on September 26 and 29, I read the numbers on the product pages one by one. Today, before buying an EA (a program that automatically executes FX trades), I will read the 20 items in combination.in combinationand interpret them.
September 26 article “What is PF? Three scenarios where even the PF 1.5 on an EA product page would still be in the red”:https://www.gogojungle.co.jp/finance/navi/articles/126730
September 29 article “Why a 90% win-rate EA is dangerous”:https://www.gogojungle.co.jp/finance/navi/articles/126847
The numbers appearing in this article are all calculation examples for explanation purposes.They are not my own test results or performance.
Conclusion
When you look at product pages item by item, each one may look acceptable. The danger comes fromwhen you miss the answer pile by looking at them one by one, and they convergetogether.
Therefore, I will guard against two points below.
- Before opening the product page, write down in advance the phrase “I will not buy based on this answer.”
- Doubt the gap between the product page’s results and real trading performance.
In the free section, I will show five clusters of the 20 items and one of the riskiest combinations as a calculation example.
Three answers that look good when read one by one
Suppose a product page for an EA lists the following three items (calculation examples for explanation):
- Description of construction: If you lose, double the position size on the next trade
- Recommended capital: 100,000 yen
- Performance: profitable after 100 trades
The first is martingale (increase the next trade’s size each time you lose). No matter how many losses, as long as you win once next, you recover losses and make a profit. Read alone, this feels reassuring.
The second is the recommended margin (funds suggested to run that EA). With 100,000 yen, you can start with a small amount of capital.
The third is the number of trades. If you’re profitable after 100 trades, it doesn’t look like a structure that will collapse quickly.
When stacked, seven consecutive losses exceed the funds
We calculate the three together. Assume the first loss is 1,000 yen. This amount is after deducting trading costs (the difference between buy and sell prices and fees).
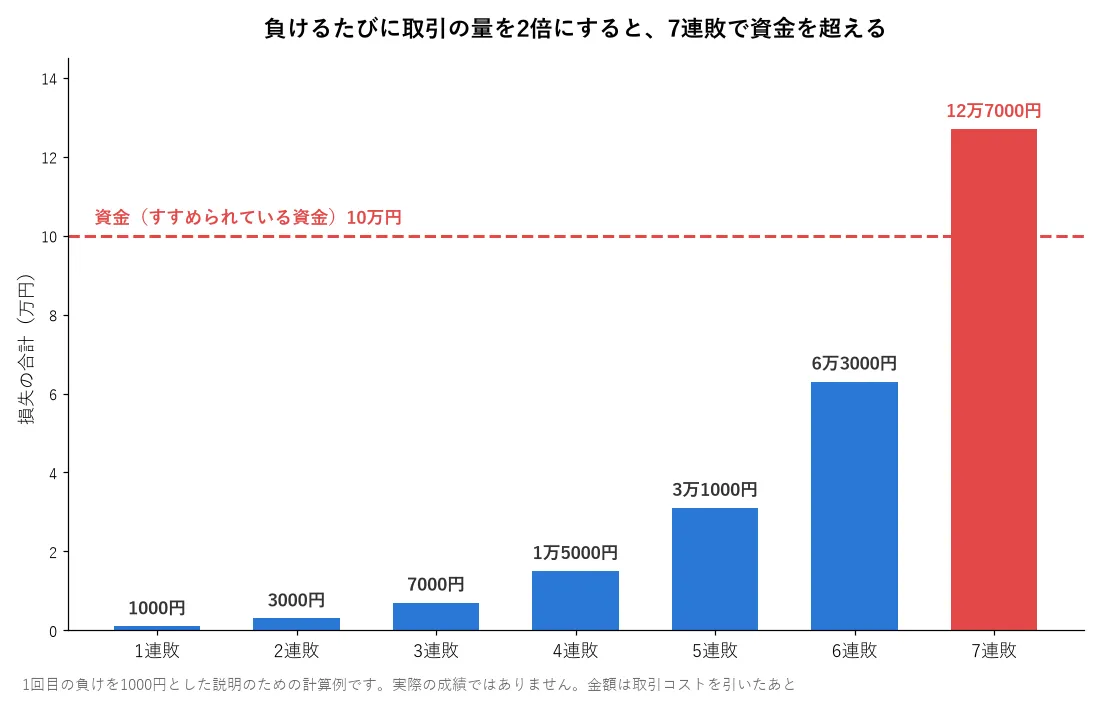
Because you double the trade amount after each loss, the loss amount also doubles: 1,000 yen, 2,000 yen, 4,000 yen, and so on. The total loss after six straight losses is 63,000 yen.
After six consecutive losses, remaining funds are 37,000 yen. The seventh trade, if you lose, would reduce funds by 64,000 yen.If you go to seven consecutive losses, the total loss becomes 127,000 yen and exceeds the 100,000 yen in funds.“If you win once next, you can recover” only holds when you still have funds to cover the next loss.
So, how often does seven consecutive losses occur? Assume win rate is 60% (four losses out of ten). The probability of seven straight losses from a given starting point is about 0.16% (roughly 1 in 600). It looks rare.
But as you place more trades, the story changes.The probability that seven straight losses occur at some point within 100 trades is about 9%. Within 1,000 trades, about 63%.
In other words, even if the 100-trade record is in the black, seven consecutive losses may haven’t occurred yet. If you continue the same construction up to 1,000 trades, there is a greater than even chance that at some point seven consecutive losses occur. If at that time your funds have not reached 127,000 yen, you will exhaust your funds.
The most serious issue is a combination where funds disappear all at once
Among the 20 items, the combination I take most seriously is, as in the above example,a design where losses appear all at once, funds cannot withstand it, and the short-term performance hasn’t yet shown the lossyet.
The reason is that there is no time to stop. If losses occur little by little due to trading costs, you can stop in the middle when performance deteriorates. This form can wipe out funds in a single day's string of losses, so by the time you notice, it’s too late.
A design that does not implement stop-losses (automatic exit when a certain line is reached) can also take this shape.
A martingale design (doubling the purchase after losses) can be the same. Which answer is dangerous depends on the combination described in the paid section.
The 20 items are grouped into five clusters
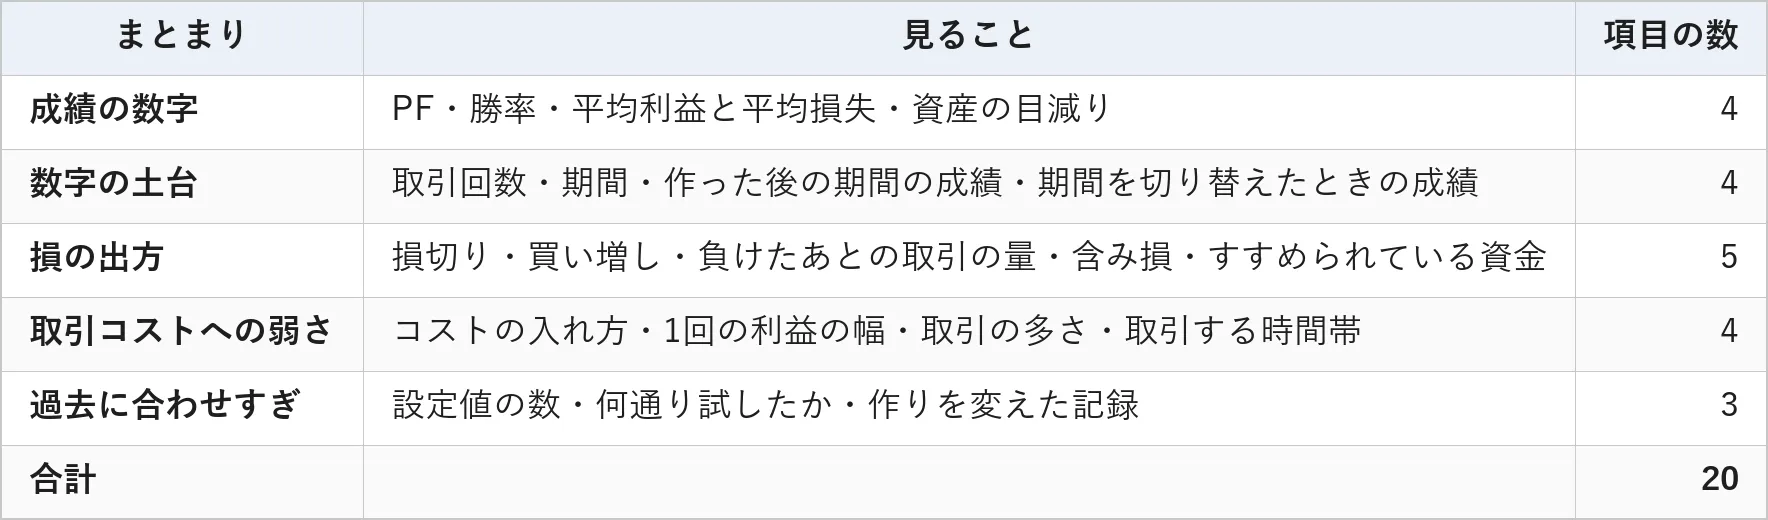
Even within a cluster, you cannot find dangerous combinations. The martingale example above spans two items of “loss shape” and “base numbers of trades.”
Two ways of thinking
Decide the criteria first.If you decide the standard after seeing good numbers, the standard becomes lax. You might think, “If PF (the ratio of total profits to total losses; below 1.0 is in the red) is so high, perhaps fewer trades are acceptable.” Therefore, before opening the product page, write down “I will not buy based on this answer.” It’s the same method I use to determine a cutoff before my own verifications.
Doubt the gap with real trading.The results on product pages are derived from backtested data or records run under fixed conditions. In real trading, trading costs vary with time of day, etc., causing results to differ. I currently compare results from my verification program with the trading software’s verification results for each trade, to measure the gap. I haven’t published the numbers yet, but it’s something you can doubt before buying.
Items included in the paid section (980 yen)
- A list of six dangerous combination explanations, the reasons for each, and how to confirm them on the product page (high win rate, trade size after a loss, averaging up, vulnerability to trading costs, overfitting to past data, and duration of performance)
- Tables showing the probability that seven consecutive losses occur somewhere and, for capital, how many times the first loss can be endured (multiplied) to endure that many losses
- Calculation example where a floating loss from averaging up does not appear in realized profit/loss
- Procedure to recalculate PF by adding trading costs from the product page’s average profit and average loss
- Examples of how to write criteria and a flowchart for pre-purchase checks
- Bonus: 20-item checklist (where to look and notes on potentially dangerous answers. space to copy)
Even the free portion can help distinguish today’s martingale and small-capital combinations.
Finally
At FX Grail Research Institute, when we see a good number, we first look for the conditions under which it would fail. In today’s example, the failing condition was “the total loss from consecutive losses exceeds the funds.”
The calculations and diagrams in this article were created with AI, and the numbers have all been cross-checked by programs.
We do not promise a method that guarantees profits. But we believe there is a grail to be found.
The grail I am seeking is a buy/sell rule that would not break even after factoring in trading costs, even in periods not yet seen. A single profitable martingale after 100 trades may be a counterfeit if seven consecutive losses have not yet occurred.
Even a fake that looks acceptable one item at a time reveals its true nature when you stack the answers. Write down a “not buy” answer before opening product pages, and read by stacking the answers. This alone can rule out one fake. Each fake you rule out brings you one step closer to the grail.
Glossary
- EA: A program that automatically executes FX trades
- PF: Total profit from winning trades ÷ total loss from losing trades. Below 1.0 is in the red
- Win rate: Proportion of winning trades
- Martingale: Increase the next trade’s amount after each loss
- Recommended margin: Funds recommended to run that EA
- Stop loss: Automatically close position when a set threshold is reached
- Nampin ( averaging up): Increase holdings without cutting losses when losing trades
- Unrealized loss: Loss on trades that have not yet been settled
- Setting value: The numbers inside the trading rules
- Trading costs: Money incurred on each trade. The spread between buy and sell prices and fees
This article is not investment advice. All numbers are calculation examples for explanation.