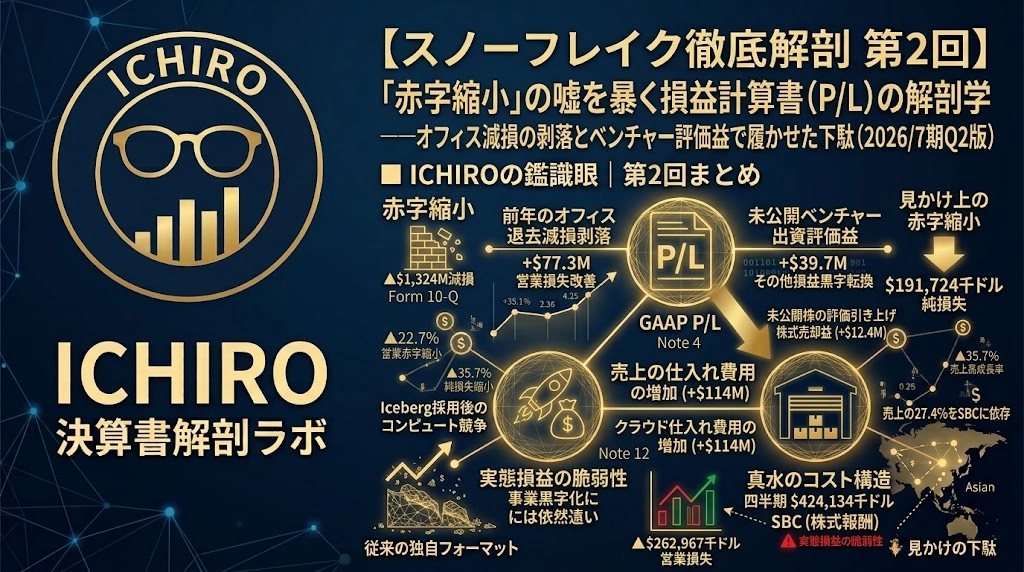
[Snowflake Thorough Analysis Part 2]: Exposing the Lie of "Reductions in Deficit" - An Anatomical Breakdown of the Profit and Loss Statement (P/L): The Unloading of Office Impairments and the Shoe Horn of Venture Valuation Gains Worn On (Version Q2 of FY2
ICHIRO|Financial Statement Anatomy Lab
Following the most recent earnings release, major US financial media and analyst reports have prominently argued that Snowflake is moving toward improved profitability. The strongest supporting evidence cited is the "significant narrowing of operating losses and net losses" shown on the income statement (P/L).
If revenue grows more than 35% year over year while the loss band narrows, it can initially appear that the company is "maintaining a growth trajectory while economies of scale are kicking in, bringing GAAP profitability closer."
However, a meticulous examination of the Form 10-Q filed with the U.S. Securities and Exchange Commission (SEC) (Q2 2026 as of July 31, 2026), including the income statement (p. 7), notes (Note 4), and MD&A (p. 53–60), reveals that this "narrowing of the losses" is not due to operational efficiency but is instead a "facade built by accounting-specific factors and outside operating gains," creating a showy impression.
Here is the previous Palantir series analysis?