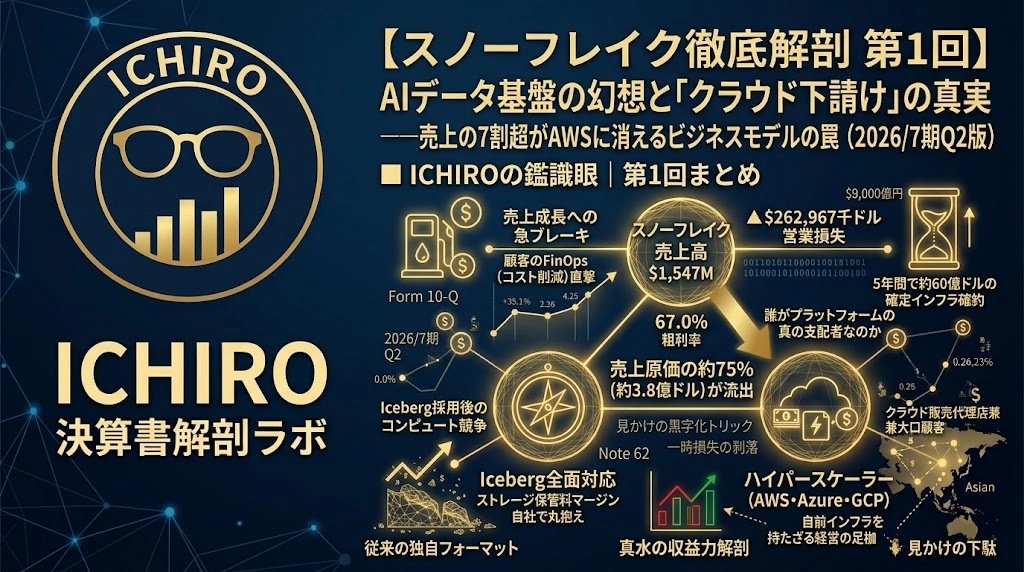
[Snowflake Thorough Analysis Episode 1]: The Illusion of AI Data Platforms and the Truth of "Cloud Subcontracting"—The Business Model Trap Where Over 70% of Revenue Disappears into AWS (2026/Q2 Version)
ICHIRO|Financial Statement Anatomy Lab
In the U.S. stock market, Snowflake Inc. (ticker: SNOW) is frequently talked about as the “winner of enterprise AI.” The company’s proposed “AI Data Cloud” is drawing intense market attention as a platform that integrates vast data from large enterprises worldwide and powers next-generation generative AI applications.
However, when we scrutinize the numbers in the Form 10-Q (quarterly report for the second quarter ended July 31, 2026) that the company filed with the U.S. Securities and Exchange Commission (SEC), a structural distortion in its business model, contrasting with the market’s flashy narrative, comes to light.
In this first installment of the series, we dissect from primary sources the fragility of the core revenue model—consumption-based (pay-as-you-go)—and the overwhelming power dynamic with major public cloud hyperscalers.
Here is the previous Palantir series analysis article from last time?