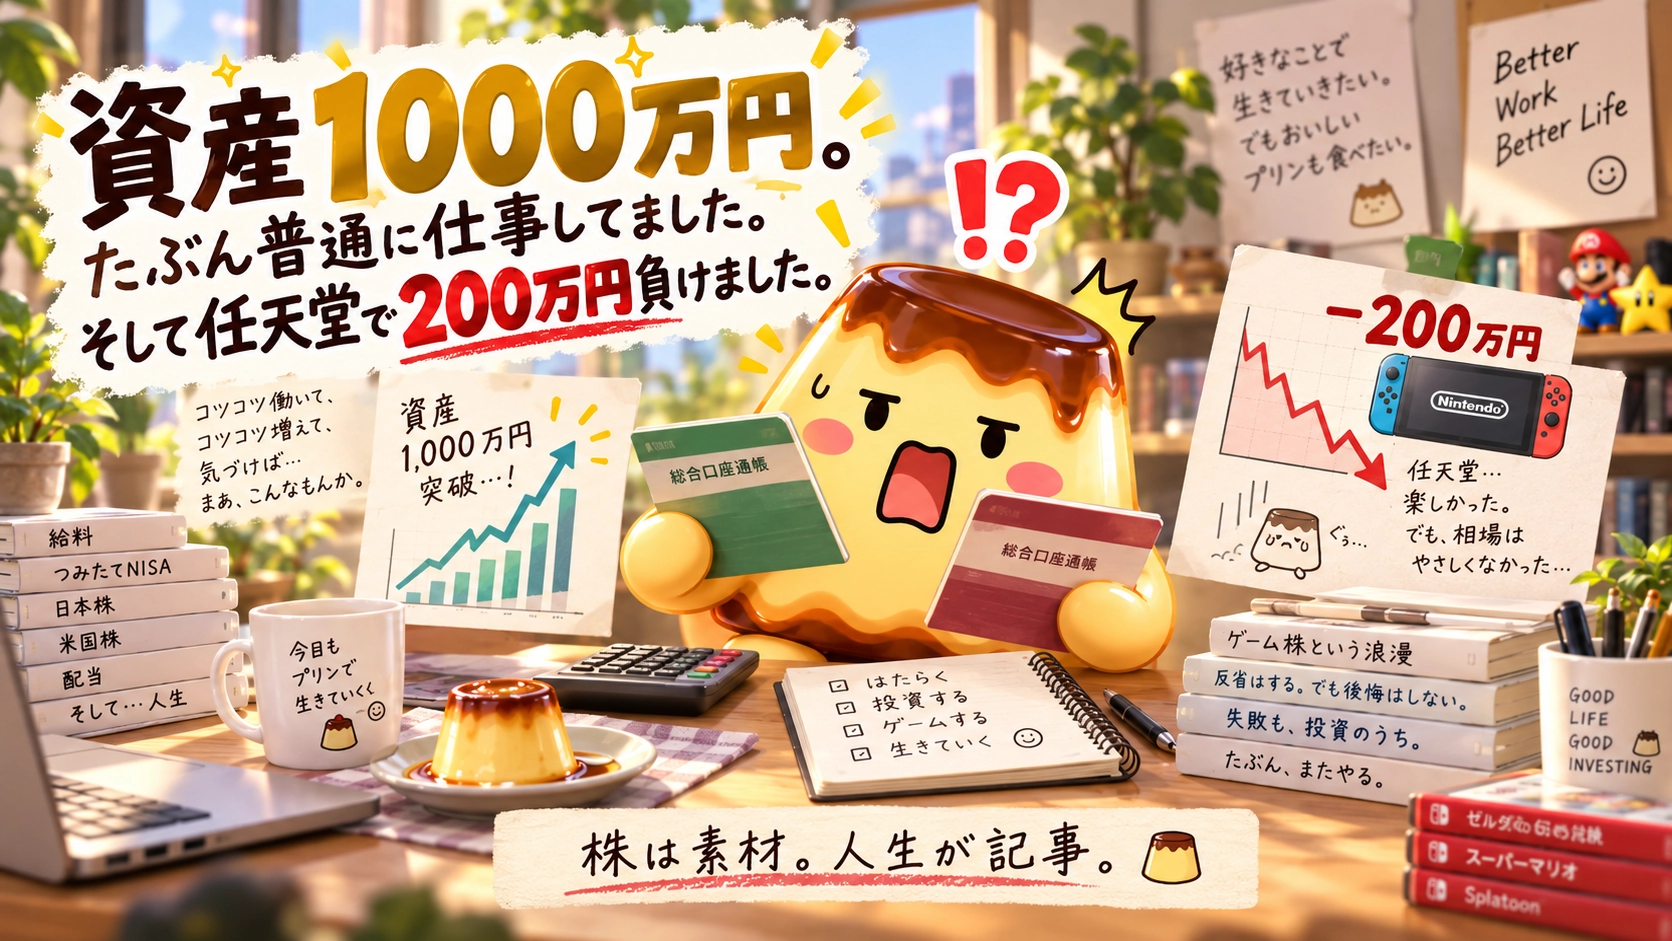
Assets 10,000,000 yen. Probably I was working normally. And I lost 2,000,000 yen at Nintendo.
If my 1000万円 achievement were to be made into a movie, the trailer would be like this.
A working man.
The salary that gets deposited.
Several passbooks gathered on the desk. The balance at the securities company.
And the man finally dared to touch the forbidden addition.
“Ah, I surpassed 10,000,000 yen.”
The whole of America went to work the next morning as usual.
Director: “Could we have a little more something happen?”
Me: “I lose 2,000,000 yen at Nintendo.”
Director: “Please say that first.”
Sorry. I made the trailer without permission.
Hello, I’m Princess Power (Purino-Water).
Last time, I wrote about how the 5,000,000 yen I saved through working became seed money for investing, and I lost about 14,000 yen at the initial Nissan Motor Company.
https://www.gogojungle.co.jp/finance/navi/articles/126361?via=authors_detail
This time is a continuation of that.
I have no memory of when I reached 10,000,000 yen.
If you add up multiple passbooks and the balance at the securities company,
“Ah, I exceeded it.”
That was about the feeling I had.
There was no “Yay!” either.
It was a sensation you wouldn’t have noticed if you hadn’t done the additions.
The colors of the world hadn’t changed. There was no celebratory cake.
I was probably working normally.
For a milestone in life, the reaction of the person himself wasn’t much different from when you check the total at a supermarket.
Even 10,000,000 yen would have liked to be welcomed a bit more grandly.
Sorry. I didn’t realize you were there until I combined them.
Before money started working, I was already working.
Even up to 10,000,000 yen, the basics were the same as when it was 5,000,000 yen.
Work. Get paid. Use. Save. Deposit.
As I wrote last time, I was leaving about 100,000 yen per month on average when including bonuses.
I went on trips. I hung out with friends.
It wasn’t a feeling of extreme frugality; I used what I should, and tightened what I should.
And I continued doing so.
The thing that worked best at the time, I think, was the ability to have deposits.
“Let money work for you.”
Nice, isn’t it.
So, when do I not have to work?
If you turned my former self into a financial product, the investment policy would be “the person comes to the office every day.”
Important documents have alarm clocks tucked into them.
Even though it’s an investor briefing, at the end everyone says, “Let’s wake up tomorrow too.”
What kind of gathering is this?
But in reality, the money I worked hard to save became the source for the next money.
I’m sorry for those who were waiting for compounding magic to appear.
For a while, you’ll continue to see my working-life footage.
I profited from BRICS.
Money has an international demeanor.
Of course, not only salary.
I held BRICS-based mutual funds, and that’s where I profited.
Brazil, where high economic growth is expected (Brazil), Russia (Russia), India (India), China (China) are four countries
that were collectively called “BRICs,” and were hugely popular at the time.
I have particular memories of emerging countries like Brazil performing well.
I don’t clearly remember the product names.
“Why did you choose that fund?”
If I were to explain that with today’s knowledge, someone smarter than my former self would emerge.
Anyway, the rise of funds was a tailwind as well.
Money back then had more overseas experience than I did.
I went to work.
Money went to Brazil.
Household head stayed domestic.
It’s a fairly large two-base lifestyle.
What’s abroad is money, though.
I myself worked properly and deposited money.
The world economy and my salary were converging in the same account.
And I also did individual stocks with the surplus funds.
Most trading was short-term or swing, and I hardly remember the specific stocks I bought and sold.
I remember making money, but I can’t recall the company names.
Still, stocks were quite interesting.
I wasn’t yet at the stage of spending hours looking at charts, deeply considering demand-supply and human psychology.
Back then, I wasn’t as hooked on stocks as I am now.
I did actually close the screen properly.
In later years, that became difficult.
If I could bring my later self here, my earlier self might say, “Maybe it’s time to close the screen.”
It’s your future.
When people talk about stocks, I want someone to say, “So what?”
There was a time when I felt lonely.
There was no one around who I could talk stock with.
Talking with friends was fun.
But I couldn’t talk about stocks. It was out of the question at work. There weren’t any people who invested in stocks, to begin with.
Whether it rose or fell today.
Whether I did this kind of trade or profited from mutual funds.
It wasn’t a request like, “Please tell me the next stock to buy.”
I just want to talk.
After watching a favorite movie, I want to tell someone, “That part was great,” that feeling.
If I could imagine a bonus for opening an account, it would be this:
“If you talk about stocks, there will be one person who asks, ‘And then what?’”
That would be nice.
Don’t keep it in a box. Just come through the front door normally.
We’ll serve tea here.
“With holdings of how many shares can I have a refill?”
The number of shares doesn’t matter. You can drink what’s left in the teapot.
But that was how much I wanted a reply.
When you hear “Stock is something you do alone,” you might think, “Oh, is that what it is?”
Deciding trades alone. And more than that.
Even though you have something you love, there is no one to talk about it with.
Passbooks can be added to endlessly, but conversation partners did not come from addition.
I’ve forgotten the day I reached 10,000,000 yen, but I remember this.
After making money with BRICS, I lost about 2,000,000 yen on Nintendo.
Here’s the continuation of the trailer.
After profiting from BRICS-based mutual funds, I lost about 2,000,000 yen in Nintendo stock.
If you compare it to a game, the hero on the screen is energetic, but I who am controlling it am collapsing.
Mario, please help me a little.
The princess is important, but there’s also someone in front of the TV.
Back then, I had grown fed up with it.
I sold all the individual stocks and took a long break from stock trading.
However, not all investment assets became zero.
There was one remaining developed-market stock mutual fund that showed unrealized losses.
I couldn’t sell it at a loss, and I held it for a long time.
The person had closed up shop, but the mutual fund still sat in the back of the store.
Even the closing music had ended.
I wasn’t leaving. I just couldn’t sell.\n
I could say I “stood my ground on long-term holdings,” but
I didn’t sell.
As for the person I was back then, I’d like to keep that part.
It wasn’t crisis management; it was a heartbreak holiday.
Even while resting, the market moved a lot.
During that time, I didn’t hold any individual stocks.
Then the Lehman Brothers collapse came.
But I didn’t predict a big drop and escape it.
I lost 2,000,000 yen and just got tired and drifted away.
Because there were many life events, I didn’t even open a securities account.
Yet, I didn’t escape the market impact entirely, as one mutual fund with unrealized losses remained.
Not having individual stocks turned out to be a good thing.
If I edited this as “I sensed the crisis and withdrew,” it might suddenly make me cross my arms.
Please don’t.
In the main story, I’m down 2,000,000 yen and discouraged.
But I was just lucky.
If you continue investing for a long time, sometimes later you’ll look back and think “that was the right move.”
But in reality,
whether it was the right decision or just luck, I don’t always know even for myself.
When you only list successful stories afterward, it’s easy to become a great investor.
In my case, I only lost 2,000,000 yen on Nintendo and took a break.
A great investor would probably rest more stylishly.
Investors rest. Salary continues as usual.
Even if you stop stock trading, work goes on.
Work, spend within reason, save.
Somehow, financial assets reached about 20,000,000 yen.
Stopping investing didn’t stop wealth creation.
A life where you work and save supported the earlier me.
More than the amount, it was my story.
When I tried to talk about 10,000,000 yen, work, BRICS, and Nintendo all came up.
Yet only the me on the day of achievement did not appear.
The lead role, you could say, was absent there.
I wanted to increase money.
Writing like this now might be a continuation of those stories from back then.
Now, Abenomics begins.
As Japan’s economy moves out of long deflation and the air changes, I too return to the world of stocks.
From here, the way money grows and my distance from stocks will change.
The sequel will feature the same lead actor.
“Could you replace me with someone smarter?”
Because this is a true story, I can’t replace that part.
Thank you for reading to the end.
I’m glad to be talking about stocks I couldn’t discuss in the past, even now.
If you’d like to read more, I’d be happy if you could like or follow.
※ The stock names and loss amounts are based on the author’s past experiences and are not investment recommendations