

[World Market & Forex Comprehensive Analysis] Nikkei 60,000 Recovered; Oil Plunges as U.S.-Iran Military Strikes Are Postponed — BOJ Signals Rate Hike in "Main Opinions" and Tonight at 21:30 "U.S. October CPI" Collide: The Full Picture of November 10th
The night of Tuesday, November 10, 2026, the world's forex and financial markets are approaching the release of the October U.S. Consumer Price Index (CPI) at 21:30 JST, the month’s biggest event, with a tense atmosphere as they enter pre-European/American trading hours.
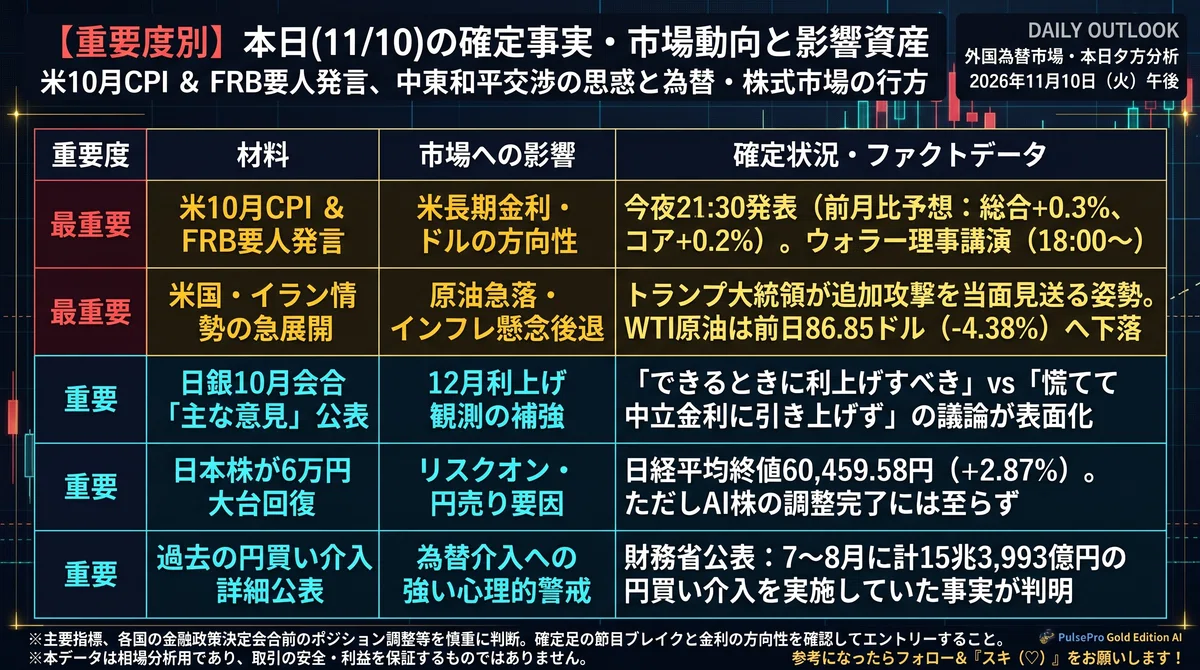
What is driving the current market moves is the decline in crude oil prices and the retreat of inflation concerns following the signal of “Trump's willingness to hold off on additional military action against Iran.” On the NY market the day before, risk appetite recovered, and in today’s Tokyo stock market the Nikkei Stock Average closed at 60,459.58 yen (+1,684.08, +2.87%), reclaiming the 60,000 level significantly.
However, in the FX market, the USD/JPY remains in a nervous range around the late 157s to early 158s without a clear direction. In the morning, the Bank of Japan’s “Main Opinions” confirmed a strong stance in favor of early rate hikes, while the previous day the Ministry of Finance published details of substantial past FX interventions (approximately 15.4 trillion yen from July to August), reinforcing a ceiling of intervention vigilance.The hardline view supporting early rate hikeswas noted, but the pace to reach the neutral rate remains a matter of debate, and the market faces a complex mix of expectations, with December’s meeting seen as potentially raising rates but with high hurdles for a series of rate hikes.
“Is the oil price drop driven by hopes for U.S.-Iran peace genuine, or are the tensions in the Strait of Hormuz still a ignition risk?”
“How will the Bank of Japan’s December rate hike expectations clash with tonight’s U.S. CPI and the FRB WoLler speech?”
Based on confirmed facts and official data as of 18:30 on November 10, this article details the full picture of today’s and tomorrow’s financial markets and practical trading strategies.
Chapter 1: The 5 Major Major Macroeconomic Materials Revealed Today
A summary of the core factors defining the current market environment.
Chapter 2: The Current State of the FX Market — 158-yen Battle and Intervention Vigilance
The key exchange rates confirmed in the Tokyo market on November 10.
【November 10 Tokyo Market Confirmation Rates (AM to PM)】
・USD/JPY (Dollar/Yen):
157.90–158.12 yen (previous NY close: 157.86–157.96)
・EUR/JPY (Euro/Yen):
177.20–177.42 yen
・EUR/USD (Euro/Dollar):
1.1216–1.1226 dollars
・Dollar Index (DXY):
around 101.66 (vs. prior day -0.63%)
In the previous NY market, the steep drop in oil fed inflation concerns and a shift in expectations led to a rally in risk assets. In today’s Tokyo market, supported by the resilience of U.S. long-term yields, USD/JPY again tested the 158 level.
Key Points in the FX Market
USD/JPY:A critical moment whether it stabilizes in the 158s and tests 158.50, or whether it pulls back to the 157s on the CPI release.
Cross-Yen:Oil’s fall improves Japan’s terms of trade (yen-buying factor), while global stock gains support risk appetite (yen-selling factor) — a direct tug-of-war.
Chapter 3: Japan’s Monetary Policy, BOJ “Main Opinions,” and the MOF’s Developments
Today in the Tokyo market, two official announcements that could shake the FX market’s backbone were published.
1. BOJ “Main Opinions” (October 29–30 meeting) Analysis
The main opinions published at 8:50 a.m. on November 10 revealed active deliberations among policymakers on additional rate hikes.
Hawkish view:“The next rate hike should be done when possible, without being overly cautious.”
Dovish view:“There is no need to hasten the move to neutral policy rate.”
The explicit inclusion of a stance in favor of early rate hikes is a yen-positive development, but concerns about the pace to reach the neutral rate remain strong, suggesting a mixed message for the market: while December’s meeting retains the possibility of a hike, the hurdle for consecutive hikes remains high.
2. The Pressure from Katayama’s Remarks and Past Intervention (15.4 trillion yen)
In the morning of the 10th, Finance Minister Satsuki Katayama stated that “the Bank of Japan should decide all policy tools, and ETF sale profits should not affect policy decisions,” emphasizing respect for central bank independence.
Additionally noteworthy is the MOF’s disclosure on the prior day the 9th of detailed FX intervention resultsfor July–August.
【MOF Disclosure: FX Intervention Balance Operation for July–August 2026】
・July 30: 7,976.5 billion yen (yen buying)
・July 31: 5,552.3 billion yen (coordinated intervention with the U.S.)
・August 3: 1,871.4 billion yen (yen buying)
------------------------------------------
★ Total intervention amount: 15,399.3 billion yen
This official data exerts a strong, silent pressure on the markets: if the USD/JPY moves into the late 158s toward 160, authorities can unleash a large-scale intervention of around 10 trillion yen at any time.
Chapter 4: Japan Government Bond Market — 30-Year Auction Results and Long-Term Yields
Today the MOF released the results of the 30-year government bond auction.【November 10 30-year JGB Auction Results】
・Coupon rate: 4.20%
・Average accepted yield: 3.847%
・Total bids: 1,512.6 billion yen
・Accepted amount: 450.7 billion yen
・Bid-to-cover ratio: about 3.36x
Although the bid-to-cover ratio of 3.36x indicates steady investor demand, ultra-long-term yields stay high. Japan’s long-term yield rises are usually driven by narrowing U.S.–Japan rate differentials and are seen as yen-strengthening. However, if fiscal expansion and more government bonds continue, there is a risk of simultaneous yen and bond selling, so it’s prudent not to judge the yen solely by the interest rate gap.
Chapter 5: Stock Market — Nikkei 60k Rebound and Residual AI Stock Risk
Global stock markets have rebounded sharply from last weekend’s panic selling.
【Major Indices’ Close and Change】
・Nikkei Average (Close on 10th):
60,459.58 yen (+1,684.08, +2.87%)
・Dow Jones (Close on 9th):
52,389.75 dollars (+2.15%)
・S&P 500 (Close on 9th):
7,549.94 (+2.35%)
・Nasdaq Composite (Close on 9th):
25,253.14 (+2.74%)
The Nikkei rose from a morning low of 59,268, with 161 gainers and 64 decliners, finishing higher across the board.
A Calm View of the Stock Market
In the short term, a rebound driven by inflation cooling due to crude oil drop was evident, but doubts about the ROI of massive spending by AI-related firms have not been fully resolved. With U.S. tech earnings and regulatory trends ahead this week, it would be premature to call an unconditional full-blown bullish market simply because the Nikkei has returned to the 60k level.
Chapter 6: Tonight’s Biggest Mountain — U.S. October CPI and FRB WoLler Chair’s Speech
Tonight in Japan time, a series of key events will determine the global market direction.
【Most Important Schedule Tonight through Tomorrow Morning (Japan Time)】
・18:00– ?? WoLler FRB member speech and Q&A ?????
・19:00 ?? October NFIB Small Business Optimism Index
・21:15 ?? ADP weekly employment numbers
・21:30 ?? October U.S. CPI ????? [MostImportant]
・22:35 ?? Fed Governor Lael Brainard? (Logan Dallas) remarks
・03:00 (tomorrow) ?? U.S. 10-year bond auction (42.0 billion)
・05:30 ?? Boeman (Bowan) Fed Vice Chairman speech
Market Consensus for October U.S. CPI
Headline CPI (MoM): Forecast +0.3%(Previous +0.6%)
Core CPI (MoM): Forecast +0.2%(Previous +0.3%)
With last week’s strong U.S. jobs data (NFP +165k) raising December rate hike odds to about 80%,if core CPI remains elevated, U.S. long-term yields could surge and the dollar could strengthen decisively.Conversely, a CPI miss would trigger a rapid fall in rates and a dollar weakness adjustment.
Chapter 7: The Truth About the Middle East Situation — Postponed Military Action and the Reality of the Hormuz Strait
Geopolitical factors have been weighing on crude prices, but the surface reporting and on-the-ground reality still show a considerable gap.
1. President Trump’s Postponement of Attacks
On November 9, after meeting Qatar’s prime minister, President Trump said he intended to postpone a large-scale new attack on Iran for the time being. This reduced the panic over a complete war causing a halt in oil supplies, and WTI crude futures fell sharply to 86.85 dollars per barrel (-4.38%).
2. Residual Maritime Blockade and Tanker Fires
But this does not mean “the end of the war.”
U.S. continues maritime blockade of Iranian ports.
Iran demands sanctions and blockade relief; the U.S. refuses.
According to Iranian state media, several attacks on tankers and incidents of navigation impairment have been reported recently, and tanker fires have occurred in the Gulf of Oman.
Drone and missile attacks by Yemen’s Houthi movement toward Saudi Arabia are sporadic.
Markets shifted momentarily from expecting an immediate expansion of military conflict to awaiting diplomatic negotiations, but until the blockade is解除, the risk of a rapid oil rally due to sudden military frictions remains.
Chapter 8: Commodity and U.S. Treasuries Movements
【Previous Day’s NY Market and Current Confirmed Levels】
・WTI crude futures: 86.85 dollars (-4.38% from previous)
・Gold futures: 4,114.50 dollars (rising on dollar weakness and oil weakness)
・U.S. 10-year yield: 4.886%
・U.S. 2-year yield: 4.564%
・U.S. 30-year yield: 5.279%
There are reports that the U.S. budget deficit for fiscal year 2026 is 6.2% of GDP and public debt is 100% of GDP, making the supply-demand balance and yield movements in tonight’s U.S. 10-year auction (42.0 billion) a crucial factor for USD/JPY.
Chapter 9: Structure and Practical Levels of FX Markets and Major Currency Pairs
Decisions around tonight’s U.S. CPI release for major currency pairs.
【USD/JPY Technical Monitoring Levels】
★ 159.00 yen: psychological absolute ceiling and maximum intervention alert zone ↑
★ 158.50–158.60 yen: recent rebound high and strong resistance ↑
★ 158.00–158.12 yen: today’s Tokyo high and psychological battle line
――――――
Current price: 157.90–158.05 yen
――――――
★ 157.50 yen: near-term support ↓
★ 157.00–157.26 yen: daily chart pullback support band, near last week’s lows ↓
★ 156.50 yen: clear trend reversal alert line
Key Trade Views for Major Currency Pairs
USD/JPY:A tug-of-war between the upside driven by rate differentials and the BOJ’s rate-hike expectations and intervention vigilance. Pursuing a long in the 158 zone ahead of CPI is extremely risky.
EUR/USD (around the low 1.12s):Oil-driven inflation cooling expectations in Europe and awaiting U.S. CPI. If CPI undershoots, a rebound beyond 1.1250 could occur.
AUD/JPY:As Japanese stocks rebound to 60k, risk-on buying supports, but recovery depends on China’s economic pace and the risk of renewed Middle East tensions.
CAD/JPY:Sharp crude price drops to the 86-dollar area pose direct headwinds for the Canadian dollar, keeping upside limited among cross-Yen pairs.
Chapter 10: Tonight’s Market Scenario Analysis (Three Major Branches)
Three scenarios based on the U.S. October CPI result and the reaction of U.S. interest rates.
? Scenario A [CPI unexpectedly high & Fed hawkish ➔ Dollar rises; 158.50 yen test]:
Conditions: Both headline and core CPI above expectations, U.S. long-term yields rising above 4.95%.
Trajectory: USD/JPY breaks 158.00 and tests 158.50; however, values above 158.50 face heavier resistance due to authorities’ rhetoric and potential actual intervention.
? Scenario B [CPI undershoots & U.S. rates fall sharply ➔ Dollar plunge; test of 157.00]:
Conditions: CPI misses on both headline and core, crude drop accelerates inflation concerns receding rapidly.
Trajectory: USD/JPY breaks below 157.50 and plunges toward 157.00; BOJ rate hike expectations help accelerate yen buying.
? Scenario C [Stocks stay high & Dollar weak; Yen strong (mixed scenario)]:
Conditions: Middle East talks progress keeping stock markets buoyant while U.S. yields fall and oil weakens (improving Japan’s trade conditions) leading to simultaneous dollar softness and yen strength.
Trajectory: USD/JPY softens while cross-Yen pairs like AUD/JPY show resilience due to domestic and external disparities.
Overall Conclusion: Tonight’s Practical Trading Outlook
The biggest lesson for today’s market is to discard the simplistic notion that “rising stocks automatically mean a weaker yen (higher USD/JPY).”“Rising stock prices do not guarantee yen weakness.”
Crude oil declines can be a powerful trigger for yen strength and dollar weakness:
Do not chase the initial spike right after CPI release:
At 21:30, algorithms often whip the market up and down with stop-hunting. It’s not too late to wait for the U.S. 10-year yield and the dollar index’s confirming moves before entering.
Always keep past intervention amounts in mind (15.4 trillion yen):
If USD/JPY surges into the late 158s, expect the risk premium of sudden rate checks or real intervention to be in play at any time.
As important indicators approach, manage positions prudently and trade with discipline based on confirmed facts and objective price action.
If you found this helpful at all, please follow and press the “Like” (♡) at the bottom of the screen to encourage future updates!
TrendPulse Pro Free Trial:https://www.gogojungle.co.jp/tools/indicators/86532?via=users
TrendPulse Pro AI Free Trial:https://www.gogojungle.co.jp/tools/indicators/86529?via=users
QuickScalp AI Free Trial:https://www.gogojungle.co.jp/tools/indicators/86523?via=users
An indicator that removes emotion and captures the market with clear evidence and rules.
Details of functions and design logic are published on each product page
? [GogoJungle Product Page]