

[80,000,000 ticks truth] Why does the beloved "Fixing Value and Gotō Day EA" fail on real accounts? — Quants reveal the "true distortion on days 5 and 10" (measured PF 14.39 / full picture of win rate 81.07%)
Previous article
We received numerous responses such as “I was fooled by the illusion of fixed spreads” and “I finally understood why real costs left nothing behind.”
Therefore, this time,loved by Japanese FX traders the most,the most widely created EA classic anomaly—“Goto-ichi (fixing the value of the middle rate) Trade” truth,will be laid bare under cold quantitative analysis and vast real data.
1. Why can’t commercially available “Nakaochi/Gotō day EAs” win in real trading?
“On the 5th, 10th, 15th, 20th, 25th, 30th (the fiftieth day), there is real demand for USD purchases for corporate settlements. So if you buy USD/JPY in the morning and settle by the 9:55 fix, you’ll win.”
This is a very famous anomaly that anyone who started FX has heard. In fact, GogoJungle also has many “Nakaochi EA” and “Gotō-day EA” listed for sale.
However, many people who purchased those EAs and ran them on real accounts tweet after a few months like this.
“Backtests were cleanly rising, but in real life I can’t win at all…”
Why does one lose in the Gotō day anomaly, which should be logically correct? The three reasons uncovered by quantitative analysis are as follows.
Because everyone buys at the same time (around 9:30), you get killed by slippage
Orders concentrate at textbook times, so broker slippage becomes severe, and you are forced into prices far less favorable than interbank rates.
Caught in the early-morning spread widening
EA that builds positions from the night before or after midnight get hunted by explosion of spreads around 00:00–01:00.
The false accounting trick of “90% win rate (SL 50 pips / TP 5 pips)”
Because a huge stop loss is included to improve tester visuals,there are occasional “sharp drops before the fix” every few months,and your account balance is wiped out in one blow.
2. Quant conclusions: The Gotō-day distortion does not exist in a single time window
We conducted a comprehensive search across all market spaces on MetaTrader 5 (MT5) for USDJPY,using the entire market space (24 hours × all entry times × holding times × trade directions) in a brute-force manner, and audited with the real tick data from T〇〇〇 FX (about 80 million ticks).What we found was astonishing.
The truth uncovered:
“The Gotō-day edge is not just a single 9:55 fix, but is dispersed across multiple different times during the day.”
In other words, you fail because you bet with a single fixed time on a very large lot; the correct institutional-investor approach is to “disperse across multiple statistically validated slots and execute with multiple parallel orders.”
3. Conclusive evidence: 80 million realistic ticks prove the shock of PF 14.39
A tale told by numbers alone would suffice. Below are backtest results for a 10-strong portfolio with the Gotō-day filter activated, in the state of “TP=0.0 / SL=0.0 (completely time-based market closing)” with no exit take profits or stop-loss distortions.
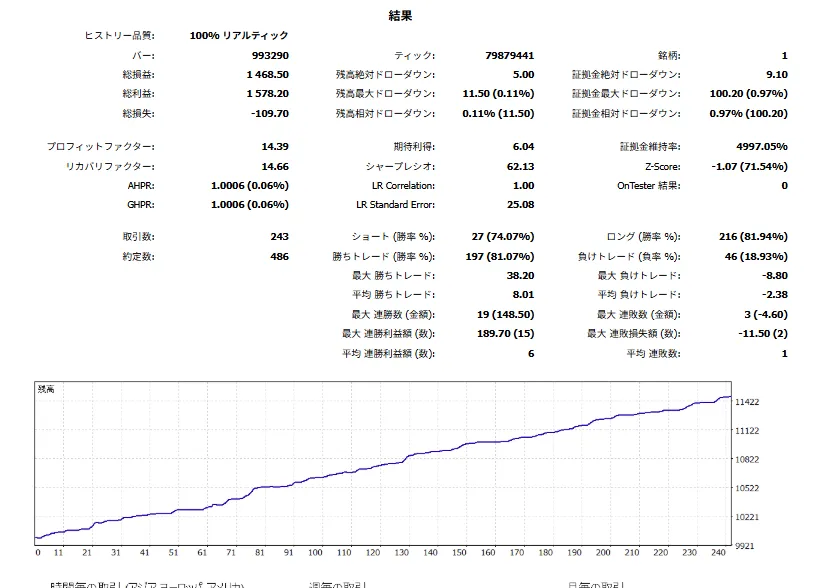
【Testing conditions and real tick data (T〇〇〇 FX USDJPY / M1)】
Testing period:2024-01-01 to 2026-09-01 (about 2 years 8 months)
History quality:100% Realtick (ticks: 79,879,441 / bars: 993,290)
Profit Factor (PF):14.39(Total profit 1,578.20 / Total loss -109.70)
Recovery Factor (RF):14.66
Sharpe Ratio:62.13(Extremely stable at statistical anomaly level)
Total trades:243 trades (Long 216 / Short 27)
Total win rate:81.07%(Long win rate 81.94% / Short win rate 74.07%)
Average win/loss ratio (Risk-Reward):Average win +8.01 / Average loss -2.38(3.36 : 1 overwhelming win-small loss!)
Maximum drawdown:Balance max DD 0.11% (only 11.5 USD) / Margin max DD 0.97%
Longest winning streak:Up to 19 consecutive wins(Maximum losing streak only 3 times and stopped immediately)
LR Correlation:1.00(a perfectly straight line with a rising tendency like drawn with a ruler)
This is not the typical “high win rate but a big loss when it loses” seen in commercial EAs. On average, you win 8.01 pips and if you lose you only lose 2.38 pips (risk-reward 3.36:1), maintaining an ideal “small losses, big gains.”Result: win rate over 81% and PF over 14,
4. Truly genuine anomalies do not require forced fiddling (curve-fitting)
Why can such numbers be achieved with no TP or SL configured, in an “undiluted” state?
Because the distortion captured is the genuine structure of the Gotō-day market itself.
There is no need to twist parameters or force-fit past data (curve-fitting). Like the laws of natural science, as long as you capture the market’s distortion with proper observation tools, the market will return a beautifully geometric straight line.
The Gotō-day multi-execution engine used in this validation was officially released yesterday asInpDateFilterMode = 1) built-in by default.
Dispel the fantasy of fixed, sweet spreads,and experience the true world of quantitative trading.
▼ The multi-portfolio system that produced this demonstration data is here