
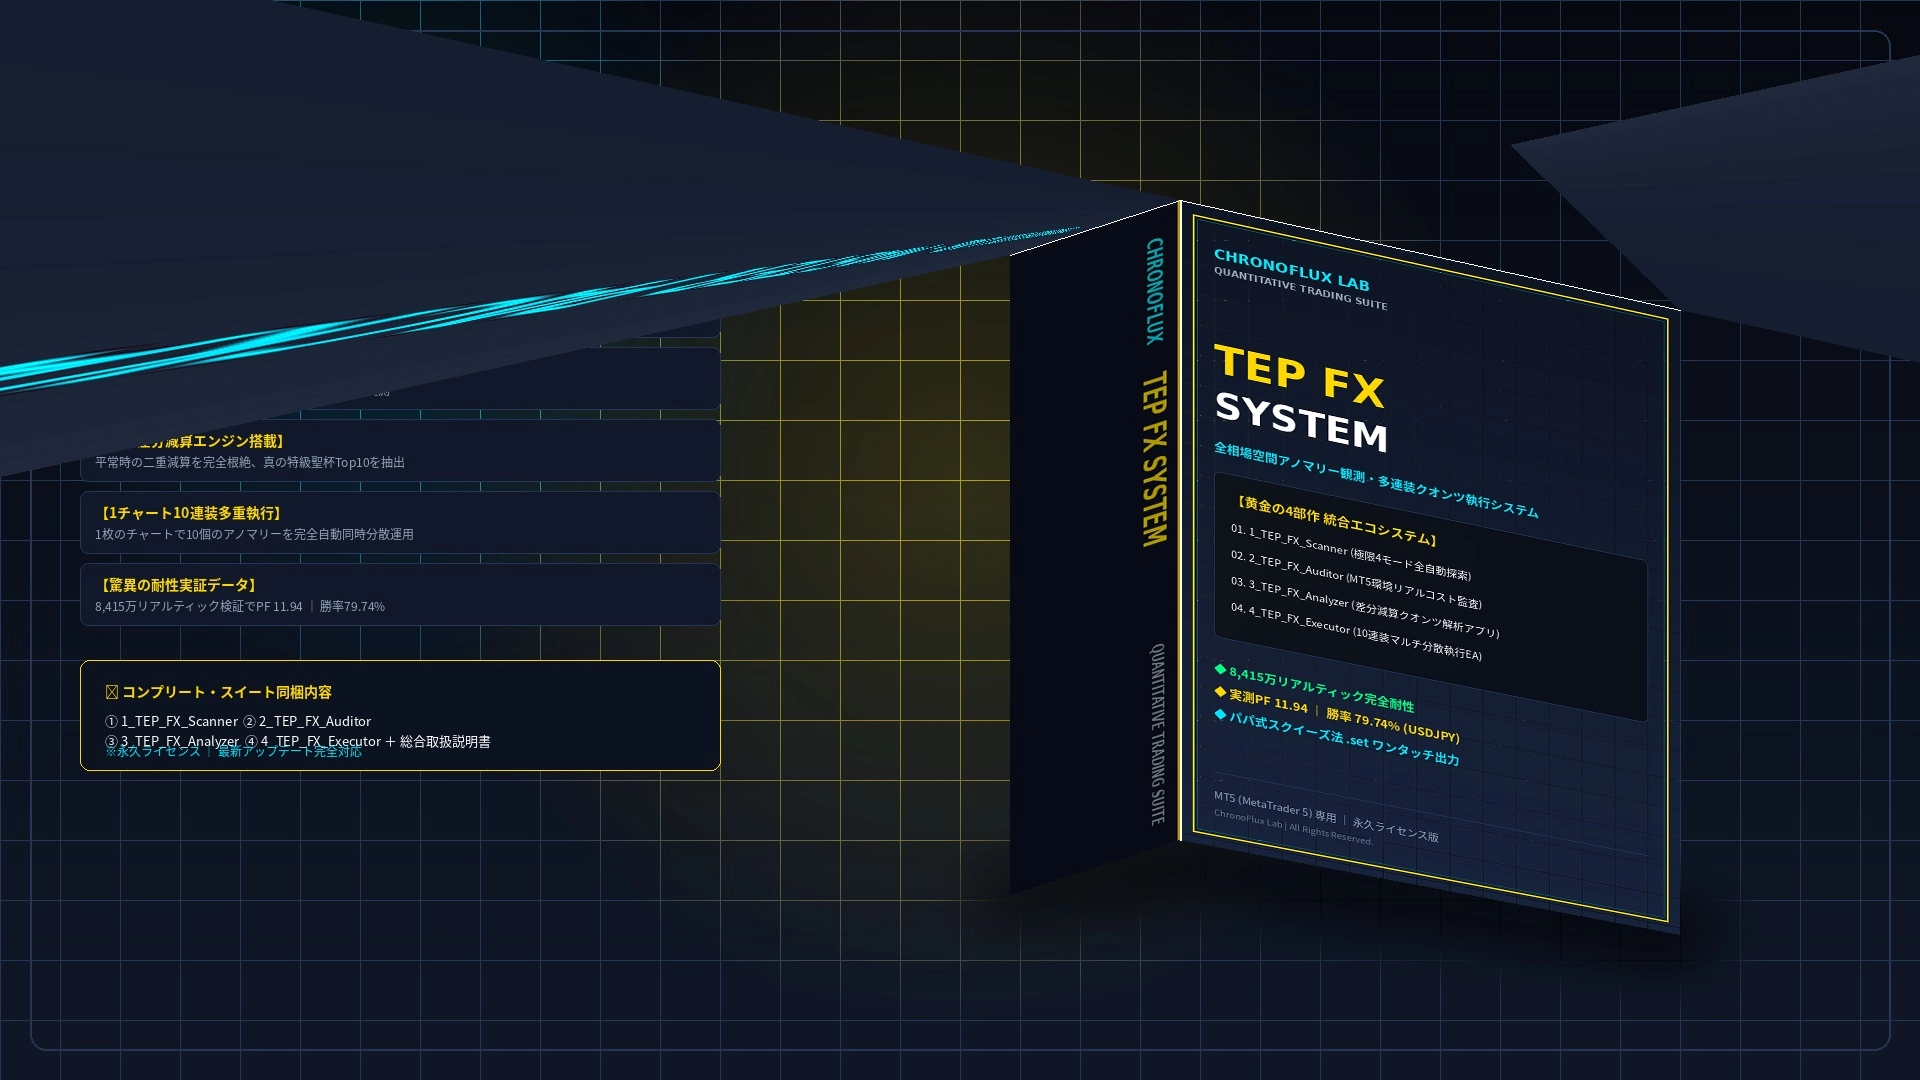
Why do EAs that show a consistently rising equity curve in backtests die in the real market? — The quantitative trader's rule that exposes testers' sweet delusions
"Backtesting showed PF exceeding 3.0 with a clean upward trend, but..."; "As soon as I started running it on a real account, funds were gradually depleted..."
Have you ever felt this frustrating too?
The reason 99% of off-the-shelf EAs fail in real markets is not because you had bad luck or because market conditions suddenly changed.
There is only one cause. It is because you tested with MT5 Tester’s "too-sweet imaginary environment".
Three big traps of the tester laid bare
The sweet illusion of "fixed spread"
When the tester calculates with a fixed 1.5 pips spread, during the real market’s late night/early morning hours (around 05:00–07:00 Japan time), spreads explosively widen to 5 pips to 20 pips or more. The tester does not calculate even one yen of losses from this overnight spike in live trading.
Ignoring huge negative swaps
Holding positions across days incurs heavy negative swaps, starting with triple swaps on Wednesdays, which erode the account daily.
The drag of external ECN fees
Fees of around 6–7 dollars per round trip per lot reliably eat into profits as the number of trades increases.
"Even if the tester looks like you win every day, when you subtract 100% of the real account’s measured costs, in reality you only had to shoot bullets twice a week." This is the cold hard truth that quantitative analysis reveals.
Quantitative approach based on institutional investor standards
To fundamentally solve this problem, we developed an integrated system that fully observes the temporal distortion (anomalies) in the market.
Instead of creating a fake holy grail by fitting TP/SL to past data like commercial EAs,
Directly and in milliseconds measure the full 24-hour spread expansion and swaps with undercover probes
Strictly subtract only the "diff-cost" between normal spreads and late-night/early-morning expansions
Extract only the top 10 that won’t collapse even when subjected to 84.15 million real-testing waves
The result is the following measured data:
Profit Factor (PF): 11.37
Win rate: 78.83% (274 trades, 216 wins, 58 losses)
Max drawdown: Margin DD 0.10% / Balance DD 0.01%
Recovery factor: 16.06
TP/SL: All achieved in the bare state of "0.0 (no adjustment)"
Survivability without using profit-taking or convenient stopouts, and mechanically closing at the designated time, demonstrates the tangible evidence of the market-structure distortions we are capturing.
A miracle that monetizes the FX "position waiting time" instantly
Moreover, digging deeper into quantitative analysis revealed another surprising fact.
In FX, even during times when spreads and fees are prohibitive, binary options (High/Low standard trading) with zero spreads can offer a huge golden window with win rates over 80%.
By leveraging the binary option characteristic where a payout is full (1.85–1.95x) as long as the price is just 0.1 pips above (or below) at the judgment moment,
During the day, monetize instantly with countdowns and voice alerts for BO
At night or during work, leave it to FX multiple-entry EAs to completely automate wealth accumulation
A ideal risk-diversified portfolio has been created.
Owning an unbreakable structure
Shall we end the quest for "winning signals" and "fake backtests" once and for all?
The complete reveal of the genuine quantitative trading system and the High/Low win-rate specialized analysis system is published on the product page below. Please check its overwhelming evidence during the introductory, limited-period special pricing.