[Financial AI / AI Agent Research] 18 settlements: Are there zero trades on Sundays? Distinguish weekly profit/loss from unconfirmed
Even knowing that the weekly 18 settlements exist, can we say that there were no new trades on Sunday? The answer is: we cannot. The final editing document as of 18:30 JST on October 25 carries over the scope of verification from 00:00 on October 19 to 18:30 on October 25, including 18 settlements and post-costs net profit and loss of −14,747 JPY. The absence of new primary sources for the same date and the absence of trades on the same date are distinct. The two-line morning SELL is kept as a separate signal record, and it does not add to the count without corresponding orders or settlements.
Update on the evening of October 25:We reflected the DAILY_BRIEF.md with the 18:30 closing time in the same article published in the morning. The scope of the weekly aggregation is updated to the final document range of 10/19–10/25. The figures are verification values based on the statements obtained on 10/24, and are not the result of reobtaining VPS or original account records through editing this article. The morning local handoff is treated as a historical observation. We have not placed new orders, resent orders, or changed EA/AutoTrading/OBS.
Conclusion: The 18 settlements ledger and the SELL two-line are not the same aggregation
This article is a weekly reflection on financial AI, AI agents, self-made indicators, and EA AI research and development. I compared the account-history documents with the logs stored on my device. The editing did not involve reobtaining the independent original statements from the brokerage, nor re-auditing orders by connecting to a VPS. I will separate what was confirmed within the document from what the editor personally verified in production.
The source of the aggregation is the 18:30 JST version of DAILY_BRIEF.md on the day. The final document defines the verification scope from 00:00 on 10/19 to 18:30 JST on 10/25, and since there is no new evidence on the same day, the confirmed value for 10/24 has not changed. The morning local source is LOCAL_CODEX_HANDOFF_2026-10-25_0610_JST, covering 06:10 on the 24th to 06:10 on the 25th JST. Since the account aggregation and the terminal logs are verifiable from different sources, I will not overwrite one with the update time of the other.
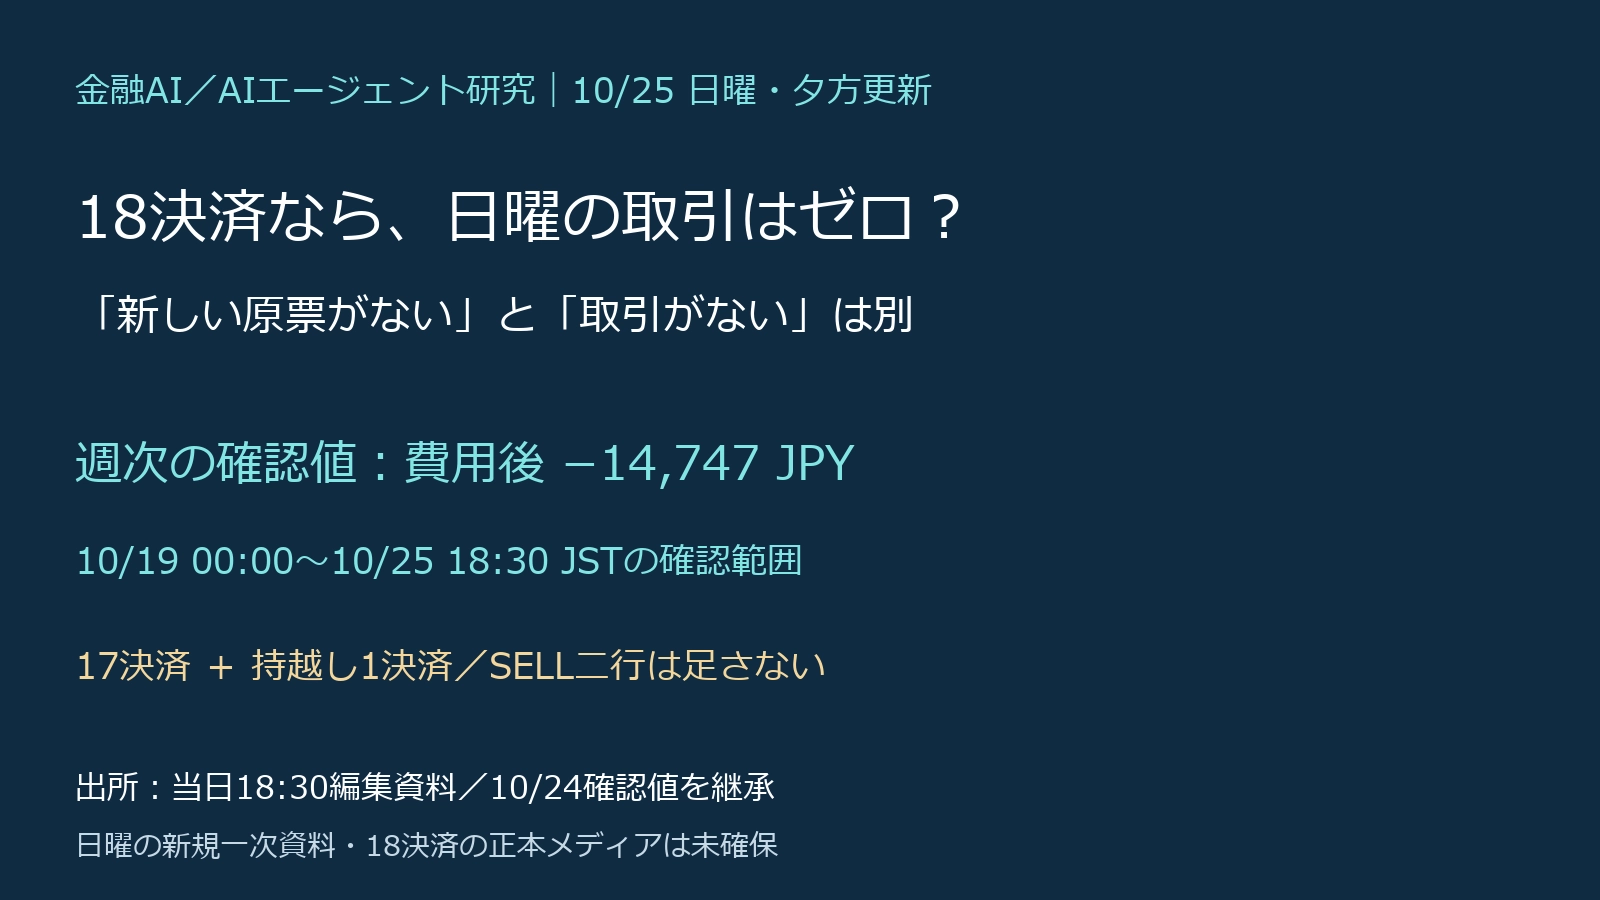
Verification range from 10/19 00:00 to 10/25 18:30 JST
18 settlements → net −14,747 JPY including costs
17 settlements −11,375 JPY plus carried-over 1 settlement −3,372 JPY
+ do not add
Morning SELL two-line: signal storage record / no confirmation of correspondence with orders and settlements
New raw data on Sunday: not found / not proof that there were zero trades on Sunday
Source: editing document as of 10/25 18:30 and morning 06:10 handoff. This is a schematic diagram that explains the differences between counts and evidence and is not a trading screen or a profit-and-loss graph. The original media for the 18 settlements has not been secured.
Basis: separating costs included figures and carry
The 18 settlements in the weekly document are 8 with profit including costs and 10 with loss including costs. gross (profit and loss before costs) −14,515 JPY, commission −255 JPY, swap +23 JPY, net −14,747 JPY. The unit here is specified as Japanese yen in the document. The arithmetic including signs is −14,515 − 255 + 23 = −14,747. Having profitable deals and a weekly total that is positive are separate facts.
Not all 18 deals are new entries this week. The document distinguishes 16 new this week and 17 settlements including partial settlements, netting to −11,375 JPY, and carryover settlements from the previous week totaling 29,976,736 netting to −3,372 JPY. If you count new trades, partial settlements, and carry-overs all in the same unit, there is a risk of double-counting both trades and profit/loss.
The carry-over −3,372 JPY can be read as part of this week's settlement totals. However, this handoff alone does not determine trade direction, lot size, entry and exit prices, signals, ACK/TICKET_SIGNAL responses, or the final settlement reasons. Even if numbers and outcomes are known, it does not automatically tell which decision caused the loss. It is important to fill in unconfirmed paths and not attribute a specific modification failure.
The final document treats 17 settlements as aligned with the VPS account statements and individual tickets confirmed on 10/24, and distinguishes carry-over 29,976,736 as settled on 10/19 after being opened on the prior week's Friday. Here, “confirmed” means confirmed in the report, not independently rechecked by the editor. The carry-over’s trade direction, quantity, entry/exit prices, signal_id, ACK/TICKET_SIGNAL, and settlement reason remain UNKNOWN. It does not mean that all decision paths for all 18 deals are complete.
Last three settlements and losses not reached by break-even price
As three settlements reflected in v1.41, the final document records ticket 30020837 as +1 JPY, 30022986 as +962 JPY, and 30027152 as −2,509 JPY. These results are already included in the weekly 18 settlements and do not represent adding three more to the 18 deals. We do not compute the overall win rate or profit/loss effect of the entire version from a few results.
30027152 shows SELL 0.02 lot, entry 3992.40, close 4000.35, initial SL 4000.52. The price figures are presented in GOLD price terms, not in Japanese Yen profit/loss. The maximum unrealized profit before costs was about 360.81 JPY, and it was recorded that it did not reach the entry price trigger of 1,250 JPY. The appearance of unrealized profit midway and the hitting of the entry price trigger are separate events. Do not directly convert price differences to yen; interpret execution differences or settings effects by separating the details and specifications.
Another point is not to add the previous day’s morning or midweek interim totals into this 18-settlement period. If the same trade appears in a later aggregation, adding it would double-count. When reading past articles, first check the target period and closing time, whether costs are pre- or post-cost, and whether you are looking at the entire account or a specific range. Do not interpret an increase in numbers as new trading activity; verify the trade number and the correspondence to the aggregation range.
How far the SELL log reveals the scope
In the morning local handoff, there are SELL records with bar=2026.10.23 23:50:00, price=3993.34, warn=0, and bar=2026.10.23 23:55:00, price=3993.99, warn=1. The price is the price shown in the log and not Japanese Yen profit/loss. The bar time and Japan time are not reconciled, so I will keep the original notation here and will not state that these were new trades on October 25.
warn=0 and warn=1 are information to read the decision value on that line. Zero does not mean filled, and one does not mean stopped out. Merely looking at two lines does not confirm whether they were two separate orders or updates in the same state. Only by connecting candidate identifiers, EA reception, approval responses, order numbers, and fill history can we consider the actual correspondence with trades.
There will be a difference if you subtract the two prices, but I will not convert that into profit or loss. The actual buy/sell direction, order quantity, executed price, contract terms, and costs are not all aligned here. Seeing a sell displayed first and then a higher price does not mean that the sell was settled at that price. As a rule, numbers that are convenient for explanations should have their units fixed in advance.
Limit: even if the total losses are known, the causes of all paths are not esclare
There are missing drives with the Drive originals recording, screenshots, and trade_meta corresponding to this week’s 18 settlements in the weekly documents. Since we have no recordings to confirm the source and transaction handling, we do not embed other transaction videos. The diagrams are not reproductions of actual charts; they explain the difference between aggregation and signals. The absence of recordings should not be taken as proof that no trades occurred, nor should it be taken as confirmation that current operations are normal. When there is no new material, we hand over the status as unconfirmed.
In the morning handoff, holdings and order/settlement P/L on the VPS were UNKNOWN. The 18:30 evening document also states that we could not confirm new same-day trade logs, results, ACK/TICKET_SIGNAL, or account statements in the Drive originals and the day’s working area. This is not proof of zero Sunday trades. The fact that past records disappeared does not mean current operations are normal. When new material is not available, we do not fill zeros and simply carry forward unconfirmed data.
Moreover, we do not conclude future win rates, expected profits, or the superiority of any particular version from the results of a small 18-settlement window. The purpose of announcing this week's loss is not to improve performance or to blame a single cause. It is to clarify what can be explained and what is missing in terms of entry, holding, exit, and costs, and to specify the order of next investigations.
Next verifications: address identical trades before counts
The next verification order is to fix the scope, and connect signals, approval responses, trade numbers, entry and exit, costs, and the original media within the same trade. In particular, carry-over 29976736 must not borrow an unknown path from another trade; the original record must be sought. Partial settlements should distinguish the original position from subsequent history, and not rephrase settlement counts as new entry counts. This reconciliation work is not yet completed.
In our research activities, we handle 24/7 weekday trade-drive broadcasting. However, announcements of broadcasts do not imply that recordings for the 18 settlements are secured or that Sunday morning production is confirmed. In continuing research and verification of self-made indicators and EA, we distinguish visible screens, saved logs, and account statements, and we do not append numbers without solid backing to the actual results.
Specifications and availability arePlease refer to the GogoJungle sales pagewhich shows a discontinued status in the latest inspection records, and does not indicate that purchase is possible. This document is a research record and does not guarantee trading recommendations or profit/loss avoidance. The Sunday conclusion is to use the after-cost profit/loss of the 18 settlements as the baseline, and to keep the morning two lines separate as pending verification.
Final reference: Google Drive’s original of DAILY_BRIEF.md edited on the day, with a deadline of 2026-10-25 18:30 JST. Amounts are in JPY (Japanese Yen) as stated in the document, and counts are per settlement. The alignment of natural trades with videos, entry/exit images, and trade_meta under the same ticket and signal_id is not yet completed. When a new daily primary record becomes available, I will re-check whether there are any same-day settlements and the scope of aggregation; until then, I will not heuristically increase or decrease weekly figures.