[Laboratory Development Logic Introduction] WeekOpen Portfolio — Design and empirical results of applying the same logic to 6 currencies for weekly Monday gap reversals
【Image: WeekOpen_banner.png】
Semura Lab. introduces the lab development logic, the fifth installment. This time, we handle the EA "WeekOpen Portfolio" that aims to capture the rebound after the weekend closure in 6 currencies.
To state the conclusion first. In a ten-and-a-half year backtest, all 6 currencies achieved PF1.5 or higher (1.50〜3.04) with the same parameters. On the other hand, about 74% of the profits concentrated after 2020, and there are a few instances where all 6 currencies hit stop losses in the same week. The following is organized according to anticipated questions.
Q. What is this EA aiming for?
Demand-supply accumulated during weekend non-trading is released immediately after the market opens. Then, the rebound is pursued weekly for each of the 6 currencies. The market direction is not predicted. The specifications are as follows.
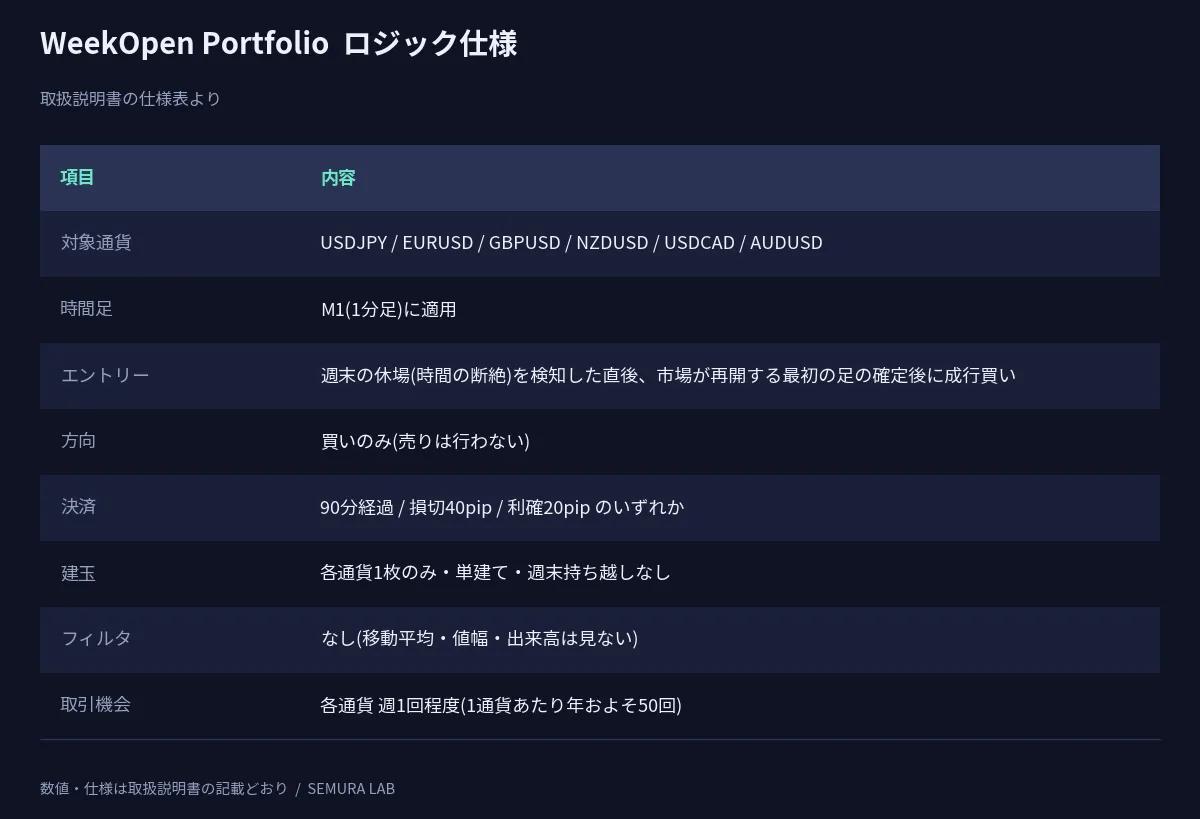 【Image: tbl6_spec.png】
Q. Why does behavior not change even if server times differ?
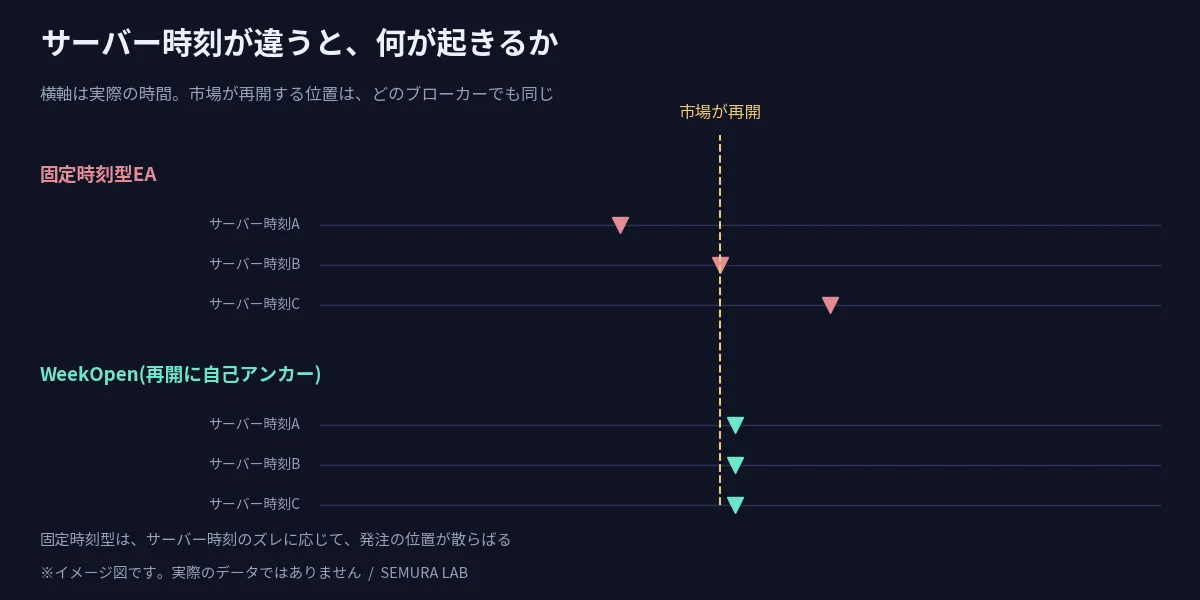
Because the entry criterion is based on the event of “market reopening” rather than a fixed time. Specifically, if there is a gap of more than 90 minutes from the previous bar and the current bar is a Sunday or Monday, it is judged as the first bar of that week. It does not place orders twice in the same week.
An EA with fixed times would place orders in different time zones if the broker server time differs from the testing environment. This EA is tied to the market reopening event, so this issue is structurally avoided.
 【Image: fig27_anchor_concept.png】
Q. What is the meaning of using the same parameters for 6 currencies?
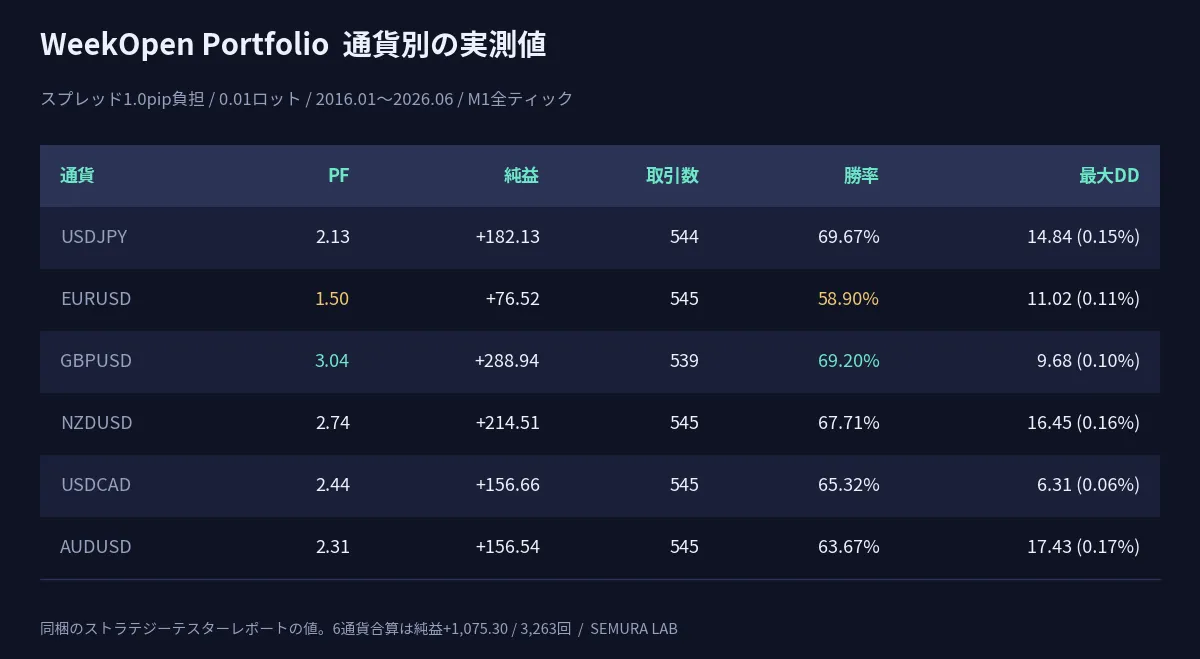
Because no per-currency individual optimization is performed, there is little room for overfitting. The fact that the same values produced results for all 6 currencies indicates that an edge exists across currencies. The verification used A〇iory’s demo account, M1, all ticks, from January 2016 to June 2026, with a 1.0 pip spread burden and a fixed 0.01 lot.
 【Image: tbl5_pair_results.png】
The highest PF among GBPUSD is 3.04, the lowest is EURUSD at 1.50. The win rate ranges from EURUSD's 58.90% to USDJPY's 69.67%; the maximum drawdown by currency ranges from USDCAD's 6.31 (0.06%) to AUDUSD's 17.43 (0.17%). This shows the asset curves by currency, displaying the two end currencies at the extremes.