
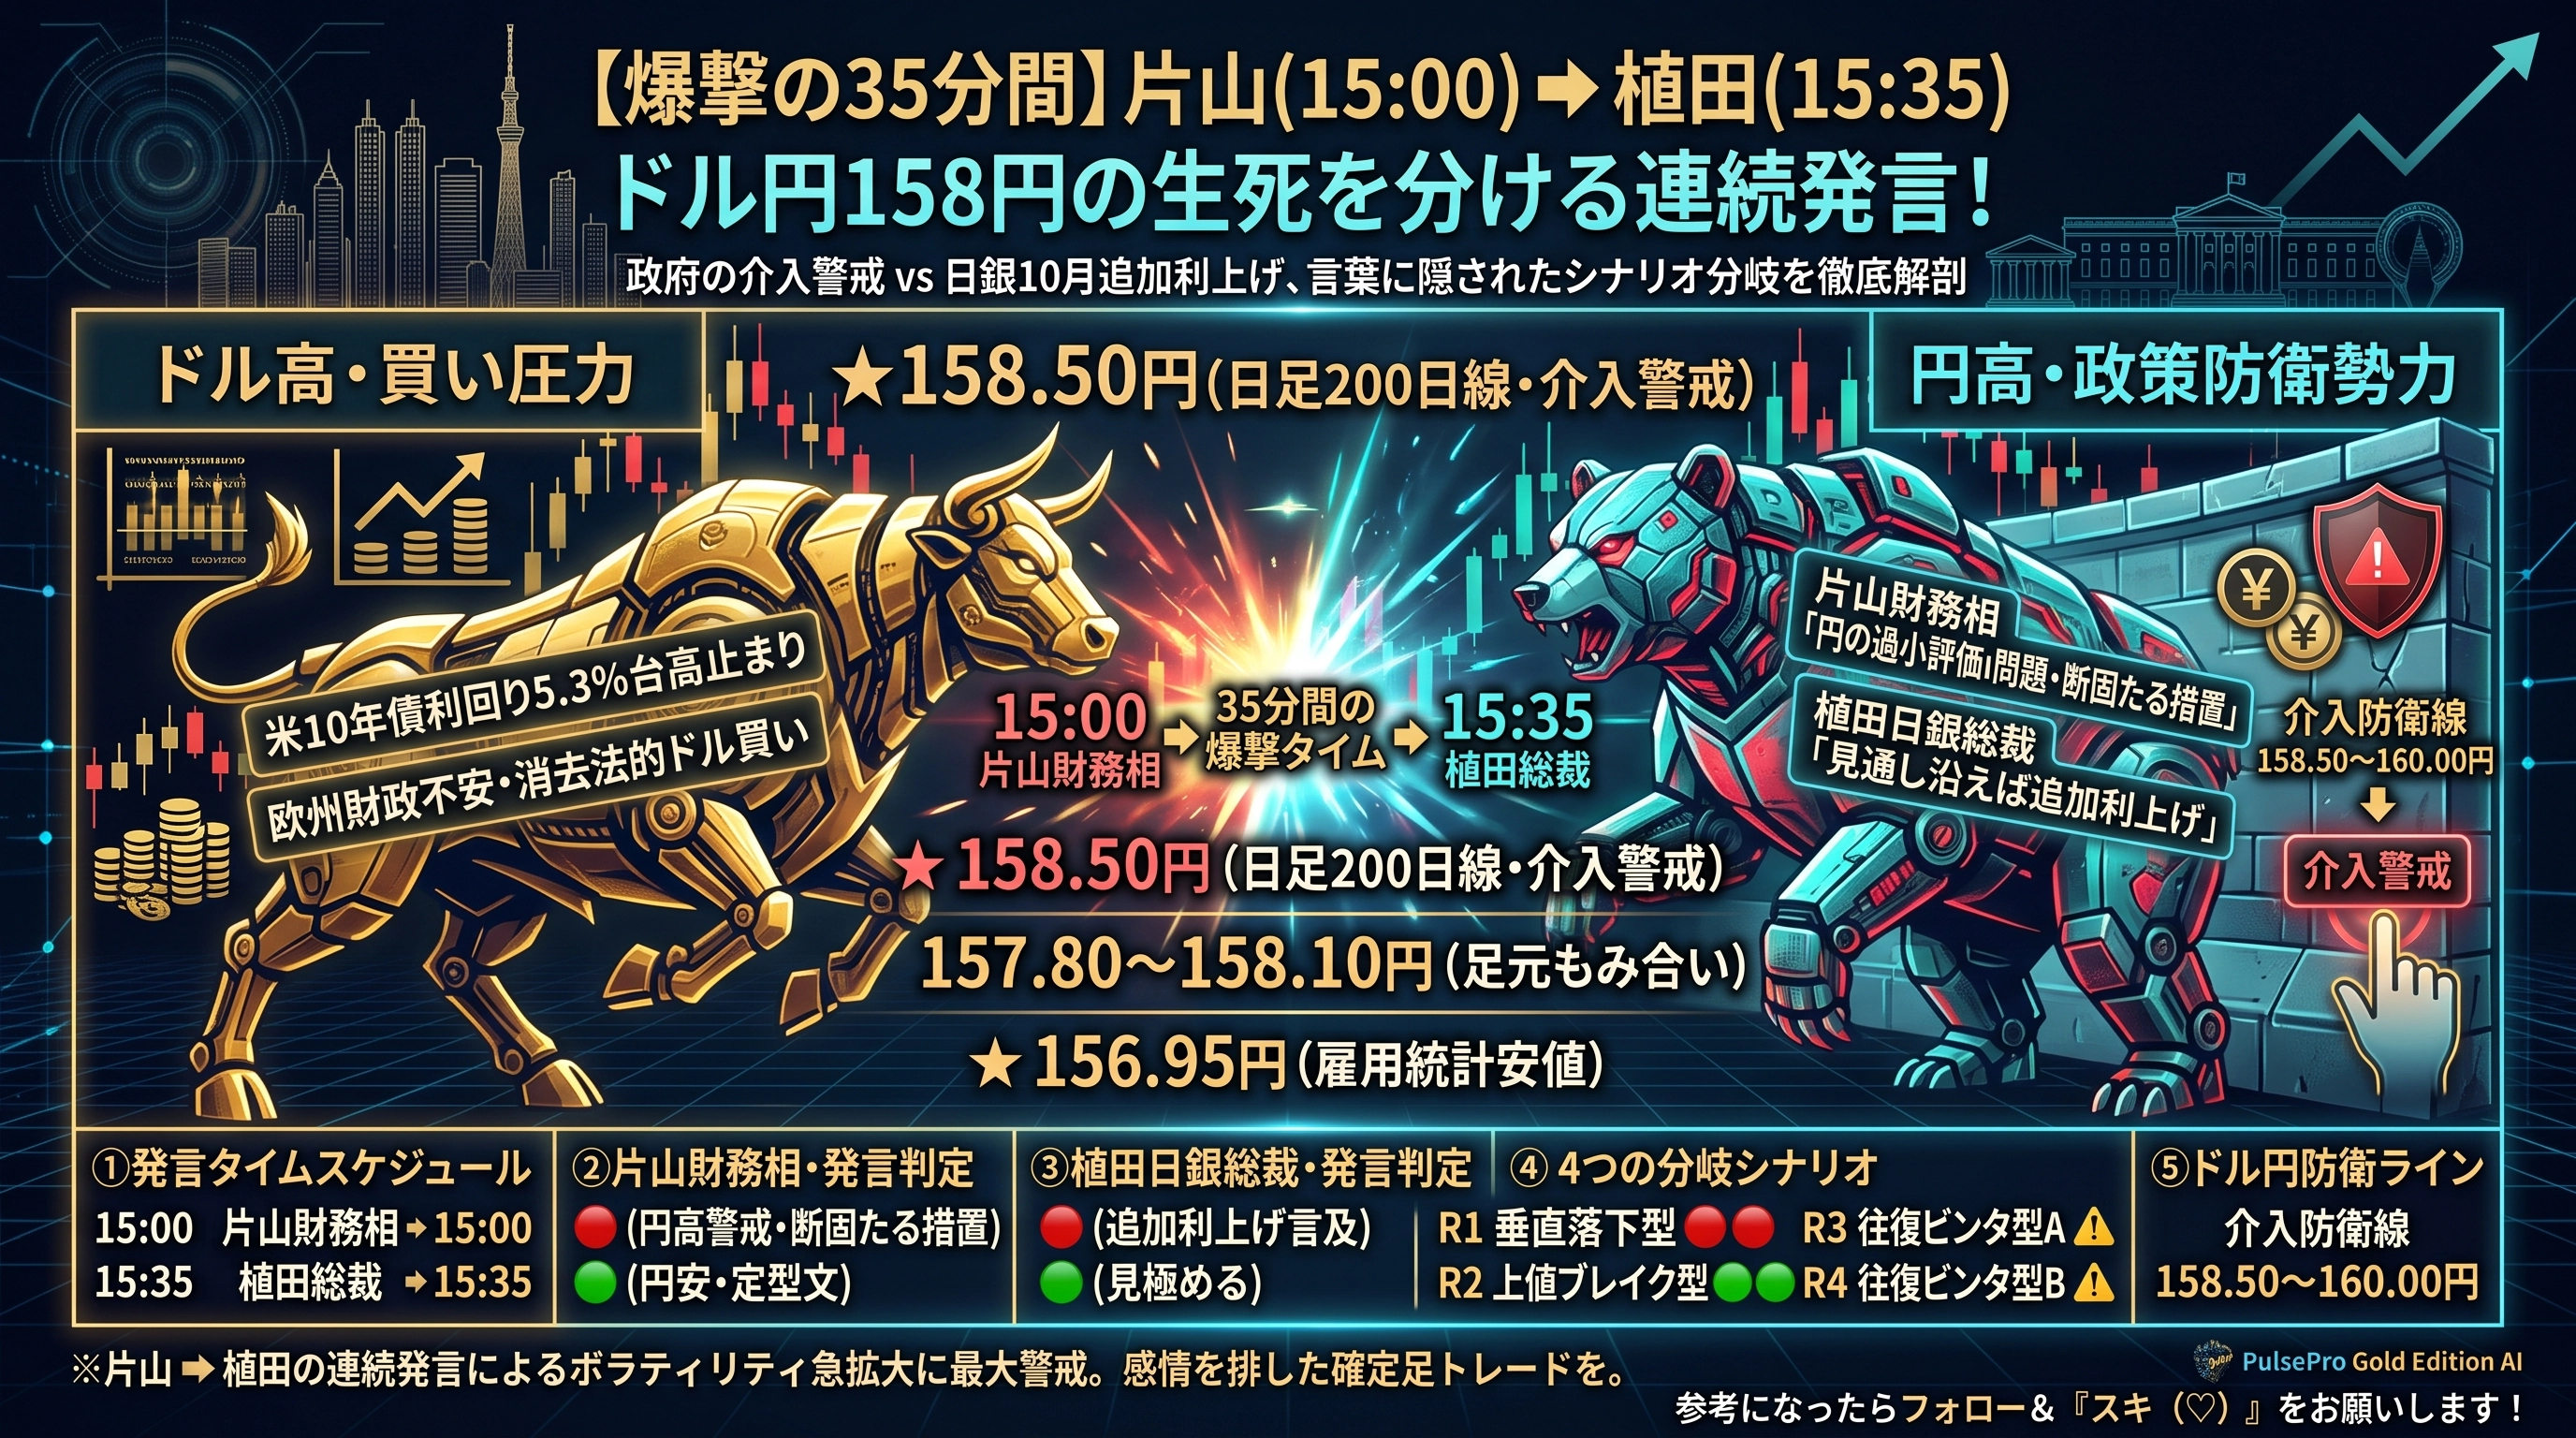
【158 Yen Defense of the King of the Hill】Finance Minister Katayama (15:00) × Bank of Japan Governor Ueda (15:35) consecutive appearances — the 5.3% U.S. interest rate barrier and the "FX intervention and rate hike signal" decision matrix
On Tuesday, October 6, 2026, in the afternoon, in the Tokyo foreign exchange market the USD/JPY hashovered in the narrowly confined 157-and-some to 158-and-some rangeand is proceeding with a very tight range as if holding its breath.
“Why is the USD/JPY able to stay around 158 even though U.S. employment data was weaker?”
“What will the market do around the speeches by the heads of the Bank of Japan and the Ministry of Finance this afternoon at around 3:00 PM?”
“Which keywords will trigger a yen appreciation, and which words will accelerate yen depreciation?”
In New York last night, U.S. 10-year Treasury yields rose to around 5.34% at one point, while expectations of intervention by Japanese authorities loomed over the upside.
With the 3:00 PM speeches by Finance Minister Katayama and BOJ Governor Ueda scheduled in quick succession today, we will thoroughly dissect the hidden intentions behind the spoken words and how the foreign exchange market reacts, from a practical perspective.
Chapter 1: The Current Power Balance — Why doesn’t the USD/JPY break away from “158 yen”?
First, we will organize the market environment before the 3:00 PM events.
【Current Major Market Indicators (as of 14:40 on 10/6)】
・USD/JPY: 157.80–158.10 yen (fluctuating around 158 yen)
・U.S. 10-year Treasury yields: 5.30–5.34% (maintaining historically high levels)
・U.S. 2-year yields: around 4.8%
・WTI Crude Oil Futures: in the $89–$90 range (pause due to G7 stockpile releases)
・EUR/USD: 1.116–1.119 (euro at multi-month lows due to France fiscal concerns)
・U.S. stock market (NASDAQ): continuing to rise, led by tech, up to 27,477
The main reason why the USD/JPY did not break down despite last Friday’s U.S. September employment data (NFP + 29,000) is“that U.S. 10-year yields remain stubbornly in the 5.3% range”and that “euro selling driven by France’s fiscal and political concerns is acting as an indirect dollar buying trigger”
Although U.S. Secretary Yellen (Bessent? likely Janet Yellen) stated that underlying inflation has fallen to about 2.3% and that mortgage rates would drop if Iran-related tensions ease, this has not been enough to reverse the current bond sell-off (higher yields) and dollar demand.
In other words, the fundamental environment remains favoring a stronger dollar and weaker yen, and the current picture is that the rally above is being dampened by Japanese government and BOJ verbal warnings and fear of actual intervention.