
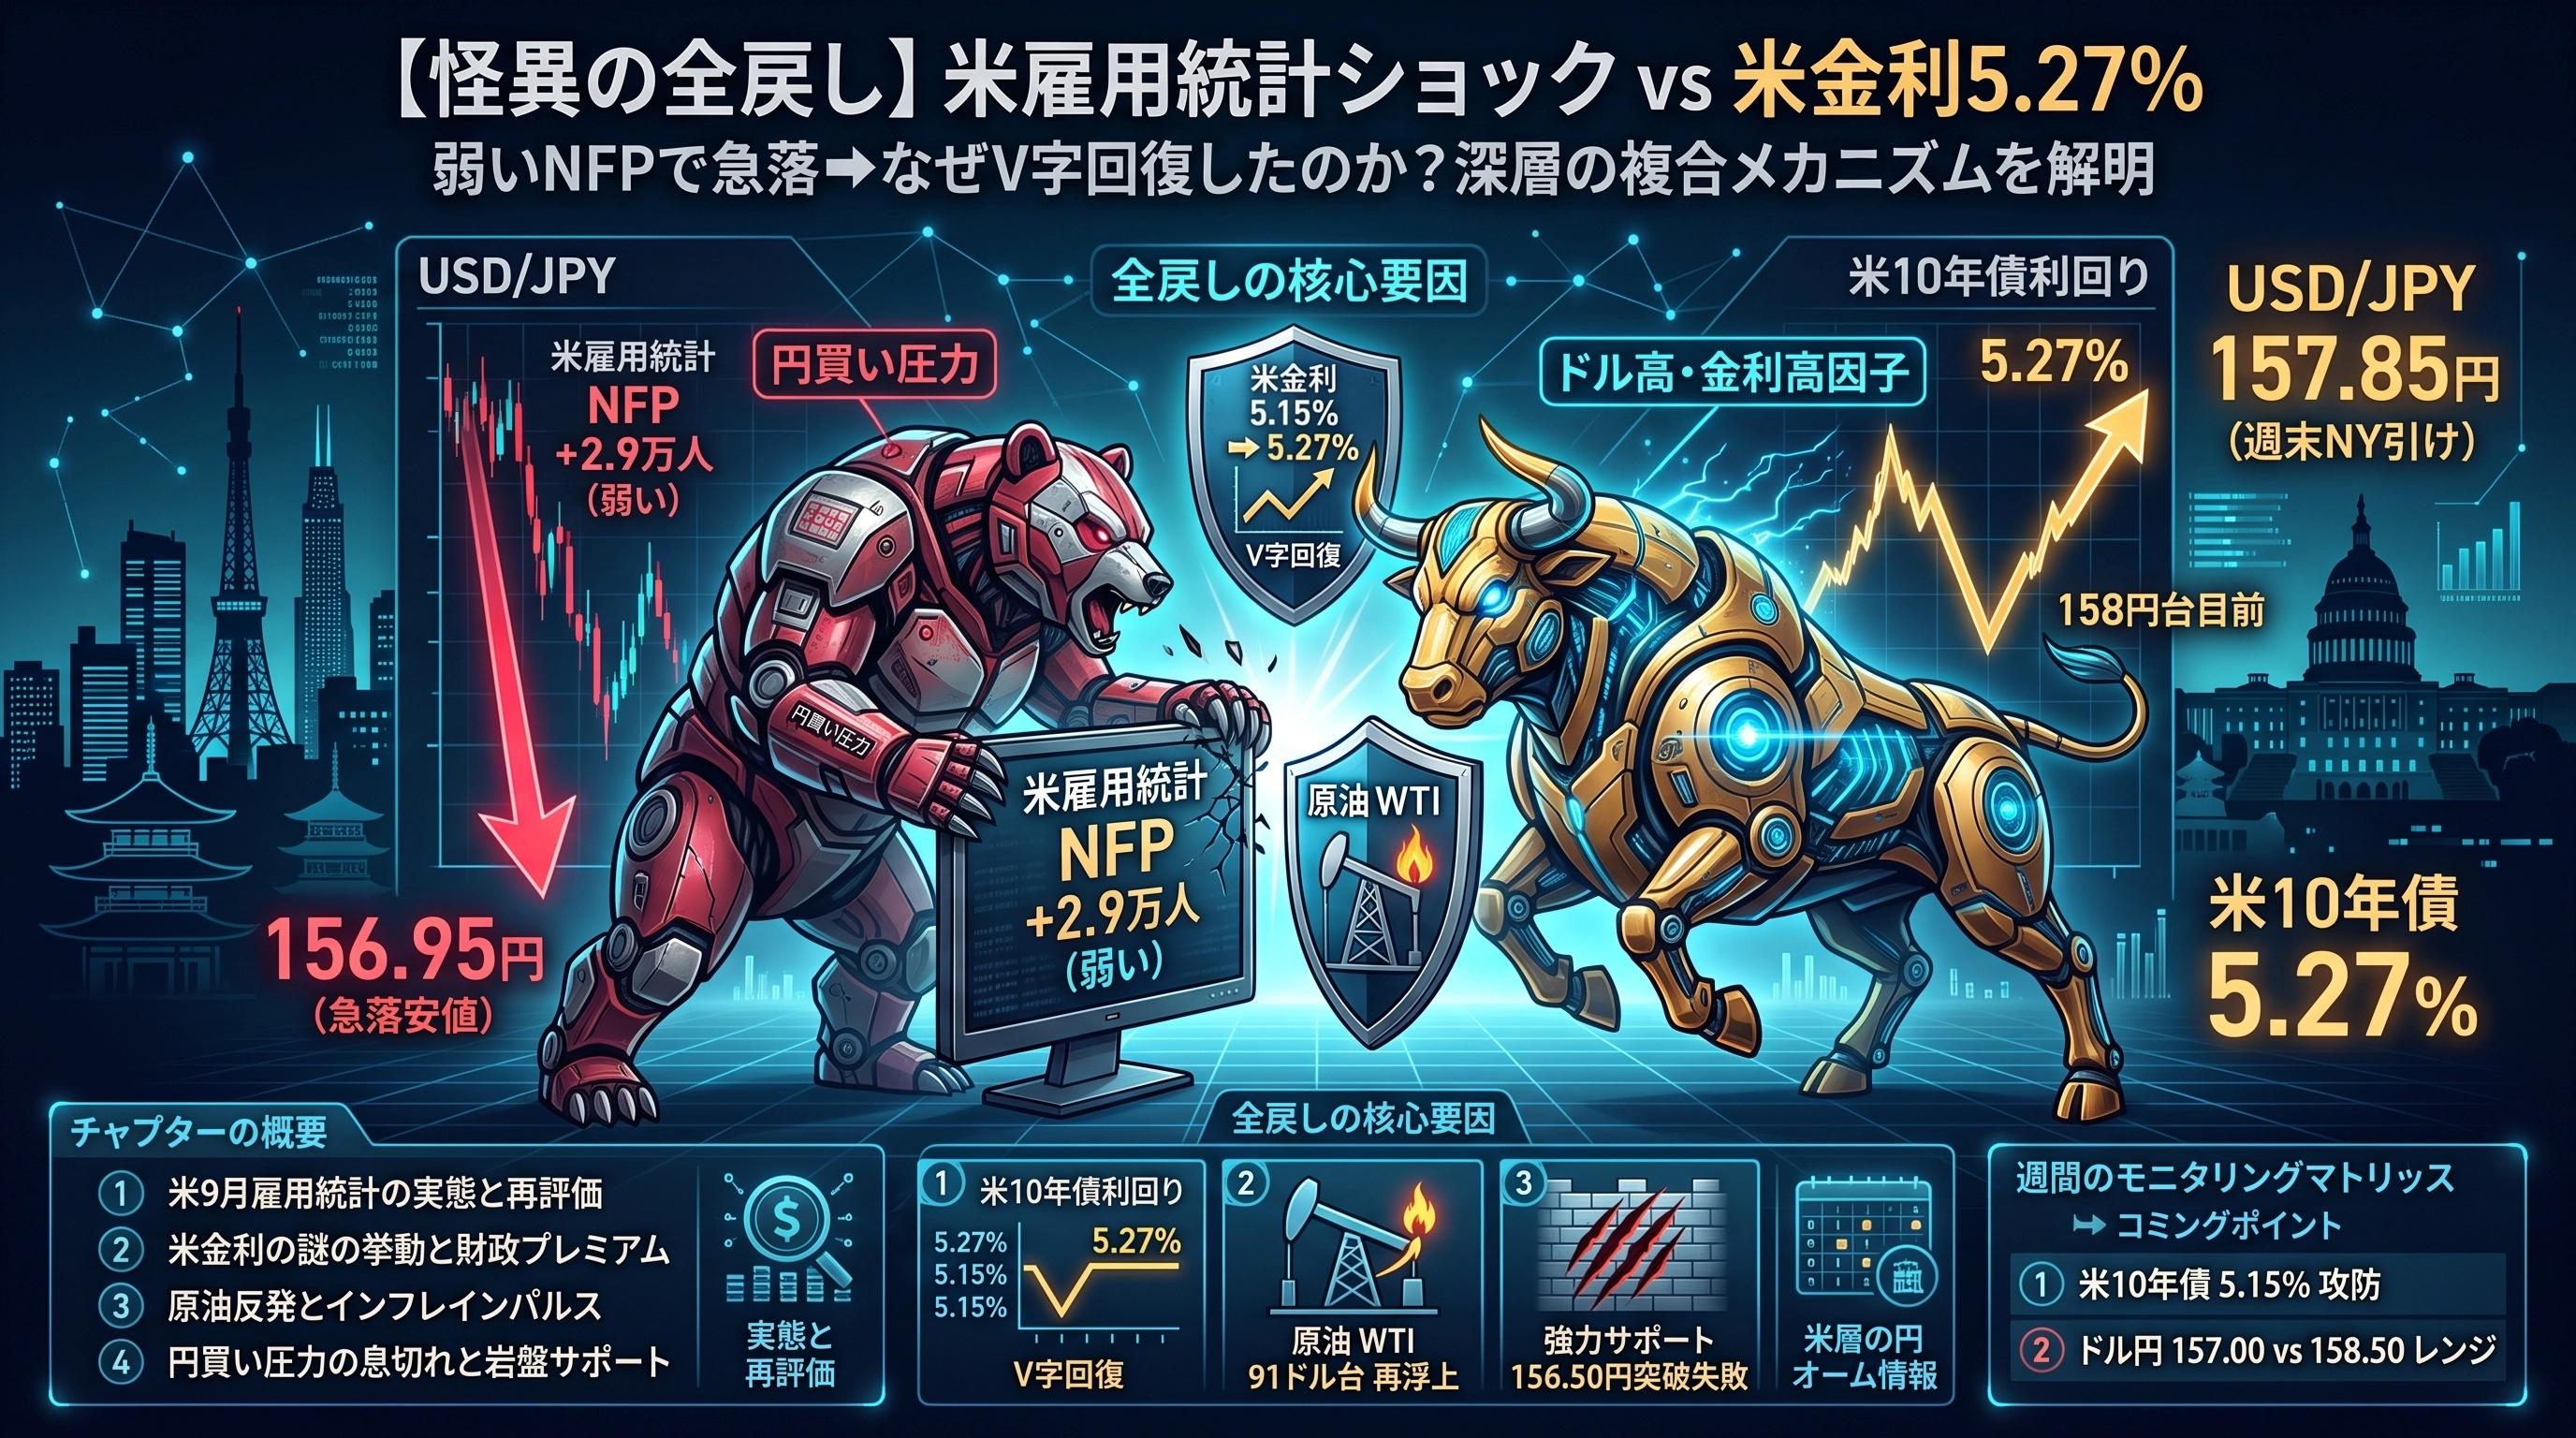
[Mystery's Full Reversal] USD Employment Statistics Shock Triggers 156.95 Yen Sharp Drop ➔ Why did it V- rebound toward 158 Yen? The Weekend Trap mastermind: "US long-term rate at 5.27%, oil rebound, yen buying fatigue" — the whole picture
On October 2, 2026 (Friday) in the NY market, the USD/JPY dollar-yen pair exhibited an extremely dramatic and perplexing volatile swing.
In the US September employment report released at 21:30 Japan time, the nonfarm payrolls (NFP) posted a shocking number of "+29,000" new jobs, well below market expectations. The dollar-yen pair moved from the 158.20 yen area just before the release toa vertical drop of more than 1 yen to around 156.95 yen in just a few minutes.
However, the real turmoil started from there.
Immediately after the plunge, aggressive buying came in, and around midnight,near 157.85 yen (weekend NY close) nearly fully retraced. It rallied back toward the 158 yen level at one point and closed the session.
“Why didn’t the currency pair continue to plunge despite such weak employment data?”
“If the dollar index (DXY) remained soft, why did the dollar-yen rise?”
“What was the true cause of the rapid rebound from 156.95 to 157.85?”
If you only chase surface-level news, you will never see the following layered mechanisms:a composite of “rebound in US long-term yields (5.15% ➔ 5.27%), “recovery in oil,” “fiscal premium,” and “end of yen-buying pressure”, which we will thoroughly uncover together with the chaotic timeline of the past week.
Chapter 1: Fact-checking the US September Employment Statistics
――The truth that “weak” is not the same as “collapse”
First, we整理 the objective data of the US employment statistics that served as the trigger for the sudden drop.
【The reality of the US September Employment Statistics (BLS release)】
・Nonfarm payrolls (NFP):
+29,000 (Market expectation +88,000 to +90,000 / Previous +162,000 → +133,000)
Downward revisions
・Revisions for the last two months (July–August):
Total of a large downward revision of −600,000
・Unemployment rate: 4.2% (Market expectation 4.1% /Previous 4.1%)
・Average hourly earnings (MoM):
+0.1% (Market expectation +0.3% / Previous +0.3%)
・Average hourly earnings (YoY):
+3.0% (Market expectation +3.1% / Previous +3.1%)
Placed in order, the numbers show a sharp drop in employment, rising unemployment, cooling wage growth, and downward revisions to past figures—a seemingly complete negative surprise.
The case for the Fed to raise rates at the October FOMC effectively evaporated, and the market priced in a rapid fall in the probability of a “October rate hike.” The immediate reaction after the release, pushing the dollar-yen down to 156.95, was a textbook-like initial response.
Why wasn’t it interpreted as an “US economy collapse”?
However, as institutional investors scrutinized the data, another facet came into focus.
The mechanism behind worsening unemployment:
The primary reason unemployment rose from 4.1% to 4.2% was not a large layoff by companies, but an increase in new entrants into the labor market (people starting job searches).
Low initial jobless claims:
The number of initial unemployment claims filed the previous day was 197,000, a very low level.
The persistence of “Low-Hire, Low-Fire”:
The current US labor market is not in collapse, but rather interpreted as a soft landing where firms are cautious about hiring while also keeping layoffs unusually restrained.
This calm reassessment became the first defense that prevented a one-way panic toward a dollar-wide selloff.
Chapter 2: The Core of the Full Retracement ①――Why the US 10-year Yield Rebounded
The V-shaped recovery from “5.15% ➔ 5.27%”
The most important and decisive driver of this wild fluctuation wasthe mysterious behavior of the US 10-year yield
.
【Timeline of the US rate moves】
21:30 (immediately after the jobs report):
With the complete disappearance of rate hike expectations, the US 10-year yield plunged from 5.24% to briefly 5.155%. The US 2-year yield also fell to the low 4.70% range. The dollar-yen subsequently dived to 156.95 yen as a result.
From 22:30 onward (NY market in full swing):
After the initial decline in yields, a worldwide bond sell-off (yields rising) resumed abruptly. The US 10-year yield rebounded from 5.155% to around 5.27% by the close, and the US 2-year yield recovered to around 4.81%. The narrowing of the US-Japan interest rate differential’s expectation collapsed entirely, pushing the USD/JPY up to 157.85 yen.
Why did long-term yields rise despite “weak employment”?
While short-term rates (2-year) reflect the Federal Reserve’s policy rate quite directly, long-term rates (10-year and 30-year) are determined by a combination of factors:
{US 10-year yield} = {monetary policy outlook} + {inflation expectations} + {fiscal and debt supply premium}
Right after the employment data, only the monetary policy outlook part fell. Subsequently, the following mega-risks re-emerged at the front of the bond market.
Rebound in oil prices:
Oil had previously fallen sharply due to factors such as the G7 strategic reserves release and the US’s diesel export ban being reconsidered. However, against the backdrop of Middle East geopolitical risk, prices held firm in the low $90s for WTI and near $100 for Brent, reminding the market that the fuel-inflation risk remains present.
Fears of US fiscal deficits and increased debt issuance:
Even as employment slowed, the pressure to issue a large amount of government debt did not disappear. The fiscal premium (term premium) in the yield curve pushed the long-term yields stubbornly up to 5.27%.
The fact that “the Fed is not in a rush to hike” and “US long-term yields would fall” are not equivalent in today’s market. This yield rebound blew away the ladder beneath the short-dollar-long-yen traders.