[Middle East Turbulence and Dollar-Yen Plunge] Shock from U.S.-Iran Ceasefire Plan Rejection and Reports of "Bombing After the November Midterm Elections" — The Hidden Mechanics Behind Reaching 156 Yen and Monday Morning Judgment Scenario
On Friday, September 25, 2026, in overseas markets, USD/JPY moved from around the high of 158.84 yen to a temporary
fall to a low of about 156.94 yen, finishing the week's trading at 157.29 yen。
Despite U.S. 10-year yields around 5.19% and 30-year yields in the high 5.4% range — a “historically high interest-rate level” — why did the market slam to the 156 yen area?
On the weekend of September 26, decisive reports from WSJ and Reuters stated that “the Trump administration rejects Iran’s seven-day ceasefire plan and expects to resume bombing after the November midterm elections.”
This could not be read through by superficial expectations of rate cuts or interest-rate differentials; an in-depth analysis of the Middle East situation, a two-stage risk, and the intervention watch by Japanese and U.S. authorities, as well as a practical roadmap to judge on Monday with oil, U.S. interest rates, and cross yen, are provided in detail.
Chapter 1: Weekend bombshell — Iran’s “seven-day ceasefire plan” and Trump’s rejection
Late last week, when crude prices (WTI and Brent) fell sharply, the main factor suppressing the upside in USD/JPY was
the prospect of progress in U.S.-Iran diplomatic talks and a resumption of traffic through the Strait of Hormuz.
However, the report by WSJ on the 26th, citing U.S. government officials, undermined the market’s optimistic scenario from the ground up.
[Key points of Iran’s “Seven-Day Ceasefire Plan”]
- Condition 1:解除の海上封鎖の解除 by the U.S. on major Iranian ports
- Condition 2:解除 of sanctions on Iran’s crude oil exports and解除 of frozen assets (about $12 billion)
- Condition 3: Seven days of cessation of fighting on all fronts including Lebanon
➔ In return: within seven days of the proposal, fully resume navigation through the Strait of Hormuz and return to nuclear talks
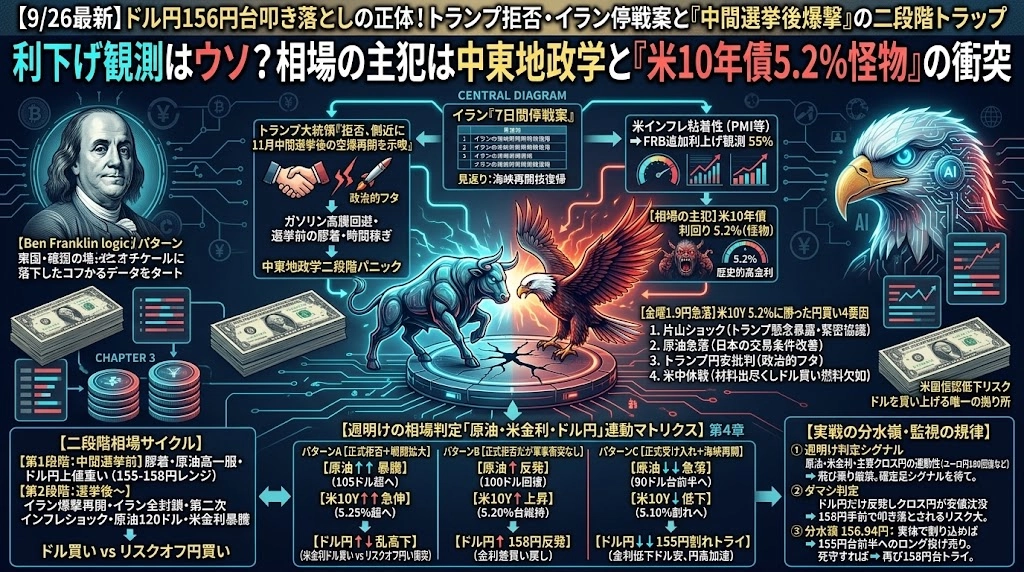
In response, President Trump reportedly told aides that “he plans to reject Iran’s seven-day proposal and resume bombing after the November midterm elections.”
(Note: Iran has indicated it is awaiting official U.S. reply, and Reuters notes that it has not independently verified the WSJ report as of now.)
Looking back at Trump’s latest remarks, a highly calculated political intention emerges.
September 9:Stated that “the war ends right after the November midterms.”
September 17: In an Axios interview, said he was faced with a major decision on whether to destroy the regime in Iran.
September 22: In a United Nations speech, warned that without an agreement Iran would be annihilated, while suggesting a possible agreement after the elections.
September 26:
WSJ: “Rejected Iran’s plan and hinted to aides that airstrikes would resume after the midterms.”
In other words, before the elections he wants to avoid aggressive military action that would push gasoline prices higher, while still holding the card that after the elections he would resume full-scale military actions.
Chapter 2: The truth of the September 25 “1.9 yen plunge” — there were four factors that defeated U.S. rate hikes and pushed the yen higher
The most cautionary fact in Friday’s market was that “even though U.S. 10-year yields hovered near 5.2%, USD/JPY was knocked down from around 158.8 to around 156.9.”
Under normal circumstances, higher U.S. rates would strongly support dollar buying, but four forces fully subdued the yield-driven momentum and caused the yen to strengthen against all currencies.
【The Four Major Factors Causing Friday’s Decline】
① Extremely fearful of U.S.-Japan coordinated intervention:
  Finance Minister Katuyama repeatedly stated that “President Trump is concerned about the yen’s weakness,” “working closely with Treasury Secretary Mnuchin,” and “will take firm measures against excessive speculative activity.”
  Coupled with the rate check on the 18th, this triggered heavy selling by major longs.

② Improved trade terms for Japan due to a drop in crude:
 Oil futures fell more than 2% after Iran’s proposal, easing the burden of import costs (persistent demand for selling yen in reality), so yen was bought against all currencies.

③ “Political lid” from Trump’s remarks:
 The President himself raised concerns about the yen’s weakness, leading hedgers to conclude that buying in the 158–159 range would be a target for both governments.

④ Diminished risk appetite after the U.S.-China summit’s “ceasefire extension”:
 Although U.S.-China trade ceasefire was extended to January 10, 2027, no fundamental solution was reached, so it did not become a fuel for a fresh risk-on dollar buying.
If U.S. rates rise while the currency falls, this is clear evidence of not a “dollar weakness” but a “strong yen fueled by policy and geopolitical risk pricing.”
Chapter 3: A two-stage market scenario born from time-buying until the midterm elections
Trump’s hope for a post-midterm bombing could create a two-stage cycle in the currency and energy markets.Two-stage market cycle may unfold.
【Projected two-stage trajectory】

[Stage 1: Sept–Oct (gridlock and time-buying before the midterms)]
- On the surface, diplomacy and tentative easing of tensions are pursued
- Oil prices retreat; U.S. inflation concerns ease somewhat
- U.S. long-term yields cool and USD/JPY loses upside momentum (range 155–158)

  ↓ through November midterms

[Stage 2: After the elections – (resumption of military action and geopolitical panic)]
- Realistic prospect of U.S. strikes on Iran ➔ Iran responds with full blockade of Red Sea and Hormuz
- Oil spikes toward $110–$120
- U.S. rates surge again to 5.3%–5.5%, triggering a clash between dollar buying and global risk-off yen buying
Even if there is a temporary drop in oil and U.S. rates due to reported progress in Hormuz reopening discussions, the warning remains that this is not lasting peace but time-buying before the elections, so further downside for oil could be limited.
Chapter 4: Monday market judgment — a cross-yen cross-asset linkage matrix of oil, U.S. rates, and USD/JPY
At the Monday open, when the market sees the official U.S. response (reject vs accept) in the headlines, the market will diverge into three scenarios.
| U.S. Response | Oil Price | U.S. 10-year Yield | USD/JPY Behavior | Expected Mechanism |
Pattern A 【Formal Rejection + War Expansion】 | ↑↑↑ Soaring (Beyond $105) | ↑↑ Sharp rise (Beyond 5.25%) | ↑↓ High volatility (156–158 yen) | Oil-driven U.S. rate hikes (dollar buying) clash with global risk-off yen buying. |
Pattern B 【Formal rejection but no military clash】 | ↑ Rebound (Oil back to $100) | ↑ Rise (Maintained around 5.20%) | ↑ Rebound toward 158 (Buying dips favored) | Typical “rate-differential advantage” buyback. However, strong intervention warnings work forcefully beyond the late-158 yen level. |
Pattern C 【Formal acceptance + Strait reopening】 | ↓↓ Sharp drop (Into the low $90s for oil) | ↓ Decline (Below 5.10%) | ↓↓ Break under 155 (Accelerated downtrend) | Oil-price deflationary inflation fears ease ➔ U.S. rates fall ➔ Japanese trade conditions improve, accelerating yen strength. |
Cross-yen check to identify a real move at Monday open
If, at Monday open, USD/JPY rebounds as in Pattern B, be sure to check whether cross-yen pairs (EUR/JPY, GBP/JPY, AUD/JPY) are also being bought at the same time.Correct rebound signals:
USD/JPY ↑ EUR/JPY ↑ GBP/JPY ↑ AUD/JPY ↑
➔ A sign that the “yen-buying pressure” from the Katayama shock and oil weakness has been fully absorbed.
False signal (counter-trend sell opportunity):
Only USD/JPY rebounds while cross-yen remains near lows.
➔ This would be just speculative dollar buying in a thin market, with a high risk of being knocked down near 158.
Summary: The watershed at Monday open is 156.94 yen
Currently, USD/JPY stands at the boundary of “a dominant dollar as U.S. yields at 5.2%” and the boundary of “Trump’s remarks, Katayama’s warnings, and oil movements forming a yen-weakening containment.”
The key point at Monday open is whether the low on Friday, 156.94 yen, is broken on the daily and intraday charts.
If this is clearly broken, the massive long positions built up around 158–159 yen will unwind in a chain, bringing a realistic prospect of a test toward the low 155s.
Conversely, if 157 yen is defended and a confirmed rebound in oil and U.S. rates occurs, the window to test 158 yen again—an intervention watch zone—will reopen.
Do not be swayed by fragmented headlines; calmly monitor the three interrelated factors — crude oil futures, U.S. 10-year yields, and major cross-yen pairs — and trade in a disciplined manner according to chart-confirm signals.
If this was at least somewhat helpful, please follow and press the heart at the bottom of the screen for updates!
A unique indicator that removes emotion and uses clear evidence and rules to capture the market.