[U.S. Interest Rate Limit of 5.2%] Why doesn't the USD/JPY fall even when the Japanese government intervenes? The truth of the "U.S. Treasuries vs. Intervention" playing out just before 159 yen
As of September 25, 2026, USD/JPY remains in a highly nervous tug-of-war in the high 158 yen area.
Last night, there was a momentary plunge from near the 159 yen level (159.04) down to 158.33 yen. And continuing into this morning, statements from Finance Minister Katayama and Economy Minister Shironai rattled expectations that the yen would weaken further.
“With so strong yen-weakening rhetoric from the Japanese government, why did it retreat back to the upper-158s?”
“How long can the abnormal rate of 5.21% on U.S. 10-year Treasuries endure?”
If you waver over today’s headlines, you risk missing the crucial turning point in the market.
This morning’s plunge, the structural reasons why official warnings may not be decisive, and how the durability of “U.S. 10-year yields at 5.2%” will decide the fate of USD/JPY are explained in practical terms.
Chapter 1: What happened in USD/JPY this morning? — The truth of the plunge and the full retracement
First, we’ll sort out the roller-coaster moves from last night into this morning.
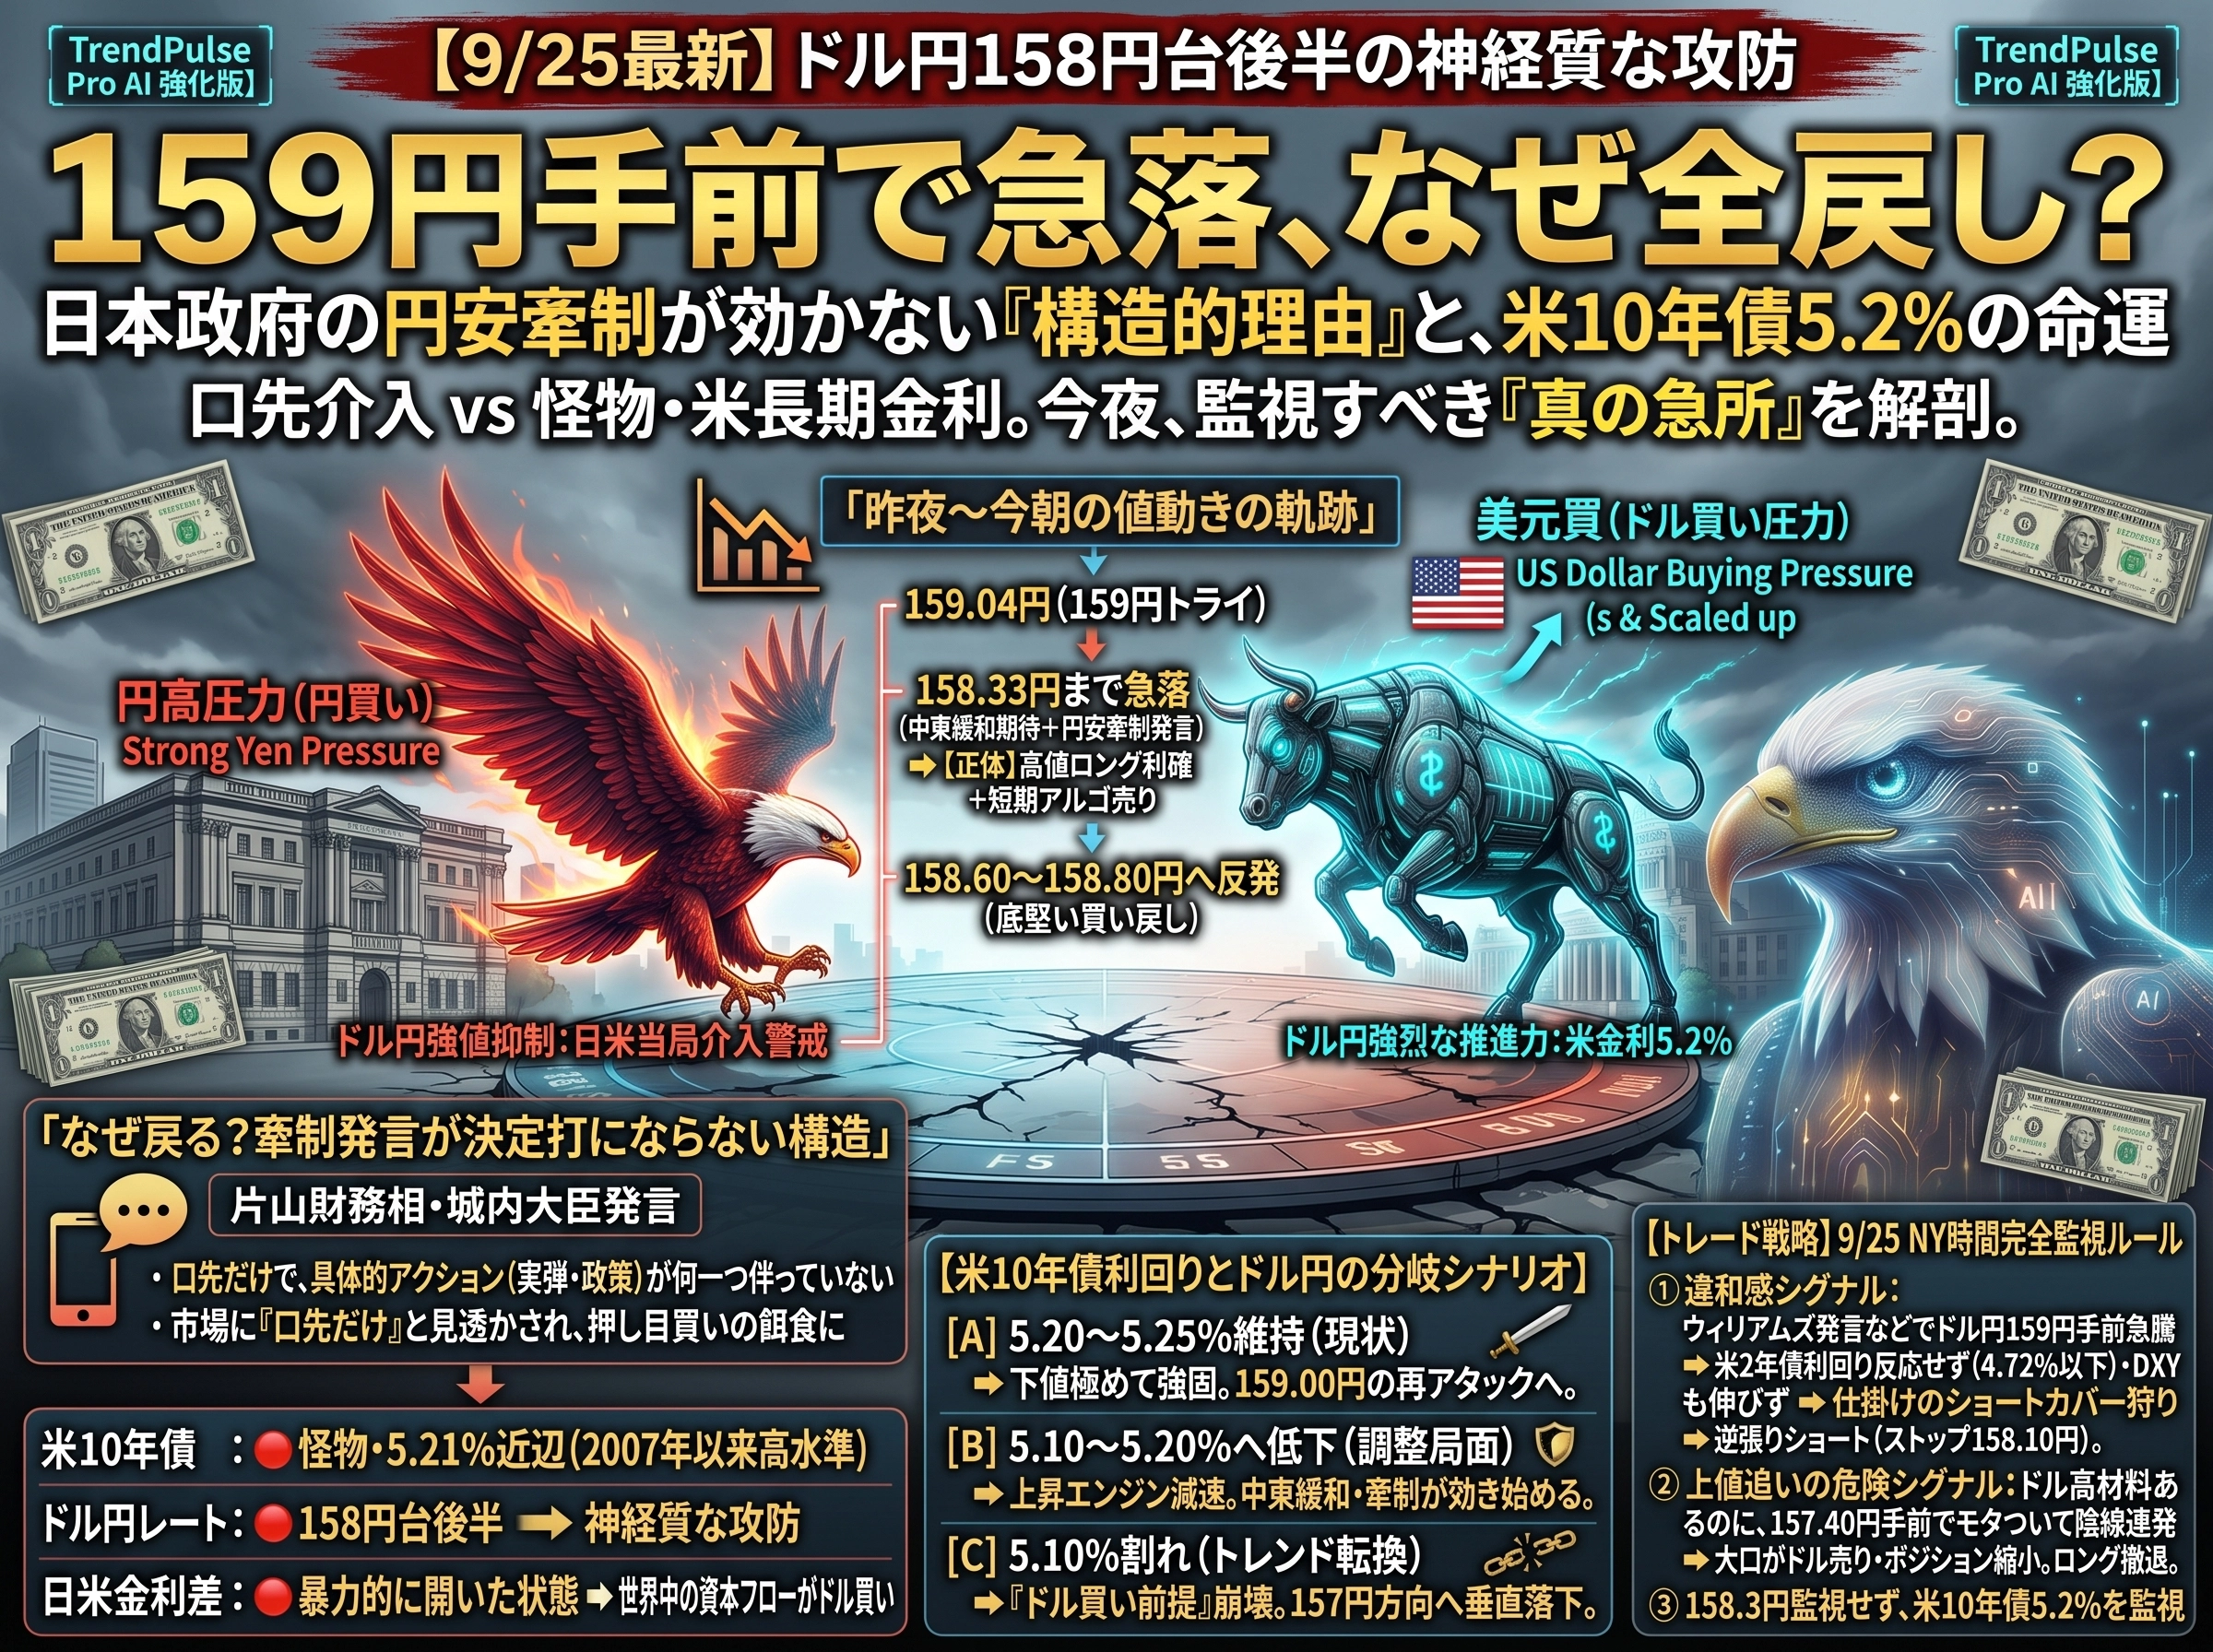
【Trajectory of moves last night to this morning】
159.04 yen (attempt at 159)
  ↓
[Hope for easing Middle East tensions]News of a phased agreement between the U.S. and Iran eases crude prices, long profits booked, lowering to mid-158s
  ↓
[Japanese government’s yen-weakening warnings]Statements by Finance Minister Katayama and Minister Jōnai push the yen down to as low as 158.33
  ↓
[Solid rebound from bargain-hunting]Unable to push lower, on the back of higher U.S. rates the pair rebounds to 158.60–158.80
What is crucial is why, after being knocked down to 158.33, yen buying did not persist and it moved back up.
This morning’s plunge should not be seen as a turning point toward a new yen-strong trend. It was merely a temporary overlay of on-side unwinds from large long positions near 159 and short-term algorithmic selling reacting to government headlines.
Chapter 2: Why Katayama and Jōnai’s comments do not constitute a decisive trend reversal
Around 11 a.m. today, powerful senior officials’ comments shook the FX market one after another.
Finance Minister Katayama:Explained that President Trump’s concerns about yen depreciation were acknowledged, and that Prime Minister Takashi also stated that “underestimation of the yen is a general concern.”
Economy and Finance Minister Jōnai:Drew a hard line: “This is not the era for monetary easing” and “not the era for stimulus measures like Abenomics.”
At first glance, this looks like a potent yen-strengthening factor. Yet the reason the market held at 158.33 is clear.
Because while the stance that “yen depreciation is a concern” was exposed, there was no physical action accompanying it—no concrete currency intervention preparation, no request for further BoJ rate hikes.Thus, market participants calmly saw through it: it was not a shot to be fired immediately, and those waiting to buy the dip seized the opportunity around the mid-158s.
Chapter 3: The powerful momentum behind USD/JPY — what lies behind the monster that is U.S. 10-year yields at 5.21%
The root cause that keeps shrugging off verbal interventions is the 5.2% range on U.S. 10-year Treasuries (around 5.22% intraday, near a multi-decade high since 2007).
【Three reasons U.S. rates jumped to 5.2%】
① Abnormally strong U.S. economic indicators:
 Low initial jobless claims (194k) and strong new-home sales
② Hawks from Federal Reserve officials:
 Presidents of the Philadelphia Fed, Cleveland Fed, and Richmond Fed have each signaled inflation vigilance and potential further hikes
③ Probability of another rate hike at the October FOMC surged to about 70%:
 Market believes U.S. rates are not going down soon, and may rise
The 30-year yield has climbed to the 5.49% range.
With such a violent widening of the rate differential between Japan and the U.S., even if the Japanese side shouts “we don’t want yen weakness,” global capital flows naturally gravitate toward dollar buying.
Chapter 4: Can U.S. rates at 5.2% endure? — Three scenarios
Now to the main question.Can this historic high of U.S. 10-year yields around 5.2% be sustained going forward?
In short: it’s hard to sustain indefinitely, but not yet a material catalyst for a breakdown either.
The market has already priced in a fairly strong U.S. economy and about a 70% chance of a rate hike in October. For yields to break to 5.30%, 5.40% on a runaway basis, further inflation resurgence or extreme data would be required.
Three levels to watch for the future U.S. yields and USD/JPY linkage are described below.
【Break-even scenarios for U.S. 10-year yield and USD/JPY】

? Keep at 5.20–5.25% (current)
 ➔ Downside for USD/JPY remains solid. 158.3 becomes a firm pullback, with a renewed test at 159.00.

? Drop to 5.10–5.20% (correction)
 ➔ USD/JPY upside engine slows. Rebound pressure around the low-158s as Middle East easing and yen-weak warnings take effect.

? Fall below 5.10% (trend reversal signal)
 ➔ The premise of “dollar buying from U.S. rate hikes” collapses.
   A simultaneous drop in crude oil prices, renewed hopes for Middle East cease-fire, and Japan’s intervention warnings would push the pair through 158.30 to about 157.
Chapter 5: External environment check — Where things stand with U.S.-China talks and Middle East dynamics
External factors surrounding USD/JPY also create a stalemate through offsetting pressures.
U.S.-China summit (Trump × Xi Jinping):
Trade truce extended to January 10, 2027, for two months. The worst tariff shocks were avoided, but core issues like tariffs and semiconductor restrictions were postponed to the next negotiations, leaving market impact neutral to slightly risk-on.
Middle East tensions (U.S. × Iran):
Reports of staged agreements toward “reopening the Strait of Hormuz” and “lifting U.S. blockade” led to a pause in oil rallies (Brent around $105, WTI around $93). However, Houthi attacks against Saudi Arabia remain a risk, so danger has not fully dissipated.
The retreat of extreme risk-off caused by external factors has also helped support USD/JPY’s floor.
Summary: Tonight’s watch should be not “158.3” but “U.S. 10-year yields at 5.2%”
The current USD/JPY market is being tugged by two major forces.
【USD/JPY — true power balance】
[Wall that blocks upside moves]Intervention warnings from Japanese and U.S. authorities just short of 159.00
    VS
[Floor that supports downside]The 158.x level supported by U.S. 10-year yields around 5.2%
The key to victory or defeat is not statements from Japanese ministers. It hinges on whether U.S. 10-year yields drop from the 5.2% range.
As long as U.S. long-term yields stay clustered around 5.2%, the willingness to buy dips around 158.30 remains. However, the moment U.S. yields clearly drift toward the 5.1% range, the market landscape will change dramatically.
Do not be swayed by a few tens of a yen; keep monitoring the behavior of U.S. bond yields in advance and trade with discipline by following objective technical signals.
If you found this helpful at all, please consider following us — it would be motivating for updates.
An update incentive you can count on!
? Try the trial version here?
https://www.gogojungle.co.jp/finance/navi/articles/126570?utm_source=share