[Developer's True Feelings] How to Avoid Being Fooled by the “Beautiful Upward Trend” in Backtests — The First Thing to Look at When Choosing an EA: The Hidden Profit Behind It
“Annual profit 300%” “Backtests multiply funds tenfold”
When I see numbers like this, to be honest, my heart still momentarily moves.
In the past, I once looked at the backtest of a certain EA and thought, “This is amazing.”
However, when I looked closely at the performance by period, most of the profit came from a few months of a sharp market.
If I had tested outside that period, the numbers would have been completely different.
Since I became the one who builds EAs, my eye for backtests has changed dramatically.
Whenever I see flashy numbers, I now first think“How much back-end strain and desperation were forced to achieve these numbers?”and I consider it this way.
In my 10 years in FX, and now while creating MT5-oriented EAs and indicators and running hundreds of backtests, I strongly feel this.
This time, I will write not only about the profitability magnitude when choosing an EA, but also about what I started looking at myself.
Why do “high-profit EAs” tend to be pitfalls?
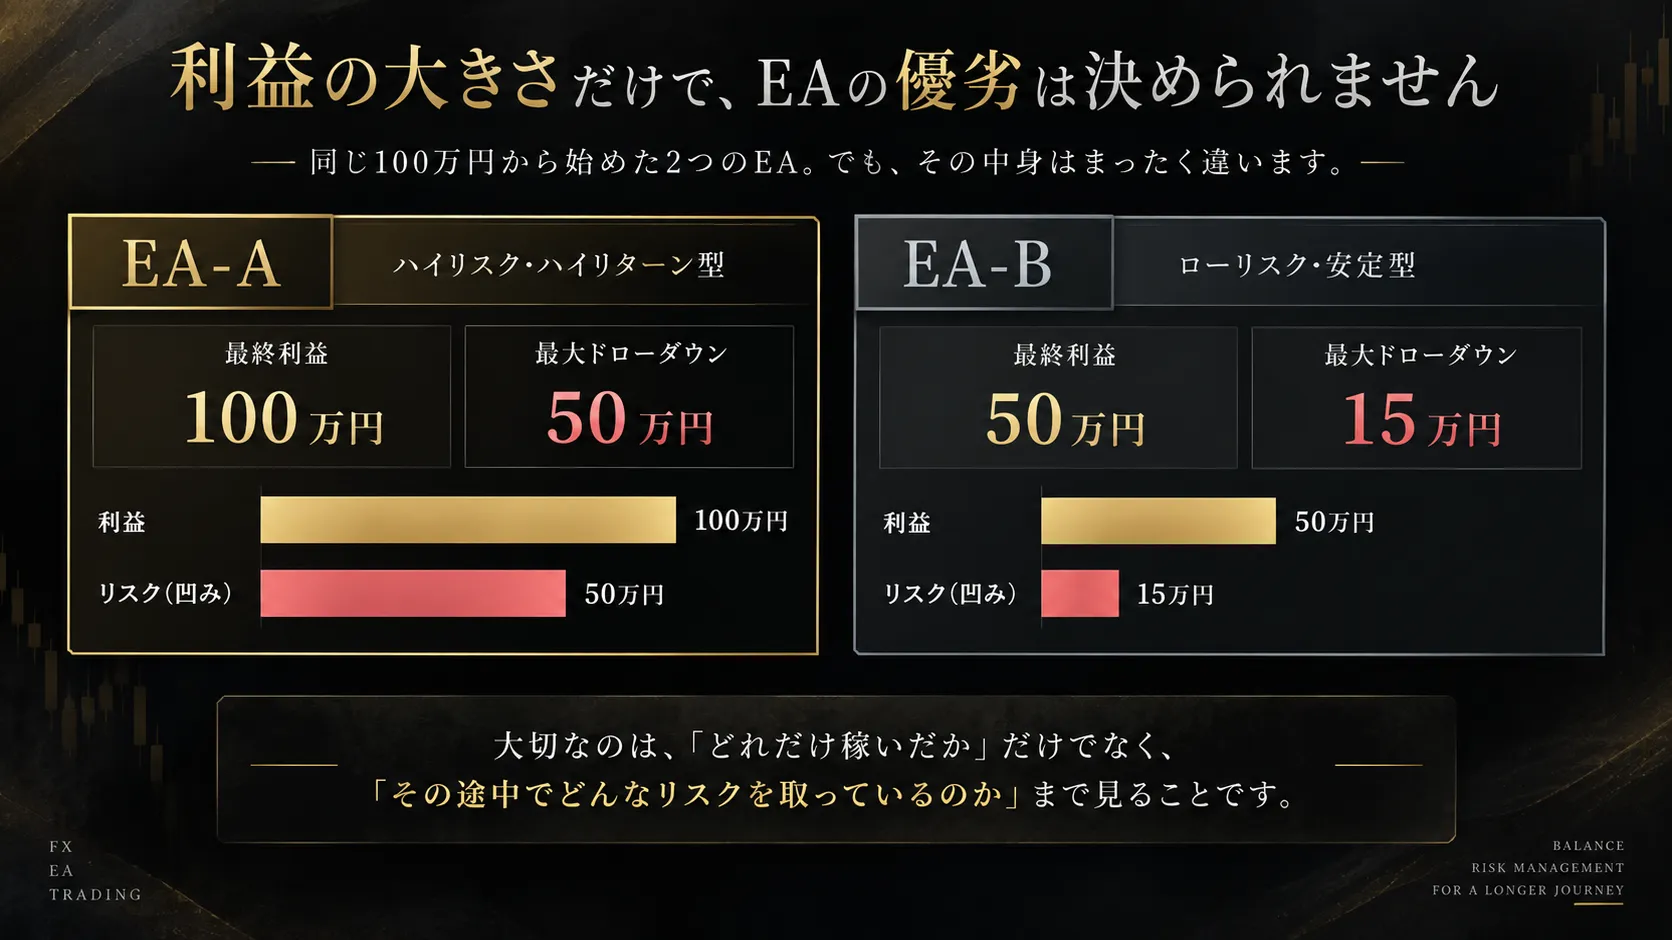
For example, there are two EAs starting from the same 1 million yen.
-
A: Annual profit of +1,000,000
Endured nearly 500,000 yen of severe drawdowns mid-way, and barely reversed with averaging down and larger lots. -
B: Annual profit of +500,000
Proper stop-losses (SL) are always set, and profits grow steadily while keeping the maximum drop around 150,000 yen.
If you look only at the numbers, A is more appealing.
But types like A may stop in the middle of real operation due to inability to withstand drawdowns, or at worst, fail to adjust lots at the right time and end up reducing assets significantly.
In fact, among the EAs I have tested in the past, there were many such cases.
If you look not only at the surface profit but also at the following underlying conditions, honestly, I feel a bit embarrassed about “the self who only looked at profits.”
- What lots are used
- What is the maximum loss per trade
- Whether averaging down or martingale is used
- Whether there are years with exceptionally high profits
As much as “how much you earned,”“what kind of fear you will taste during the process”is important.
The reality that backtests can create an “impeccably rising right-hand curve”
What surprised me most in EA development was that making the backtest graph look like a clean rising curve is not technically that difficult.
“Do not allow trading during this time zone because it tends to lose” “If this value is exceeded, do not enter”
If you add conditions one by one to fit past chart data, losing trades disappear neatly.
It becomes a so-called “god backtest” perfectly fitted to historical data.
In the early days of my own development, I rigidly fixed the conditions and created a prototype with “win rate 95% and a clean rising curve,” and I would boast alone, thinking, “this might be genius.”
However, once I moved it to forward testing (real-time demo operation), it could not adapt to market patterns unseen in historical data and was quickly crushed.
I had created an EA that was abnormally strong only for past markets (overfitting).
After this failure, whenever I added conditions to improve performance, I began to strongly question myself, “Is this merely forcing past data into shape?”
If you increase unexplainable conditions and the backtest only looks better, it may be a different issue whether it is effective in real operation.
The meter of profit and risk is always linked
By EA design, you cannot raise the return meter independently.
If you raise the lots, profits increase, but the latent drawdown and maximum drawdown also expand by the same multiple.
If you loosen entry conditions, the number of trades increases and opportunities rise, but you will certainly also pick up poorer-quality entries.
If you want to gain something, you have to take on another risk—that's a trade-off that remains true in the EA world as well.
Choose not the “most profitable EA” but the “EA you can operate”
In the end, I think this is the point.
Some people can operate even with a maximum drawdown of 30%, while others would stop the EA with only 10% drawdown.
Some people prefer daily trading, while others do better with an EA that waits days for all conditions to align.
There is no absolute right answer.
No matter how clean the backtest, if the system cannot sleep well at night due to drawdown, then it is an “unusable EA” for you.
What matters is not only the final backtest profit but also confirming how the profits are generated and what risks the EA takes along the way.
Since I myself have shifted from user to builder of EAs, this is what I focus on now.
Conclusion (Next time preview)
“I understand the theory, but then exactly which parts of the backtest should I look at to spot over-optimization or hidden risks?” you may be wondering.
Next time, I will write about five concrete points (PF, DD, number of trades, win rate, trap of period) that I first check when examining backtest data for my own EA verifications or when evaluating new EAs, with real examples.
I will continue to write from the perspective of a validator, not a seller’s marketing claim, so please come back to read it again if you like.