What is happening at 9:55 in Tokyo? Read the mechanism of the announced market (公示相場) from primary sources
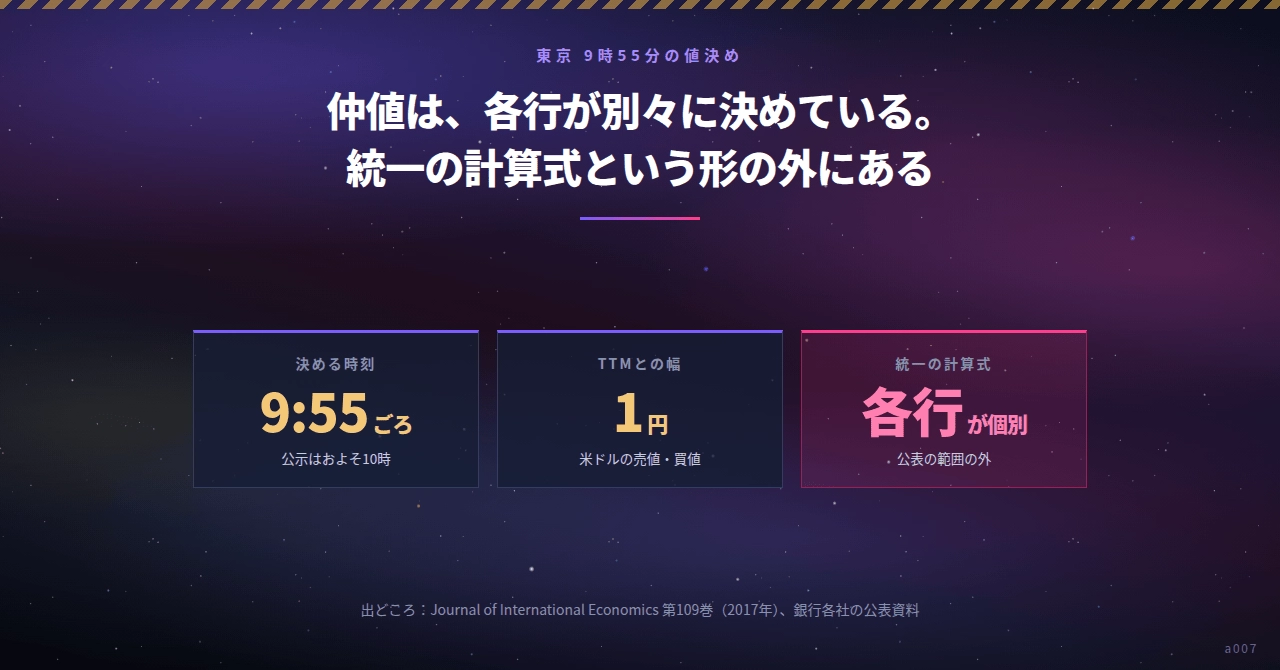
Fixing time 9:55approximately The official publication is around 10:00 | Spread with the TTM 1yen Ask/bid price for US dollars | Unified calculation formula Each bankindividually outside the published range |
When selling or buying foreign currency at a bank counter, there is a rate that serves as the daily benchmark.Customer-transaction telegraphic selling rate benchmark (TTM)This is what it is. In the market, it is called the fixing.
This article reads how that fixing is created, using materials published by banks themselves and peer-reviewed public papers.
Tokyo's fixing is determined independently by each bank based on the actual rates around 9:55. There is no unified management or formula beyond the published range.
Banks publish the following three values every business day.
| Symbol | Name | Contents | US dollar example (TTM basis) |
|---|---|---|---|
| TTM | Fixing | The central value that becomes the day's benchmark | Benchmark |
| TTS | Telegraphic selling rate | The rate at which banks sell foreign currency to customers | TTM + 1 yen |
| TTB | Telegraphic buying rate | The rate at which banks buy foreign currency from customers | TTM − 1 yen |
In整理 of published papers, the range for customer sell and buy is described as taking 100 basis points (1 yen) above and below the fixing. In banks’ actual published materials, the same level appears for the US dollar.
Also, one bank includes on the same page a note: “For transactions of equivalent to 100,000 USD or more, the exchange rate determined by market practice will be applied.” This means that there are monetary thresholds within which the published rates apply.
This is the most important part of the article. Public papers summarize Tokyo’s fixing as follows.
Each bank, based on its own trading price in the interbank market around 9:55,individuallysets the fixing. The explicit windows and calculation rules should stay outside the published range, and each bank is free to set values within the price range it actually transacted in that area.
Rules also apply after publication. The published market rate applies to customer transactions on that day. Orders placed before or after publication receive the same rate.
This design of “one value per day” defines the nature of the fixing. Market rates move by the second, but the customer benchmark is fixed daily. The moment of fix is concentrated around around 9:55.
Bank public materials also include a common disclaimer: “In response to market developments, we may temporarily change the published rate.” Several banks include this on the same page.
Public foundations also describe that if a large market movement occurs within the day, there will be a halt or modification of the fixing.
So, when would a change occur?The exact numeric threshold is not found in the banks’ materials, industry group documents, or peer-reviewed papers accessible here.There are rough figures discussed in the market, but they could not be traced to primary sources. This article leaves that blank.
That the fixing serves as the day’s benchmark for customer transactions means that the 9:55 time has meaning for those who want to settle actual needs at that benchmark.
When importers need to pay in foreign currency, they must buy foreign currency. If they settle that day’s payments at the fixing, banks will balance that demand in the market. With a fixed time and a fixed direction of demand,these demands overlap in the same time windowfor the same period.
Thus far, this is a mechanism-based discussion. Empirical questions about whether price movement in that time window shows any bias, and how large it is, will be covered in the next article.
Another point from the mechanism side: this demand arises not so much from market sentiment but from the calendar. Import settlement dates are determined by contracts and conventions, and those dates are known in advance.The time is fixed, the direction is fixed, and the dates are predetermined. Having all three together is rare in the FX market.
However, even if they line up, it does not necessarily imply a measurable bias in price movement. Market participants see the same calendar. Known demand is factored in in advance, so empirically any bias is examined by counting in data after accounting for costs.
If focusing on the vicinity of the fixing, there are three practical decisions to make in advance.
| What to decide | Contents | Reason |
|---|---|---|
| Time window | How many minutes before and after to look | Extending the window later dilutes the meaning of the numbers |
| Date to target | Which calendar day to call the target date | Fixing the definition in advance eliminates later disputes |
| How to quote prices | Use the midpoint of buy and sell, or use actual deal prices | Costs are treated differently |
In particular, the third item greatly changes how the results appear. Values counted at the midpoint exclude the spread; if you actually place orders and miss, those costs are counted both ways. For small-penny differences, this can even flip the sign of results.
Therefore, when looking at values counted at the midpoint,view them together with the costs subtractedto avoid misinterpretation.