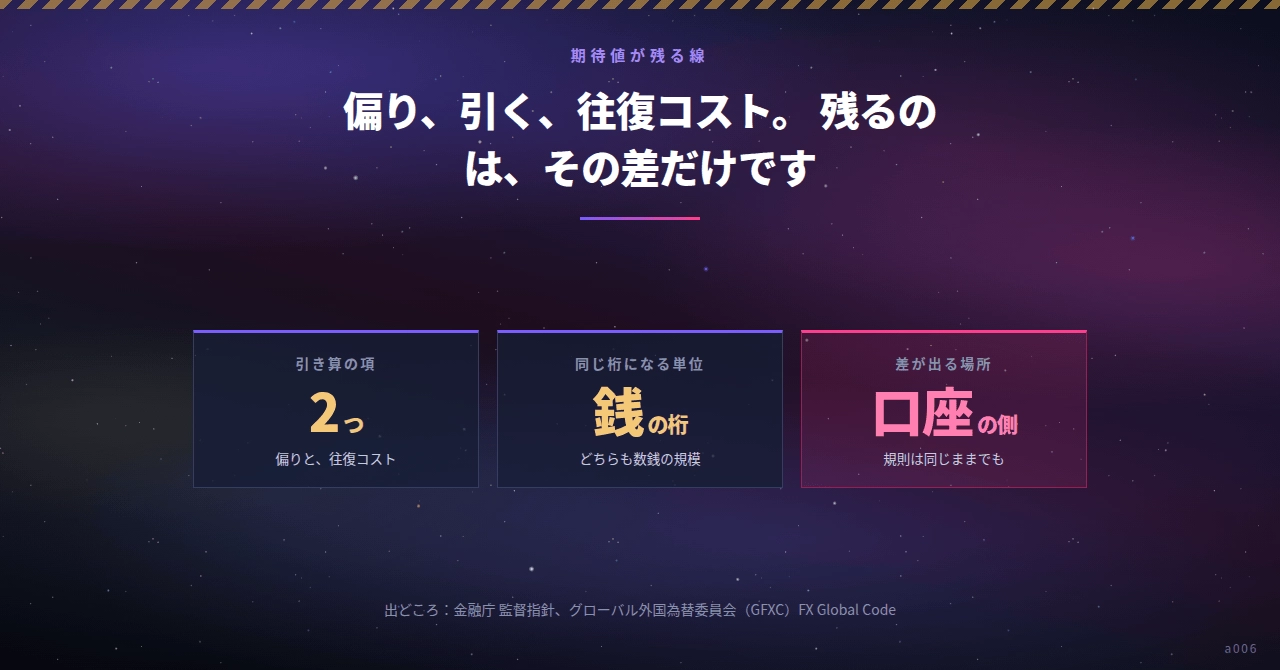
Inclination of round-trip cost. This subtraction determines all methods with short holding times
Subtraction terms 2つ Bias and round-trip cost | Units that become the same digit 銭の桁 Both are on the scale of a few sen | Where a difference appears Accountside Even if the rules stay the same, |
In designs that aim for a few sen price range within a short holding time, the expected value calculation takes a very simple form.
Expected value per trade = Average observed bias − Round-trip cost. This article deals only with this subtraction.
In a short holding-time method, the observed bias and round-trip cost line up in the same digit. Therefore, the portion left to you is determined more by the account side than by the rules.
If you aim for ranges of tens of sen to several yen with a longer holding time, even if round-trip cost is around 1 sen, its share of the result remains small.
On the other hand, when one holding period is tens of minutes and the target width is a few sen, things change. The average observed bias and round-trip costsline up in the same digit, which is why the subtraction result strongly affects the account-side numbers.
| Design | Target width digit | Round-trip cost digit | Proportion of cost |
|---|---|---|---|
| Lasting hours to days | Tens of sen to yen | About 1 sen | Small |
| Lasting tens of minutes | Several sen | About 1 sen | Large |
Round-trip cost consists of three parts: the spread (one-way cost for inbound and outbound), the round-trip fee, and the slippage average.
Here, the symmetry of slippage seen in the previous article comes into play.Slippage symmetryIf slippage is symmetric, its average is near zero, and round-trip cost is basically determined by spread and fee. If it is biased, that bias is carried entirely by round-trip cost.
Financial Services Agency's supervisory guidelines flag as inappropriate any setting that slides unfavorably for customers. Whether symmetry holds directly affects the expected value calculation.
One method to verify this subtraction’s property is this: Fix the rules and data, and vary only the round-trip cost.
If you change the rules, you can't clearly separate whether the result difference is due to rules or costs. So you keep one variable. This is standard experimental practice, though it’s often overlooked in method validation.
Place round-trip costs in several scenarios. For example, apply the spread as it appears in data. A scenario with fixed spread. A scenario with thicker slippage. Run the same rules in each, andsee where the remaining amount disappears.
This format makes interpretation clear. If you leave costs small and the result remains, but in a large-cost scenario it disappears, then the method isstrongly cost-dependent. If it remains in all scenarios, dependence is weak. If it disappears in all, the bias magnitude is the problem.
And once you know it’s a strongly cost-dependent design, your next steps are decided. Before adjusting rules, you shouldmeasure your own account’s costs.
| Result of running | Reading | Next steps |
|---|---|---|
| Remains in all scenarios | Cost dependence is weak | Can continue over a wide range |
| Only small-cost scenarios remain | Strongly cost-dependent | First measure the account’s effective cost |
| Disappears in all scenarios | Redesign starting from scenario selection |
From this subtraction, one practical tool emerges.Upper bound line for round-trip cost.
By subtracting the smallest residual that is tolerable from the average observed bias, you get the upper bound for round-trip cost. If you fix this line in advance, you can decide to proceed or not based on whether the account’s measurement result lies inside or outside this line.
If you arrange it this way,your decision is determined solely by the measurement results. The day’s market sentiment has no place outside this flow.
How you treat the scenario outside the line is also decided in advance. You may decide to pass on that account. A result that suggests passing is also evidence that measurement is at work.
Let’s push this discussion one step further. This line can also serve as a yardstick when choosing accounts. Measure several accounts with the same procedure, compare their effective round-trip costs, and you’ll get a numeric answer forwhich accounts fall inside the line.
Placing spread numbers from ads side by side is a separate task from this one. The former shows quoted values; the latter compares actual paid values. The order is to narrow candidates with ads, then decide by measurement.
And measurement costs real funds. Even the smallest quantity incurs spreads and fees on every round trip. Therefore, there is value indrawing the line before measuring. If the line is fixed, you can also estimate the required number of trading days in advance.
That subtraction is simple, which also means limited design freedom. If the target scenario is fixed, the holding time is fixed, and the cost line is fixed, the remaining judgment space is very small.
This shape fits someone who is comfortable following the set procedure exactly. Conversely, for someone who wants to add judgments on the fly while watching the market, the design may feel constraining. Before judging which is better,the personality fit becomes apparent in this design.
Another point: since this design’s target scenarios are calendar-driven, whether you can be in front of the screen at that time becomes a factor in execution. This is a condition you can check yourself before measuring.