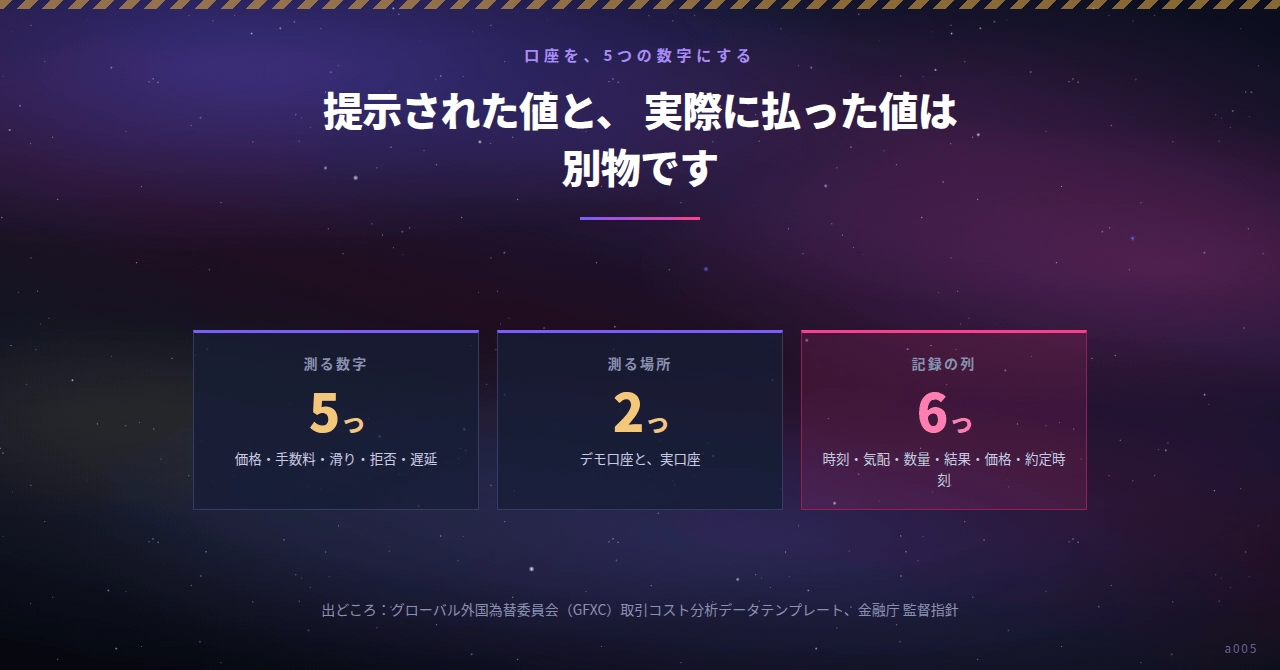
The quality of an account can be stated with five numbers — spread, fees, slippage, rejection, and delay
Measured numbers 5 aw Prices, fees, slippage, order rejection, delay | Where to measure 2 aw Demo account and real account | Records required 1 per item Time, quotes, execution price |
When comparing accounts, the first thing you notice is the quoted spread. However, whether a trade executes at that price the moment you place the order is another matter.
This articleorganizes the targets and procedures for counting the actual round-trip costs you payin your own account. In international terms, this process is called trading cost analysis (TCA).
The quality of an account can be described by five numbers: spread, fees, slippage, order rejection, and delay. The values shown and the amounts actually paid are different things, and only the latter is deducted from the expected value.
What can be measured as the quality of an account can be organized into the following five items. Each can be recorded by trading both directions in your own account.
| # | What to measure | How to record | What it affects |
|---|---|---|---|
| 1 | Spread | Difference between the bid and ask price at the moment you submit the order | Basis of one-way cost |
| 2 | Fees | Amount deducted per execution. Count in both directions | Added to one-way cost |
| 3 | Slippage | Difference between the price at submission and execution price. Keep with sign | Shows not only the average but the tails (extremes) |
| 4 | Order rejection | Time, quantity, and quotes at the moment of rejection | Actual percentage of orders that were not filled |
| 5 | Delay | Time from submission to receipt of execution notification | How delays affect performance in fast markets |
Out of these, 1 and 2 may be published even before you start trading. The remaining 3, 4, and 5 become numbers only after you trade in both directions yourself. And among these, the differences across accounts are larger..
International codes of conduct have laid out a more thorough framework for trading costs analysis. The Global Foreign Exchange Committee (GFXC) strengthened guidance on trading cost analysis, algorithmic trading, and disclosures in its July 2021 revision, and introduced a 'disclosure cover sheet' for liquidity providers and electronic trading venues, a due diligence template for algorithms, and a data template for trading cost analysis.
The fact that templates are prepared impliesthe format for comparison is taking shape. The same approach can be adapted for individual accounts at a smaller scale.
Demo accounts may have a different execution mechanism from real accounts. Relying only on demo records can lead to misjudging the real account’s characteristics.
Therefore measurements are two-stage. First, in the demo account, verify that the recording mechanism itself works correctly. Then switch to a real account andperform real-round trips with the smallest quantity. The spreads and fees incurred then are, of course, actual costs.
The number of trading days measured in the real account depends on the dispersion; more days reduce scatter, but each round trip costs money. It’s a matter of balancing desired precision with cost.
The most common omission in measurement is wanting to change conditions later. To avoid this, fix the form of records before measuring.
| Column | Contents | Reason |
|---|---|---|
| Time | Sent time (to the millisecond) | Used to separate delays and scenarios |
| Quote | Bid and ask at submission | Foundation for the quoted spread |
| Quantity | Order quantity | To see fill rate by quantity |
| Result | Filled, rejected, or void | Fix the denominator and numerator of rejection rate |
| Execution price | Actual executed price | Produces sign and magnitude of slippage |
| Execution time | Time when execution notification returned | Show delays |
Record first, before making judgments.If you look at results first and then change measurement methods, the meaning of the numbers becomes diluted.
If you look at the five numbers separately, you won’t have a decisive judgment about the account quality. Therefore, finally summarize into one line.Realized base round-trip cost.
Count half the bid-ask spread for each direction, add the round-trip fees, and add the signed average of slippage. This total is the amount that leaves your hands in one trade. If you multiply by the order-rejection rate, you also obtain the cost per actual executed trade.
| Situation | Quoted base round-trip | Average slippage | Realized base round-trip |
|---|---|---|---|
| Quiet periods | Small | Small | Close to quoted base |
| Around news releases | Wider | Likely larger | Moves away from quoted base |
| Open of the week in Asia | Wider | Likely larger | Moves away from quoted base |
The trading approach you are applying and the time of day you trade determine the realized base round-trip cost. Relying only on the average of quiet times to choose an account can be misleading here.
Conversely,you only need to measure the times you trade. Averaging across the whole day is unnecessary here.
Finally, one use for this line. If your strategy has an expected gain of only a few cents per trade, the realized base round-trip cost and your strategy’s cost will be in the same order of magnitude. In that case, changing accounts can have a larger impact on your take-home than changing strategies.
Conversely, if your target per trade is tens of cents, the cost difference will be a smaller share of outcomes.Priorities for measuring costs depend on the magnitude of the target gain. Deciding which side you are on in advance reduces indecision.