Three common points among 3 EAs that were created for 1 month and used on real money: three features that separate a 3.3% survival rate
"We are in an era where we can create a large number of EAs with AI, but what percentage actually remains usable?" This is the realistic question that anyone starting to self-create EAs would be most concerned about.
Nowadays you can have Claude write a single EA in just a few minutes, but whether it can endure real-money conditions is a completely different story.
For one month, I kept having Claude Code write MQL4, and I verified over 90 EAs cumulatively on EURUSD and GOLD.
Among them, the number that progressed to live-testing and remained under continuous monitoring was3, a survival rate of 3.3%.
However, these three share three clear common points, and whether you grasp these common points in advance greatly changes the survival rate.
Please refer to the article contents.
? Table of contents
▼ Free release
▼ Read more for release
The four clear criteria for “usable in real money”
First, I will clearly define the criteria for “usable in real money” as mentioned in this article. If this is vague, the meaning of the survival rate changes, so I defined it in four stages.
Four-stage pass criteria
- Stage 1: Backtest— 6 years full period plus, monthly +1% or more, maximum drawdown 5% or less
- Stage 2: Walk-Forward validation— Training period to unknown period results in deterioration within 30%
- Stage 3: Real operation equivalent validation— Reproduce with real spreads and slippage using tools like Forex Tester
- Stage 4: Demo operation— About half of the backtest numbers can be produced in a 3-month demo account
Passing all four stages = 3
Meaning: all four stages were passed by 3 EAs.
There were over 20 EAs among the 90 that showed clean numbers in backtests, but most collapsed under Walk-Forward.
In particular, Walk-Forward validation of Stage 2 is the harshest filter, with more than half dropping out here.
Using AI to develop EAs is normal, and this is a painful reality.
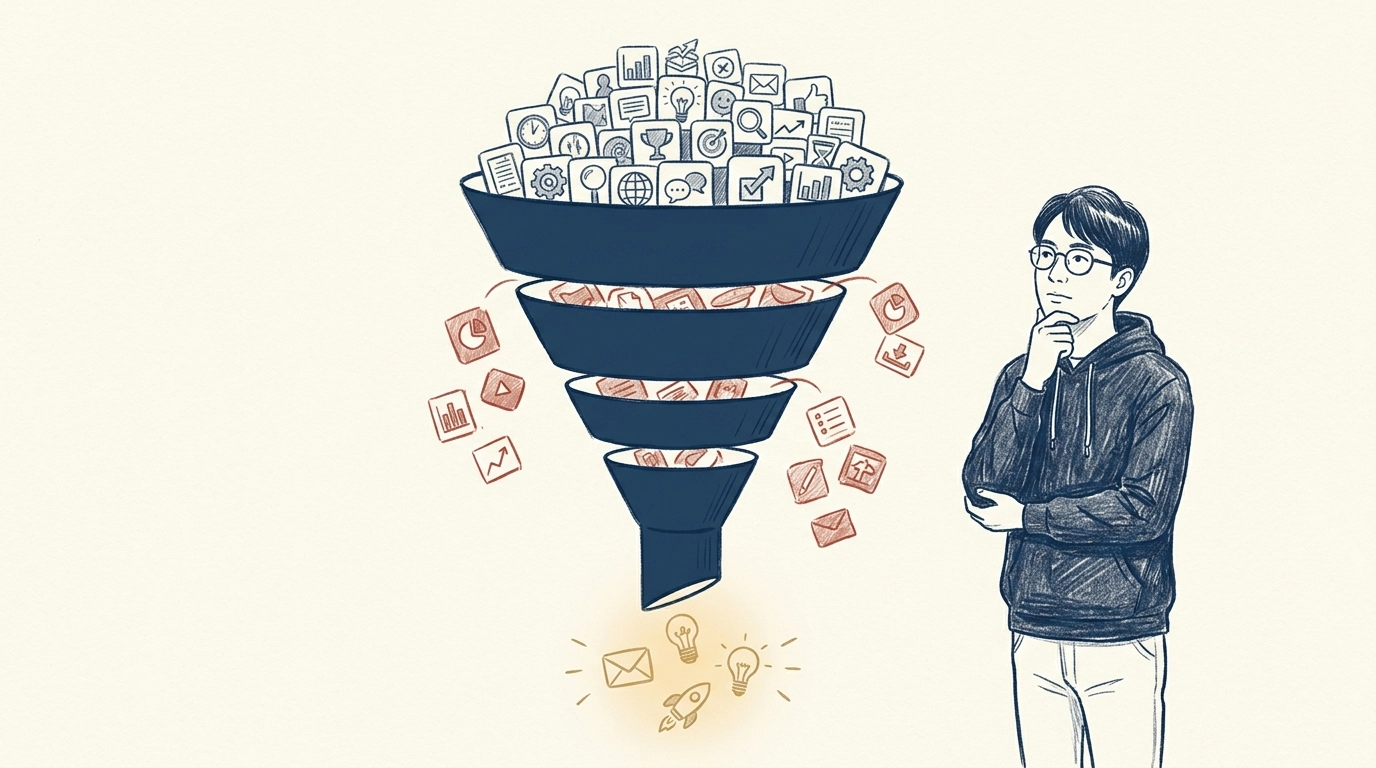
90 → 3: Stage-by-stage survival counts
I will lay out the four-stage survival counts in order. At each stage you can see where and how many dropped out.
Stage-by-stage survival trends
- Among 90, backtest positive: approximately20 (22%)
- Backtest positive and Walk-Forward passed: approximately7 (35%)
- During WF passed and real operation OK: approximately4 (57%)
- Real operation OK and 3 months of demo continued: 3 (75%)
Reasons for drop at each stage
I will show numerically why each stage failed.
- Stage 1: Reasons for 70 dropouts: Most individual indicators are negative; textbook presets systematically do not pass
- Stage 2: Reasons for 13 dropouts: Backtests with clean numbers are mostly overfitting/period-specific
- Stage 3: Reasons for 3 dropouts: Incorporating real spreads and slippage halves the expected value, threshold breach
- Stage 4: Reason for 1 dropout: If the market environment changes in a demo, the expected behavior diverges and is excluded from continuous monitoring
Survival rate from 90 to 3 is 3.3%. The idea of “finds winners by mass-producing EAs with Claude” is something you should approach with this number in mind.
More importantly,the key is to have a rigorous verification eye at each stage, I believe.
By filtering through each stage, you’re envisioning weeding out truly usable ones.
From here on, I will write about the three common points of the surviving three (low-correlation edge-prone design / not using textbook defaults / not falling in Walk-Forward) and three practical proposals for Claude EA authorsThis is especially practical content for those creating EAs.
What follows (Read more) will be released:
- Common point①Edge-prone design with low correlation(Diversification, rather than single strongest)
- Common point②Do not use textbook default values(Parameters outside conventional doctrine)
- Common point③Not falling in Walk-Forward(Maintain efficiency in unknown periods)
- To Claude EA authorsThree practical proposals
- ThreeActual operation images(Individual around +0.2% per month, combined +1–2% per month)