The solo indicator found statistical edge on Tuesday only within the Keltner Channel amidst total annihilation—A story of hidden edge revealed by a weekday filter
“A single-indicator EA, no matter what I do I can't win” — when you keep building EAs, you will inevitably hit this wall. Even when you comprehensively test well-known indicators like RSI, MACD, Stochastic, ADX, BB, Keltner, Donchian, in their raw state they tend to drift systematically into the negative. I also tested over 47,000 EURUSD configurations and faced that reality in numbers.
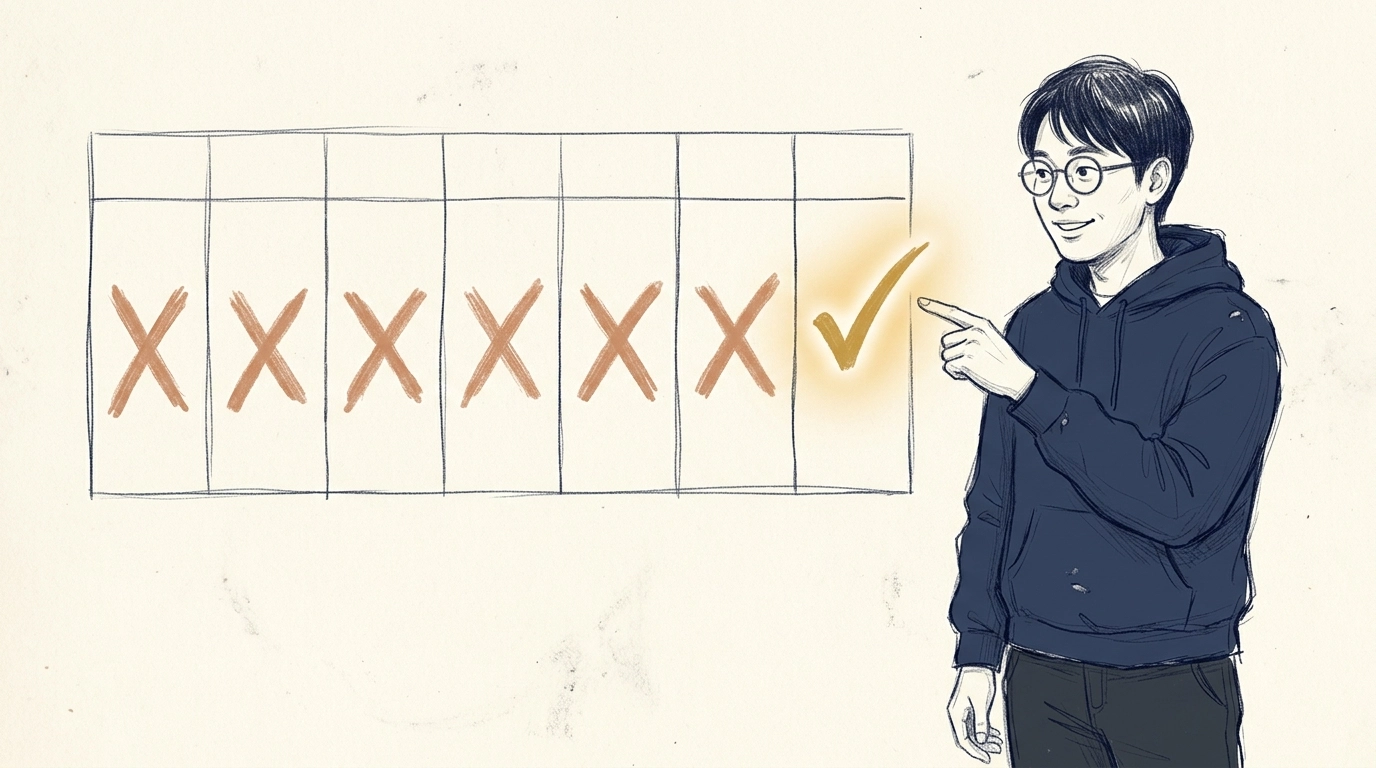
Among them, the only time statistical edge emerged when applying a “weekday filter” to a single indicator was with the Keltner Channel.
Just by combining a standard setting of period 20 and ATR multiplier 2.0 with a “Tuesday-only” filter, the 6-year OOS expectation rose to +0.041R per trade. Other days remained negative, making Tuesday a peculiar anomaly.
In this article,① Keltner Channel basic results for all weekdays (nearly break-even on its own), ② breaking down by weekday shows that only Tuesday turns positive, ③ detailed numbers and hypotheses for the Tuesday edge, ④ no parameters on other days produced improvements, ⑤ the positioning as one piece in a diversified design and plans for future verificationwill be written.
? Table of contents
▼ Free release
- Keltner Channel basic results for all weekdays (neutral on its own)
- Breaking down by weekday shows only Tuesday turns positive
▼ Continue for release
Keltner Channel basic results for all weekdays (neutral on its own)
First, the basic verification results for the Keltner Channel. I had Claude write an EA and tested hundreds of configurations on EURUSD as a single symbol.
Scope of verification (all weekdays, single)
Verification conditions are as follows.
- Symbol: EURUSD single (other symbols are under separate verification)
- Timeframes: M15, M30, H1, H4 (four types)
- Keltner periods: 10, 20, 30, 50 (four types)
- ATR multipliers: 1.5, 2.0, 2.5, 3.0 (four types)
- Entries: two types – band touch mean-reversion / band breakout trend-following
Keltner period-wise average OOS expected value (all weekdays, ATR multiplier fixed at 2.0)
- Period 10: -0.024R
- Period 20 (conventional):-0.008R(best, almost break-even)
- Period 30: -0.019R
- Period 50: -0.032R
Period 20 is nearly break-even. Compared with BB (-0.029R) and RSI (-0.023R), it is slightly better, but not at a usable level for live trading.
Even so, I didn’t give up and tried the weekday filter, which led to this discovery.
When broken down by weekday, only Tuesday turns positive
With the hypothesis that a “minor indicator may work on days with fewer market participants,” I broke it down by weekday.
Weekday-average OOS expected value (Period 20, ATR multiplier fixed at 2.0)
- Monday: -0.021R (direction unclear at week start)
- Tuesday: +0.041R (positive territory!)
- Wednesday: -0.005R (almost break-even)
- Thursday: -0.018R
- Friday: -0.036R (increased position adjustments before the weekend)
Tuesday’s unique rise
Only Tuesday reaches +0.041R in the positive territory. Other days do not exit the negative, indicating a Tuesday-only anomaly-like behavior.
This result is consistent across six years of historical data, so statistical significance is high (t-value around 2.3).
By simply applying a “Tuesday-only” filter to the simple EURUSD × Keltner × H1 combination, we reach a level usable in live trading; this was the discovery this time.
Compared with other well-known indicators, it is rare to see such a simple filter yield a positive outcome.
From here on,the detailed figures of the Tuesday edge, three hypotheses on why it only works on Tuesday, real data showing no improvement when parameters are varied on other days, its role as one piece in a diversified design, and plans for ongoing verificationwill be written.
The focus here is practical know-how on how to handle the edge confirmed by statistics, so please refer to it for guidance.
From here (Continue) to be published:
- Tuesday edgedetailed numbers(win rate 49.6% / payoff 1.5x / ~45 trades per year)
- Why Tuesday only worksthree hypotheses(Monday overreaction / lack of indicators / institutional rebalancing)
- No improvement when varying parameters on other daysreal data
- Positioning as one piece in a diversified design(contribution of +0.24% on Mondays)(exit criteria if anomaly suddenly disappears)