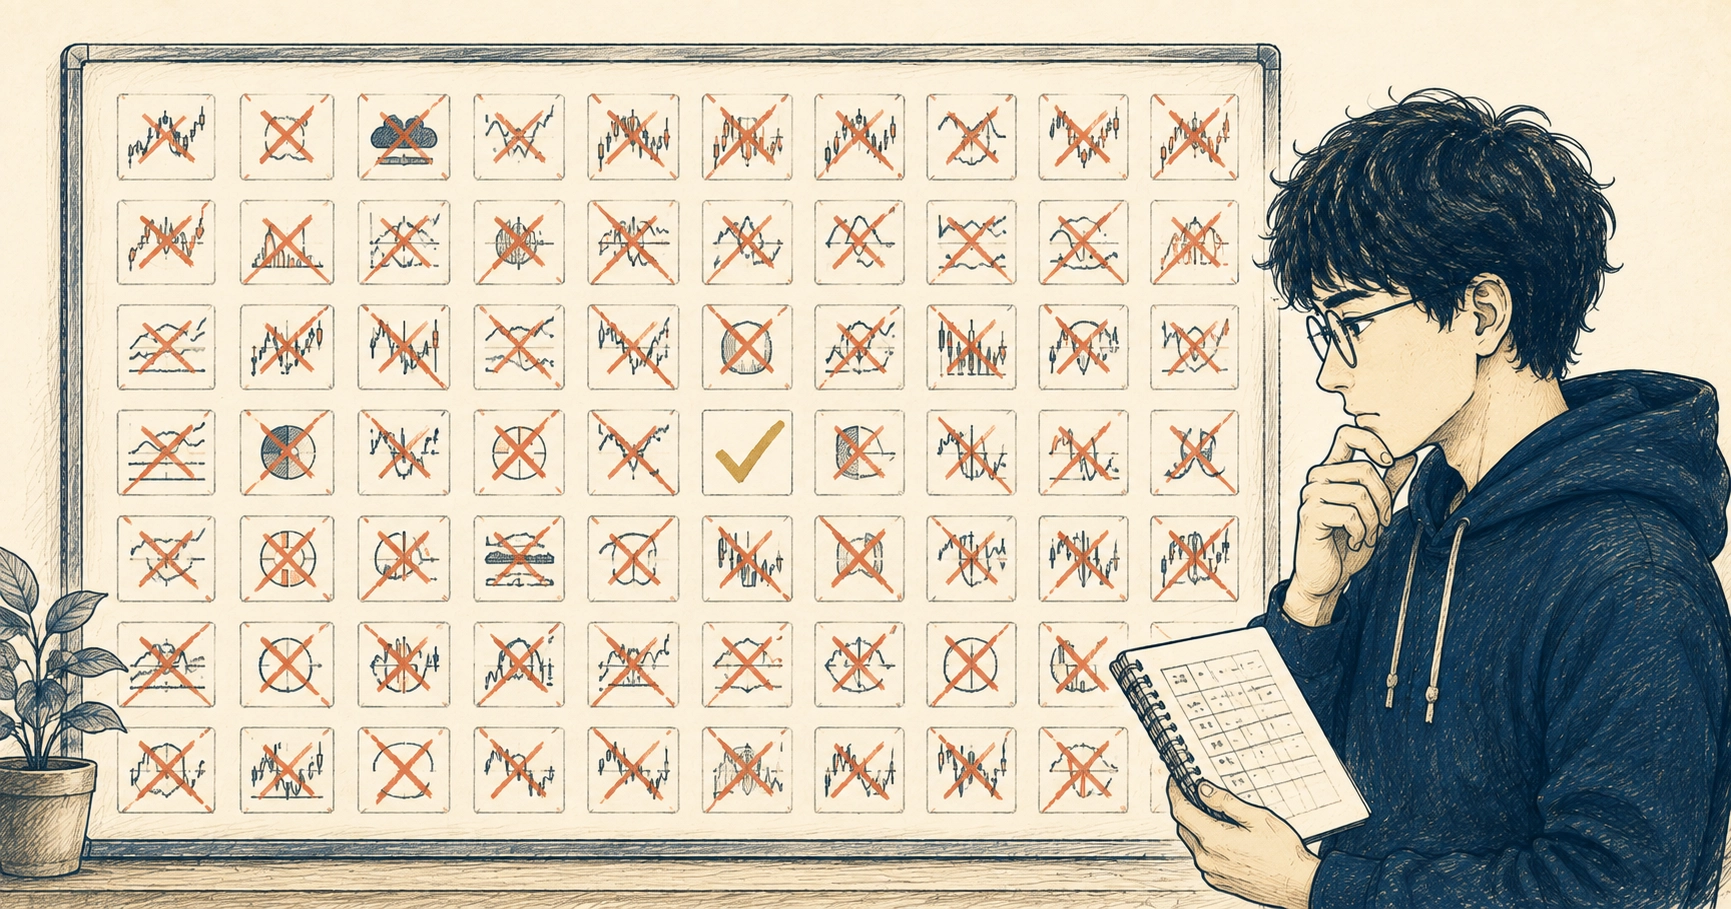
Validation record that annihilated the standalone indicator 91 logic with EURUSD — The "mathematical ceiling of a single EA" seen in 47,000 configurations
“Does RSI actually work?” “Is the MACD Golden Cross still usable?” ── An indicator that has long been treated as a given, how far does it actually perform in real markets? I thoroughly tested this question using EURUSD1 as the instrument.
7 timeframes × 91 indicator logics × parameters × exit designs × stop widths, cumulativeover 47,000 configurationsin backtests.
In short,the only single-indicator EA that was statistically positive was RSI(28); all other 90 logics were negative.Even RSI(28) fell short of the target performance (monthly +5% / DD 5%) in EURUSD alone by 6.7x. “Stable side income from a standalone EA” is mathematically impossible in EURUSD. This article records the full details.
In this article,
① distribution of 47,000 configurations (what percentage were positive), ② the fact that out of the 91 standalone indicator logics, only one was positive, ③ the reason RSI(28) was an exception, ④ why the MTF environment recognition gate 3,552 configurations couldn’t save them, ⑤ why achieving target with a standalone EA is mathematically impossiblewill be written with actual numbers only.
? Table of contents
▼ Publicly available for free
- Distribution of the 47,000 configurations — what percentage were positive
- Record of all-ruin for the 91 standalone indicators
▼ Publiced in the full article
- System-specific Parameter Sensitivity — full comparison of best and worst values
- Records of the MTF environment recognition gate that even 3,552 configurations couldn’t save
- The meaning of the mo/DD ceiling 0.149 for a standalone EA and the distance to the target 1.0
- The remaining path is diversification — conclusions indicated by the tuition of 47,000 configurations
Distribution of 47,000 configurations ─ what percentage were positive
First, look at the overall distribution of the 47,000 configurations that were tested.
In EURUSD1, the combinations involve seven timeframes from M1 to D1 × 91 logics × 8 exit types × 4 stop types × other factors.
Performance distribution for the full period (all 47,000 configurations)
- Monthly return +5% or more: about 19 configurations (0.04% of the total)
- Monthly return +3% to +5%: about 108 configurations (0.23%)
- Monthly return +1% to +3%: about 1,401 configurations (2.98%)
- Monthly return 0% to +1%: about 6,590 configurations (14.02%)
- Monthly return -1% to 0%: about 13,028 configurations (27.72%)
- Monthly return -1% or less: about 25,864 configurations (55.03%)
Ratio of positives to negatives
- Positive configurations: overallabout 17%(8,118 configurations)
- Negative configurations: overallabout 83%(38,892 configurations)
There are actually 17% configurations that look positive in backtests.These numbers up to this point are at a level where many people are happy thinking “this can win” after backtesting.
But from here, walk-forward testing (reproducing in an unseen period) collapses over 99% of the positive configurations.
Walk-Forward test (unknown period) kept positives
When selected in the training period and tested in the unknown period, the configurations that persisted areabout 9 configurations only(0.02% of the total).
Of the 17% positive configurations seen in backtests, less than 1% remained usable in real trading.
“Winning in backtests” for 99% is an illusion— this is the numerical conclusion from 47,000 configurations.
Record of the 91 standalone indicator logics
Among the 47,000 configurations, narrowing to the “standalone indicator (EA using a single indicator)” yielded even more striking results.
Out-of-Sample mean expectation for the 91 standalone indicator logics
For each major indicator family, the average expectation in Out-of-Sample (unknown period) is listed. The numbers are averages over multiple parameters.
- RSI family (average across all parameters): Expectation -0.023R
- MACD family: Expectation -0.041R
- Stochastic family: Expectation -0.038R
- ADX family: Expectation -0.029R
- Bollinger Bands family: Expectation -0.045R
- Donchian family: Expectation -0.058R
- MA Cross family: Expectation -0.042R
- Keltner family: Expectation -0.040R
- Ichimoku family: Expectation -0.056R
- PSAR family: Expectation -0.033R
All indicator families are negative. Not a single family had a positive average.
The sole exception within the 91 logics: RSI(28)
The overall average is negative, but when looking at parameters individually, there was exactly one exception.
- RSI(28) Daily chart, contrarian: Out-of-Sample expectation+0.101R
Among the 91 logics across all parameters, only this one produced a statistically significant positive result.The sole remaining standalone indicator edge with a 0.02% probability.
Why RSI(28) Daily only remained (discussion)
Reason RSI(28) performed exceptionally:
- The RSI’s textbook default value (14) is opposite and negative (-0.069R); ironically, the “settings everyone uses” are the worst
- RSI(28) captures longer-term momentum reversals. On EURUSD daily, it reverses after absorbing short-term RSI false signals
- The daily timeframe itself minimizes the impact of costs (spread + slippage)
There is an exceptional edge that goes against textbook conventional wisdom, and that was an important takeaway from standalone indicator testing.
From here on,the reasons for the best/worst values by system, why the MTF environment recognition gate 3,552 configurations couldn’t save them, the meaning of mo/DD ceiling 0.149 for a standalone EA, the 6.7x distance to target 1.0, and the numerical basis for the conclusion that diversification is the remaining pathwill be written.
Continuing from here (for viewing):
- System-specificParameter sensitivity ── full comparison of best and worst values (RSI/Keltner/BB/Donchian/MA)
- MTF environment recognition gaterecords that 3,552 configurations could not save (gate × session 33 cells with only 1 positive)
- The meaning of the mo/DD ceiling 0.149 for a standalone EA, and distance of 6.7x to the target 1.0
- The remaining path is diversification ── the conclusion indicated by the tuition of 47,000 configurations
- In diversification design, an example where a retail EA with mo/DD 0.32 exceeded Walk-Forward OOS 0.49 by more than 1.5x